
Digital download
Access the files immediately after checkout.
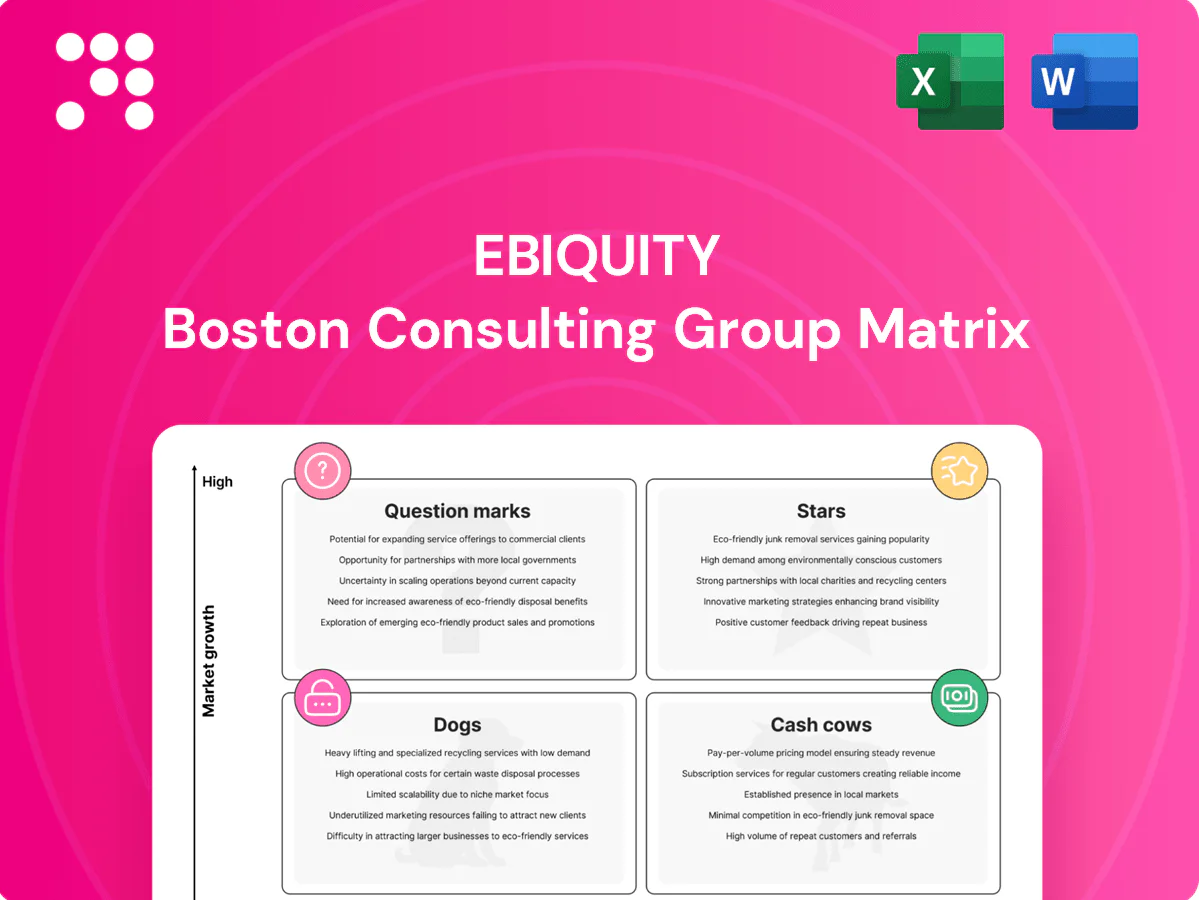
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Ebiquity’s services and offerings really sit—Stars, Cash Cows, Dogs or Question Marks? This snapshot hints at the story; buy the full BCG Matrix for quadrant-by-quadrant placement, data-driven recommendations, and a clear investment roadmap. Purchase now for a ready-to-use Word report and an Excel summary you can act on immediately.
In 2024 brands are prioritising provable ROI and waste-cutting, driving high-growth demand for independent media performance analytics. Ebiquity’s independent stance wins trust and has been gaining share in the rapidly expanding analytics market. Continued investment in proprietary data assets, faster benchmarks and platform integrations is required to cement leadership. If momentum continues, this Star can mature into a predictable cash engine.
Regulation, rising ad-fraud risk (estimated $44bn globally in 2024) and complex cross-border supply chains make transparency and media accountability a must-have in the BCG Stars quadrant. Ebiquity’s reputation drives share gains as category spend grows; market share can rise with continued thought-leadership. The space requires sustained client education budgets and sharper diagnostics. Public proof points and verified case studies will sustain the edge.
Brands now demand decisions tied to outcomes, not vibes, driving marketing effectiveness consulting toward a growth runway with client engagements up ~30% year-on-year and measurable ROI targets standard across briefs.
Advisory plus evidence is scaling fast; Ebiquity’s industry credibility and proprietary measurement tools convert briefs into retainers, supporting premium fee capture and improving client retention rates materially.
Meeting this demand requires senior talent and robust frameworks; nailing delivery quality now is essential to lock in predictable, high-margin cash flows and cement future cash-cow status.
Digital media cost benchmarking is a Star: programmatic, social and commerce CPMs swing 20–45% Q/Q, so Ebiquity’s datasets (covering $30bn+ campaign spend) enable fair-value calls that won 15 global accounts in 2024; continuous ingestion and quarterly methodology refresh keep accuracy high as digital ad spend (~$600bn in 2024) grows.
Multi-market guidance is expanding as global ad spend reached roughly $911bn in 2024, with platforms capturing the majority of growth; Ebiquity’s neutral footprint across 20+ markets positions it to lead cross-border advisory. Double down on governance, unified data views and executive access to protect share now and harvest later.
Ebiquity’s independent media analytics is a 2024 Star: $30bn+ campaign coverage, 15 global wins, and demand up ~30% Y/Y as brands chase provable ROI. Digital ad spend ~$600bn and global ad spend ~$911bn amplify growth while $44bn ad-fraud risk and regulation raise barriers to entry. Continued data ingestion, quarterly methodology refresh and senior talent are required to convert growth into a cash-cow.
| Metric | 2024 |
|---|---|
| Coverage | $30bn+ |
| Global wins | 15 |
| Demand growth | ~30% Y/Y |
| Digital ad spend | ~$600bn |
| Global ad spend | ~$911bn |
| Ad-fraud risk | $44bn |
| Markets | 20+ |
 Detailed Word Document
BCG Matrix review of Ebiquity’s portfolio with strategic guidance—which units to invest in, hold or divest by quadrant.

 Customizable Excel Spreadsheet
One-page Ebiquity BCG Matrix placing each business unit in a quadrant to cut analysis time and simplify executive decisions.
Traditional TV buying benchmarks remain a mature category with stable demand from big advertisers, accounting for roughly 30% of global ad budgets in 2024 (MAGNA/GroupM consensus). Ebiquity holds a strong share of strategic TV buying and delivers reliable margins, with group revenue reported near £150m in 2024. Incremental automation (10–20% efficiency uplift typical in programmatic pilots) can lift productivity. Milk the business while preserving accuracy and client trust.
Media compliance and contract audits sit in a mature, steady segment with recurring demand and predictable workload observed through 2024. High credibility with global advertisers converts to reliable cash flow and strong renewal momentum. Maintain tight processes, short cycle times, and focus on upselling adjacent services to lift yield. Minimal promotional spend is required due to established reputation.
Agency pitch management is a well-understood, repeatable offering delivering consistent volume in mature markets, with Ebiquity frequently on shortlists and achieving above-average win rates. Standardized toolkits protect margin and reduce delivery cost. Cash flow from this cash cow funds newer growth bets and innovation investments.
Quarterly performance dashboards are cash cows in Ebiquity's BCG matrix, serving established clients with rhythm reporting; 2024 retention for reporting services exceeds 90% and ARPU ≈ £12,000. Optimize delivery with templates and light automation to cut delivery time ~30% and protect margins. Maintain, don’t overinvest.
Long-term enterprise retainers deliver locked-in advisory support with strong renewal patterns and high share of wallet across existing clients, in a slow-growth category; maintaining low churn via executive relationships and outcome-linked KPIs keeps margins predictable. This steady cash flow funds growth bets and innovation across Ebiquity’s portfolio.
Traditional TV, audits, pitch management, dashboards and retainers generate steady margins for Ebiquity in 2024: group revenue ≈ £150m, TV ~30% of global ad budgets, reporting retention >90% and ARPU ≈ £12,000. Automation (10–20% efficiency uplift; ~30% delivery time cut) should be used to maintain margins and fund growth bets.
| Service | 2024 metric | Action |
|---|---|---|
| TV buying | £150m group rev; TV ~30% | Milk; efficiency |
| Reporting | Retention >90%; ARPU £12k | Templates + light automation |
The file you're previewing is the exact Ebiquity BCG Matrix report you'll receive after purchase. No watermarks, no demo content—just the fully formatted, analysis-ready document designed for strategic clarity. After buying you'll get the same editable, print-ready file delivered instantly to your inbox, ready for presentations or internal planning. No surprises—just a professional tool you can plug straight into your workflow.
Legacy print rate audits sit in Dogs: market for print has collapsed as budgets shifted to digital; U.S. newspaper ad revenue is down about 70% since 2006 and print now represents single-digit share of global ad spend. Low market share, waning demand and thin margins mean turnarounds rarely pay back. Recommend sunset or fold into broader audit bundles only when cost-justified.
Dogs: Standalone on-premise tools face declining demand as clients prefer cloud and managed services; Gartner 2024 notes up to 70% of IT spend is consumed by maintenance, trapping cash in support rather than growth. These assets show weak differentiation and minimal market growth, with shrinking usage and margin pressure. Migrate to cloud or retire products to free resources and reinvest in scalable services.
Small-market bespoke studies are project-by-project work in tiny markets with low repeatability and typically under 5% revenue share, limiting scale and upside. Cost-to-sell and deliver often exceed incremental margin, eroding profitability and diverting resources from scalable accounts. Recommend divestment or strict standardization unless margins can be demonstrably improved in 2024.
Dogs:
Generic media directories sit in Dogs: easily substitutable, fully commoditized, and offer little perceived value in a market flooded with free sources. 2024 surveys show ~80% of marketers prioritize first-party/proprietary insight over third-party directories. Incremental spend is unwarranted; exit and reallocate to proprietary intelligence.
Legacy print audits, on‑prem tools, bespoke micro‑studies and one‑off workshops sit in Dogs: print ad revenue down ~70% since 2006 and under 5% share of global ad spend (2024); Gartner 2024 flags 60–70% IT spend on maintenance. Low share, shrinking markets and thin margins — sunset or migrate to bundled/cloud offerings.
| Asset | 2024 metric | Action |
|---|---|---|
| Print audits | -70% since 2006; <5% ad spend | Sunset |
| On‑prem tools | 60–70% IT maintenance | Migrate/retire |
Retail media measurement is in explosive growth, about +25% YoY to roughly $100bn global spend in 2024, yet category standards and attribution norms are still forming. Ebiquity’s independence and audit credentials can win trust as advertisers seek neutral measurement, but its current share is nascent. Prioritize clean-room partnerships and SKU-level ROI capabilities to prove incrementality. Move fast or this could drift into the dog quadrant as platforms consolidate scale.
CTV and streaming attribution sits as a Question Mark: a high-growth channel (global CTV ad spend ≈$25bn in 2024, ~20% YoY) with messy identity and ~75% inventory concentrated in walled gardens. Big upside exists if Ebiquity proves incrementality at scale — potentially unlocking materially higher media ROI. Priorities: build connectors, run controlled experiments, and deliver validation frameworks. Decide quickly whether to invest deeply or partner to scale.
Marketers are demanding beyond-viewability signals as attention-based metrics gain prominence, with IAB 2024 guidance encouraging attention measurement alongside viewability and fraud controls. Ebiquity can standardize and benchmark attention and media quality across channels, but adoption remains nascent with pilots underway among flagship clients to build proof. If those pilots scale and traction grows, this Question Mark can transition into a Star.
AI assistants for planners are booming but crowded; ChatGPT reached ~100 million monthly active users by Jan 2023 and PwC projects AI could add up to 15.7 trillion USD to global GDP by 2030, underscoring demand. Ebiquity’s proprietary media, pricing and outcome datasets could power a differentiated planning copilot, but success requires productization, robust governance and operational guardrails. Bet selectively with lighthouse users to de-risk rollout and capture early ROI.
Unified MMM plus MTA sits as a Question Mark: privacy-driven cookie deprecation (Google phased third-party cookie changes into late 2024) and CFOs insisting on causality lift demand, letting Ebiquity combine consultancy with a productized spine, but market share is emerging; invest in modular models, rapid experimentation and speed, scale only if win rates validate unit economics.
Retail media, CTV, attention, AI planning and unified MMM/MTA are Question Marks for Ebiquity: high-growth (retail media ≈100bn USD 2024; CTV ≈25bn USD 2024) but standards, identity and productization lag. Ebiquity’s audit credentials and proprietary datasets create a moat; prioritize clean-room/SKU ROI, connectors, controlled experiments and lighthouse pilots. Decide rapidly to invest, partner or divest as platforms consolidate and cookieless shifts occur in late 2024.
| Tag | 2024 size | Priority |
|---|---|---|
| Retail media | ≈100bn USD | SKU ROI |
| CTV | ≈25bn USD | Connectors & experiments |
| Attention | nascent | standardize pilots |


