
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
Discover how political shifts, economic trends, and sustainability pressures shape Elis’s strategic outlook in our concise PESTLE overview. This snapshot highlights risks and opportunities for investors and managers. Buy the full analysis to access detailed, actionable insights and ready-to-use templates for immediate decision-making.
Government procurement rules in healthcare, hospitality and public services set detailed accreditation, sustainability and price-cap clauses that directly shape Elis margins and contract terms. The EU public procurement market is roughly €2 trillion annually (European Commission), so SME quotas and local-supplier preferences materially alter bid competitiveness. Policy shifts toward longer framework agreements favor scale players like Elis, while public budget cuts can delay renewals and compress pricing.
Stricter national infection-control standards boost demand for certified laundering and hygiene services; WHO estimates about 4.1 million patients affected by healthcare-associated infections in Europe annually, underpinning uptake. Public health campaigns often mandate higher linen/workwear changeout rates, while subsidies for hospitals and eldercare favor outsourced solutions; Elis operates in 28 countries and serves ~300,000 customers, exposing it to policy-driven volume swings. Policy relaxation could soften non-critical segment volumes.
Tariffs, customs frictions and border checks raise input costs for Elis by squeezing textile imports and equipment spare parts, with average EU external tariffs around 5% on textiles and customs delays adding days to lead times. EU trade agreements (40+ partners by 2024) and the Single Market streamline cross-border operations across Elis’s footprint. Red Sea and Russia-Ukraine related tensions pushed freight volatility and led to spot-rate spikes up to ~30% in 2023–24, increasing lead times and inventory costs. Growing localization and nearshoring trends—surveyed by 2024 with ~45% of EU manufacturers considering regional sourcing—could shift Elis toward more regional suppliers and higher procurement CAPEX.
Minimum wage rises increase Elis's processing and route-service costs given a workforce of about 49,000 employees (2023 annual report); statutory increases across key EU markets in 2024–25 pressured hourly labor costs. Collective bargaining in France, Spain and UK constrains staffing flexibility, while training subsidies and employment incentives (national schemes) can partly offset payroll inflation; immigration rules affect labor supply.
Public procurement rules (EU market ~€2tn) and longer framework agreements favor scale players like Elis (2023 revenue €6.1bn) but budget cuts can compress pricing. Infection‑control mandates (≈4.1M HAI cases Europe) and stricter standards raise demand for outsourced hygiene services. Tariff averages ~5% on textiles and 2023–24 freight spikes up to ~30% increased input costs. Workforce 49,000; wage hikes 2024–25 press OPEX.
| Factor | Key metric | Impact |
|---|---|---|
| Procurement | €2tn EU | Improved win rates |
| Health policy | 4.1M HAI | Higher volumes |
| Trade | 5% tariffs/30% freight | Raised input costs |
| Labor | 49,000 employees | Wage pressure |
 Detailed Word Document
Explores how external macro-environmental factors uniquely affect Elis across six dimensions—Political, Economic, Social, Technological, Environmental and Legal—backed by current data and trends to identify threats and opportunities. Designed for executives and investors, the analysis is region- and industry-specific, forward-looking, and delivered in clean formatting ready for plans, decks, or reports.

 Customizable Excel Spreadsheet
Concise, visually segmented PESTLE summary for Elis that highlights key political, economic, social, technological, legal and environmental risks and opportunities, ready to drop into presentations or share across teams for faster alignment and decision-making.
Elis shows clear cycle exposure: hospitality and foodservice volumes swing with the economy while healthcare and pharma remain more resilient; hospitality occupancy-driven linen demand fell sharply in 2020 but recovered by 2023–24 as travel returned. Elis reported ~€3.9bn revenue in 2024 with healthcare/pharma around 40%, and diversification across sectors and 28 countries smooths volatility, creating upsell opportunities during recovery phases.
Energy, water, detergents and textiles remain key cost drivers for Elis, with Euro area inflation easing to about 2.4% in 2024 but input-price volatility persisting after the 2022 shock. Elis leverages index-linked contracts to pass through increases with a lag, and its procurement scale and long-term supplier agreements dampen short-term swings. Persistent inflationary pressure continues to stress working capital and capex planning into 2025.
Elis faces multi-currency revenue and cost exposure across EUR, GBP, CHF and LatAm markets, with the group reporting roughly €4.0bn revenue in 2024, amplifying FX translation and transaction risk. Hedging policies smooth reported earnings volatility but do not eliminate translation effects on consolidated results. Higher global policy rates — circa 4%–5% in major markets in mid‑2025 — lift financing costs for capex‑heavy laundries and M&A; eventual rate cuts would ease refinancing and investment cycles.
Highly fragmented local markets create roll-up opportunities for Elis; the group, present in 28 countries and reporting €4.77bn revenue in 2023, can pursue bolt-ons to build scale. Synergies stem from higher route density, improved plant utilization and centralized procurement, driving margin expansion. Antitrust scrutiny and macro conditions (interest rates, valuation multiples) constrain deal sizes, divestments and integration pacing.
Elis faces cyclicality: hospitality volumes fell in 2020 but recovered; healthcare/pharma ~40% of ~€3.9bn revenue in 2024, smoothing swings. Energy, water and detergents drive costs amid Euro area inflation ~2.4% in 2024; index‑linked contracts and procurement scale mitigate pass‑through. Multi-currency exposure and 4–5% policy rates in mid‑2025 raise financing costs; labor tightness (EU unemployment ~6.1% in 2025) lifts wage pressure.
| Metric | Value |
|---|---|
| Revenue 2024 | ~€3.9bn |
| Healthcare share | ~40% |
| Euro area inflation 2024 | 2.4% |
| EU unemployment 2025 | ~6.1% |
| Policy rates mid‑2025 | 4–5% |
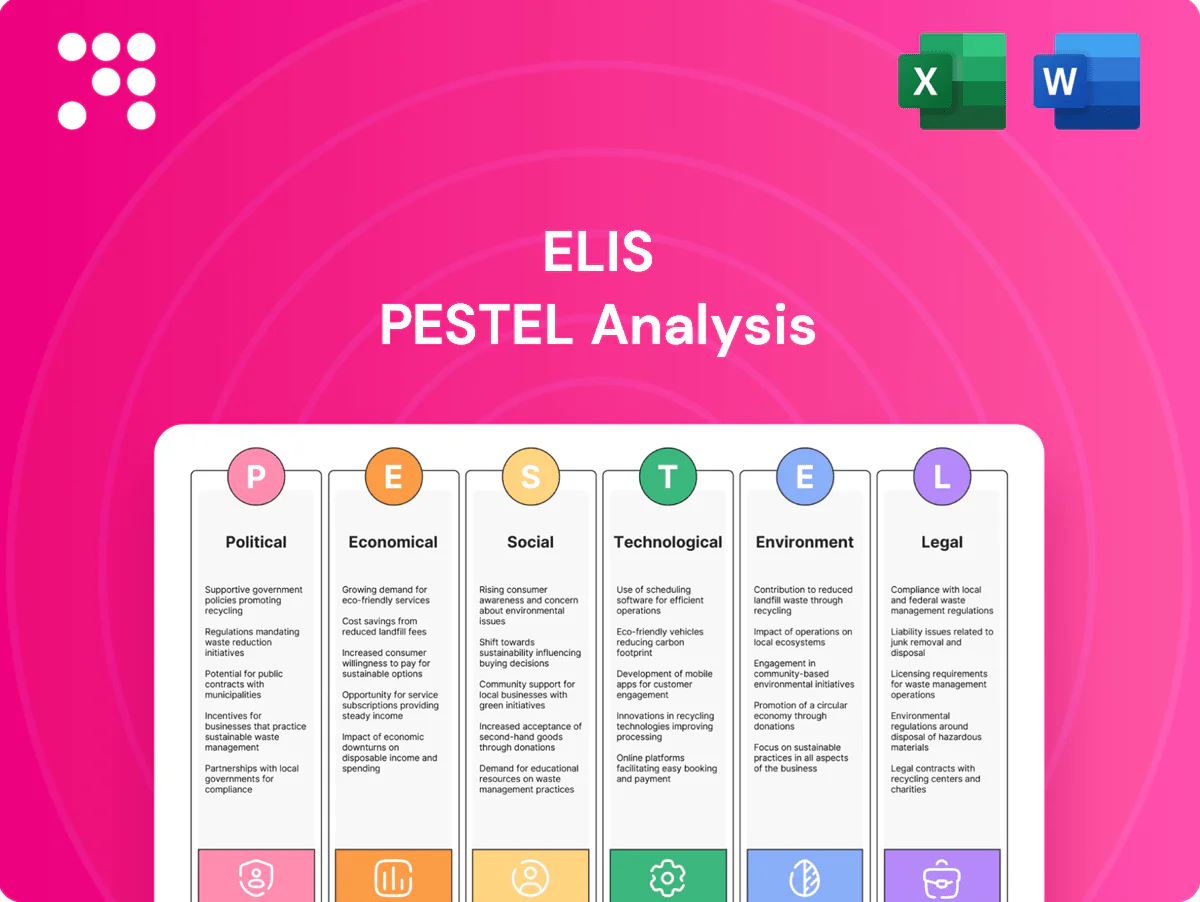
The Elis PESTLE Analysis preview shown here is the exact document you’ll receive after purchase—fully formatted, professionally structured, and ready to use. This is a real screenshot of the product with no placeholders or teasers, so the content and layout match the downloadable file exactly. After payment you’ll instantly get this same finished document, complete and ready for immediate use.
Post-pandemic cleanliness expectations remain high: a 2024 Deloitte survey found 71% of consumers factor hygiene into venue choice, boosting demand for certified linen and workwear processes with full traceability; Elis reported hygiene-related contracts up 9% in 2024. Visible washroom dispensers and mats increase customer reassurance and support premiumization and cross-sell opportunities.
Businesses increasingly outsource non-core operations to focus on strategy; in textile and hygiene services this trend fuels demand for specialists like Elis, which reported pro forma revenue of about €4.7bn and ~48,000 employees in 2023. Linen and hygiene require regulatory compliance and capital expenditure, prompting clients to externalize these costs. SLAs and KPI frameworks—standard in contracts—formalize expectations and reduce risk. Reliability and responsiveness drive retention, with repeat-contract rates key to lifetime value.
Aging populations (EU 65+ at 20.8% in 2023 per Eurostat) expand healthcare and eldercare linen需求, supporting stable volumes for Elis. Diverse, multilingual workforces require tailored training and safety programs. Flexible schedules and ergonomic workplaces improve retention in tight labor markets (EU unemployment 6.1% in 2024), and employer reputation strongly influences recruiting.
Customers and end-users now scrutinize water, energy and chemical footprints when selecting textile and linen services; transparent reporting and eco-labels materially differentiate offerings. ESG ratings increasingly determine tender outcomes, especially with large corporates and public bodies—public procurement represents about 14% of EU GDP. Reusable models can be positioned as circular alternatives to disposables, lowering lifecycle waste and demonstrating measurable footprint reductions.
Concentration of clients in cities boosts route density and plant utilization, with about 75% of EU residents living in urban areas (Eurostat 2022), improving load factors but increasing delivery time pressure. Traffic congestion and tight delivery windows demand precise route planning and real-time telematics. Micro-hubs or satellite depots raise responsiveness; noise and neighborhood rules constrain operating hours.
Post-COVID hygiene demand remains high (71% consider hygiene in venue choice, Deloitte 2024), boosting certified linen/workwear uptake; Elis pro forma revenue ~€4.7bn (2023). Aging EU population 65+ =20.8% (Eurostat 2023) supports healthcare linen volumes. 75% urbanization raises route density and plant utilization (Eurostat 2022).
| Metric | Figure |
|---|---|
| Hygiene concern (Deloitte) | 71% (2024) |
| Elis pro forma revenue | €4.7bn (2023) |
| EU 65+ | 20.8% (2023) |
| EU urbanization | 75% (2022) |
Embedded RFID tags enable piece-level tracking of linens and workwear, cutting losses by up to 30–50% and driving inventory accuracy above 95%, which improves billing accuracy by ~15–25%. Clients gain real-time visibility into usage and hygiene cycles, supporting predictive replacement that can reduce replacement costs ~10–20% and strengthen SLA compliance.
Automated sorting, folding and packing raise throughput and consistency, with industry reports showing automation can lift processing rates by 30-50% in textile and laundry operations; global robot installations reached 517,385 new units in 2022 (IFR). Robotics lower ergonomic strain and labor dependency, cutting injury exposure and absenteeism. Integration demands significant capex and change management, while predictive maintenance has been shown to cut unplanned downtime by up to 50% (McKinsey), crucial for ROI.
Heat recovery can cut laundry energy use by 20–40% while low-liquor-ratio washers reduce water consumption 30–50% and smart dosing trims chemical and utility use ~10–20%; on-site wastewater treatment enables reuse rates up to 70–80% improving compliance and lowering discharge costs; real-time monitoring flags deviations and can cut waste 10–15%, supporting ESG targets and enhancing operational margins.
Client portals enable ordering, inventory adjustments and SLA tracking, improving operational transparency for Elis, which operates in 28 countries with ~50,000 employees. Analytics forecast demand by sector and seasonality, supporting route and linen planning to reduce stockouts and overtime. APIs integrate with client ERP and facility systems; digital engagement strengthens stickiness and upsell via recurring service expansions.
RFID, automation, energy recovery and AI routing drive inventory accuracy >95%, reduce losses 30–50%, lift throughput 30–50%, cut energy 20–40% and route miles ~100M (UPS ORION), lowering fuel/maintenance 10–15% and improving on-time ~20%, strengthening SLAs and margins across Elis’s 28-country, ~50,000-employee footprint.
| Technology | Impact | Metric |
|---|---|---|
| RFID | Inventory & billing | Accuracy >95%; losses -30–50% |
| Automation | Throughput & labor | +30–50% processing |
| Energy & AI routing | Costs & service | Energy -20–40%; miles -100M; fuel -10–15% |
Compliance with EN/ISO standards such as EN 14065 and ISO 9001 for laundering and PPE handling is mandatory for Elis across EU operations. Healthcare textiles require validated thermal or chemical disinfection (thermal protocols commonly reference 70°C for about 10 minutes). Non-compliance risks fines, contract loss and reputational damage. Regular third-party audits and certifications underpin customer trust.
REACH (ECHA reports over 22,000 registered substances) and the Biocidal Products Regulation (EU) No 528/2012 govern Elis detergents and disinfectants, constraining permitted active substances and approval timelines. Labeling and safety data sheets must be maintained across EU and non-EU jurisdictions to remain compliant. Regulatory changes can force reformulation or supplier switches and redesign of storage/handling areas, impacting plant layout and CAPEX planning.
Working time rules such as the EU Working Time Directive 48-hour average limit and national overtime ceilings shape Elis’s rostering across its ~48,000 employees, affecting labor cost and staffing models. Strong union negotiations in core markets (notably France) influence wage growth and contractual flexibility, impacting margin pressure. Strict H&S obligations force investments in ergonomics and training to reduce incidents, while missteps can prompt litigation, sanctions and reputational costs.
Elis must comply with GDPR and equivalents for employee and client data, including RFID-linked usage, enforcing consent, purpose limitation and retention policies; non-compliance risks fines up to €20m or 4% of global turnover and remediation costs (average global breach cost ~USD 4.45m per IBM 2023 report).
Wastewater discharge, sludge handling and air emissions at Elis plants are subject to strict permits under national and EU industrial and water laws; violations can trigger stop-orders or delay plant expansions. Documented segregation of non-hazardous and hazardous waste is mandatory for compliance and traceability. Maintaining permits and permit-driven monitoring underpins Elis social license to operate in local communities.
Compliance with EN/ISO (EN 14065, ISO 9001), REACH (>22,000 substances) and BPR, GDPR (fines up to €20m/4% turnover), WTD 48h and strong unions (France) drive Elis’s CAPEX, labor costs and reformulation risk; non-compliance risks fines, contract loss and plant halts. Elis revenue €3.6bn (2024), ~48,000 employees; avg breach cost $4.45m (IBM 2023).
| Regulation | Key metric | Impact |
|---|---|---|
| GDPR | Fines €20m/4% turnover | Legal/financial risk |
| REACH/BPR | >22,000 substances | Reformulation/supply risk |
| Labor/WTD | 48h avg limit | Roster & cost pressure |
| Environmental | Permits | Operational continuity |
Laundries are water-intensive and thus vulnerable to droughts and restrictions; industry accounts for about 20% of global freshwater withdrawals while 2.2 billion people lacked safely managed drinking water in 2020 (UN). Closed-loop and reuse systems deployed by Elis can cut freshwater dependency substantially and are being rolled out at scale across high-risk sites. Site selection now explicitly factors local water stress indices and regulatory limits. Client communication on water stewardship is marketed as a value-add to corporate customers.
Elis is shifting from gas to electrification, heat pumps (COP 3–4) and on-site/PPAs — global corporate PPA volumes hit ~46 GW in 2023 — lowering CO2 and exposure to EU ETS pricing (~€90/t in 2024). Energy-price volatility accelerates capex for efficiency and PPAs; carbon reporting frameworks (CSRD, SBTi alignment) steer investments. Fleet electrification or biofuels reduces Scope 1 from direct combustion.
Elis's durable textile rental and repair services extend garment service life, reducing waste and raw-material demand; global fiber-to-fiber recycling remains below 1%. End-of-life recycling and fiber-recovery programs support circular goals and can lower disposal costs. Design-for-reuse with suppliers improves durability and laundering performance. Clients increasingly require circularity KPIs and metrics in tenders.
Elis minimizes aquatic impact through optimized dosing and greener chemistries, while on-site treatment plants routinely ensure discharges meet regulatory COD, BOD and microfiber thresholds; continuous monitoring and automated controls reduce incident risk. Certifications such as ISO 14001 and EU Ecolabel validate these eco-friendly processes and operational controls.
Floods, heatwaves and storms increasingly threaten Elis plants and distribution networks across its 28-country footprint, disrupting production and logistics; resilience planning focuses on site hardening and backup utilities to maintain continuity. Insurance premiums rose sharply in 2024 (circa 15% in Europe), increasing OPEX via higher premiums and larger deductibles.
Elis faces high water dependency—laundries drive significant freshwater use amid global stress (industry ~20% withdrawals; 2.2bn without safe water in 2020), so closed-loop reuse is scaling. Energy transition (heat pumps, electrification, PPAs) cuts CO2 and ETS exposure (EU ETS ~€90/t in 2024; corporate PPAs ~46 GW in 2023). Circularity reduces waste (fiber-to-fiber recycling <1%) while extreme weather and a ~15% insurance cost rise in 2024 raise resilience costs.
| Metric | Value |
|---|---|
| Freshwater dependency | Industry ~20% |
| People without safe water (2020) | 2.2bn |
| Corporate PPAs (2023) | ~46 GW |
| EU ETS price (2024) | ~€90/t |
| Insurance cost rise (2024) | ~15% |
| Fiber-to-fiber recycling | <1% |


