
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Equity LifeStyle's SWOT preview highlights resilient portfolio strength, premium location assets, and recurring cash flows, against rising interest rates, regulatory pressures, and demographic shifts. Discover the full strategic implications, financial context, and risk mitigants in our complete SWOT report. Purchase the full, editable Word + Excel package to plan, pitch, or invest with confidence.
Leasing homesites on long-term terms generates stable, high-visibility revenue with low turnover—Equity LifeStyle’s portfolio of over 140,000 sites delivers recurring lot-rent cash flows that are less volatile than apartment rents because moving costs are high. That underpins consistent same-community NOI growth in the low-single-digit range and supports dividend stability (dividend yield roughly 3–4% in 2024–2025), buffering earnings through cycles.
Zoning restrictions and strong community opposition keep new manufactured housing communities scarce, helping ELS sustain portfolio occupancy above 96% and national lot rent growth near 5% in 2024. Scarce supply gives pricing power for existing assets, protecting margins and NAV. Structural undersupply limits competitive threats from new builds and supports long-term asset value retention.
Equity LifeStyle Properties (NYSE: ELS) leverages a diversified portfolio of manufactured housing, seasonal RV resorts, and vacation cottages to balance differing demand drivers; long-term MH residents provide stable cash flow while RV and cottage guests supply higher-margin, short-stay revenue, enabling year-round utilization and amenity cross-selling that enhances resilience and revenue optionality.
Equity LifeStyle leverages a lifestyle and amenity-driven model that boosts resident stickiness through resort-style experiences and community programming, enabling sustained retention and higher lifetime value.
The focus on amenity upgrades supports rent growth and premium pricing while branded consistency improves marketing efficiency and occupancy.
Equity LifeStyle’s capital-efficient model — operating roughly 460+ communities — benefits from resident-owned homes that substantially reduce landlord responsibilities versus traditional apartments; site infrastructure and amenity investment is required, but unit-level capex is limited, supporting higher margins and stronger free cash flow conversion and enabling accretive reinvestment and acquisitions.
Stable, recurring lot-rent from ~140,000+ sites yields low-volatility cash flow with same-community NOI growth in low-single-digits and dividend yield ~3–4% (2024–25). Occupancy >96% and national lot rent growth ~5% in 2024 reflect pricing power amid scarce new supply. Diversified mix (460+ communities) and resident-owned homes cut unit capex, boosting margins and FCF conversion.
| Metric | 2024/25 |
|---|---|
| Sites | ~140,000+ |
| Occupancy | >96% |
| Lot rent growth | ~5% (2024) |
| Communities | 460+ |
| Dividend yield | ~3–4% |
 Detailed Word Document
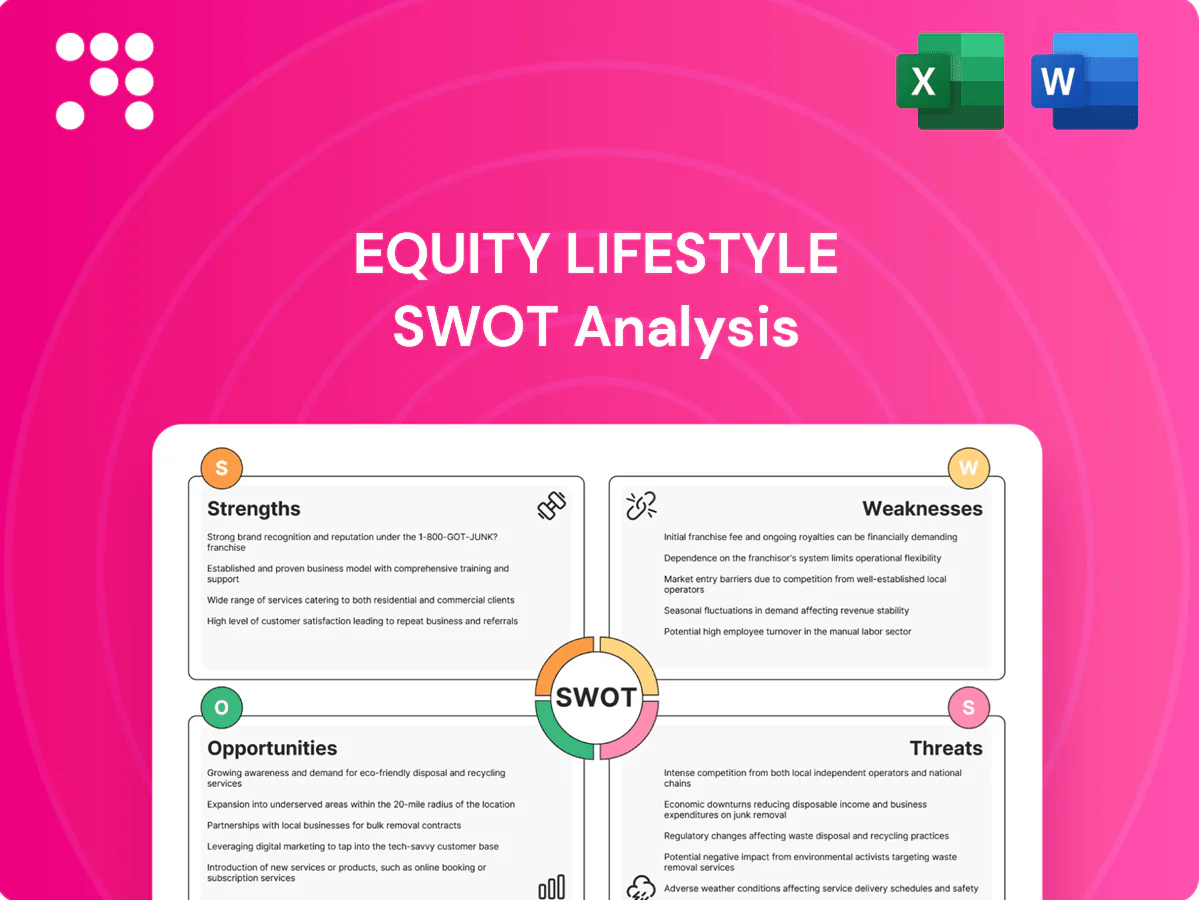
Provides a strategic overview of Equity LifeStyle’s internal strengths and weaknesses and external opportunities and threats, mapping competitive position, growth drivers, operational gaps, and market risks to inform investor and management decisions.

 Customizable Excel Spreadsheet
Provides a concise SWOT snapshot of Equity LifeStyle to quickly pinpoint operational risks and growth levers for faster investment and portfolio decisions.
As a REIT, Equity Lifestyle’s valuation and growth hinge on access to affordable debt and equity; with the 10-year Treasury rising above 4% in 2024, higher rates pressure cap rates, acquisition spreads, and development yields. Rising borrowing costs increase interest expense and can compress FFO growth. Elevated rates may limit external growth opportunities by raising financing costs and narrowing deal economics.
RV and campground revenues for Equity LifeStyle are highly seasonal, concentrated in spring–summer travel months, so a large share of annual cash flow occurs in Q2–Q3 and drives uneven quarter-to-quarter earnings. Adverse weather and extreme events (NOAA recorded 28 billion-dollar disasters in 2023 totaling $61.3B) can sharply cut occupancy and ancillary spend. Operational planning and liquidity must absorb this volatility to protect margins and NOI.
Manufactured housing communities face rent cap initiatives in several states and municipalities, threatening revenue upside; roughly 6.5 million US households live in manufactured homes. Public scrutiny over affordability can limit rent growth or raise compliance costs, potentially depressing NOI trajectories and constraining pricing strategy. Such policy risk may weigh on investor sentiment and valuation multiples.
Equity LifeStyle's concentration in Sunbelt and coastal markets places many communities in hurricane, flood, and wildfire zones, increasing insurance and mitigation costs and exposure to the 28 billion-dollar U.S. weather/climate disasters in 2023 (NOAA). Catastrophic events can damage assets, impair cash flow, and prolong recovery timelines, amplifying earnings volatility.
Limited organic pipeline: zoning resistance constrains ground-up community development, forcing Equity LifeStyle to depend on acquisitions and expansions of existing sites; in 2024 ELS reported roughly 466 communities and growth remained acquisition-driven, raising competition for quality assets and pushing purchase prices higher, which can reduce accretion and slow scale-up.
As a REIT, ELS faces higher financing costs with the 10-year Treasury >4% in 2024, compressing cap rates and FFO growth. RV and campground revenues are highly seasonal and weather-sensitive; NOAA recorded 28 billion-dollar disasters in 2023 totaling $61.3B. Rent-cap and affordability pressures threaten manufactured housing upside; ~6.5M US households live in manufactured homes. Growth is acquisition-dependent: ~466 communities in 2024, limiting organic pipeline.
| Metric | Value |
|---|---|
| 10-yr Treasury (2024) | >4% |
| Billion-dollar disasters (2023) | 28 / $61.3B |
| Manufactured-home households | ~6.5M |
| Communities (2024) | ~466 |
This is the actual Equity LifeStyle (ELS) SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report; buy to unlock the complete, editable version. The file shown is the real analysis you'll download after payment.
As US baby boomers age — the Census projects about 73 million Americans will be 65+ by 2030 — demand for affordable, lower-maintenance housing rises and fixed-income households increasingly seek cost-effective options. Manufactured housing, which made up roughly 6% of the US housing stock per the 2020 Census, offers materially lower price points than site-built homes and many rentals, supporting high occupancy and steady rent growth while expanding ELSs addressable resident base.
Independent owners control the majority of the roughly 50,000 U.S. manufactured-home and RV communities, presenting roll-up opportunities for Equity LifeStyle. A disciplined acquisition strategy can realize scale efficiencies and be accretive to FFO per share while platform capabilities in revenue management and amenities unlock rental and ancillary revenue upside. Deepening market presence via targeted roll-ups strengthens pricing power and occupancy gains.
Site expansions, infill and utility upgrades typically add 10–15% more pads and lift rents 6–10%, while amenity investments (clubhouses, pools, resort upgrades) can command 7–12% pricing premiums and extend stays 5–8%. Ancillary revenues (storage, premium Wi‑Fi, paid activities) commonly boost ARPU 5–10%, and these value‑add projects often target mid‑teens IRRs on a risk‑adjusted basis.
Digital and operational optimization via proptech—reservations engines, dynamic pricing and resident portals—can raise lot utilization and RevPAR; 2024 studies show dynamic pricing lifts revenue 8–12% and booking conversion ~15%. Data-driven marketing improves shoulder-season resort demand by 10–18% (2024). Automation trims operating costs 5–10%, boosting EBITDA margins and resident satisfaction.
Resilience investments—storm hardening, flood mitigation and on-site renewables—can lower operating risk and reduce expenses; studies show ESG improvements often cut cost of capital by roughly 10–50 basis points while enabling insurance savings and fewer operational disruptions that stabilize cash flow and protect long-term asset value for Equity LifeStyle.
Demographic tailwinds (≈73m 65+ by 2030) and manufactured housing’s ~6% share create demand for ELS’s affordable, lower-maintenance product. Roll-ups across ~50,000 communities plus site expansions (pads +10–15%, rents +6–10%) and amenity/ancillary upside (7–12% premium; ARPU +5–10%) can drive FFO accretion. Proptech/marketing/automation (rev +8–12%, demand +10–18%, costs −5–10%) and ESG (−10–50 bps CoC) boost returns.
| Metric | Range/Value |
|---|---|
| 65+ population (2030) | ≈73M |
| Manufactured housing share | ~6% |
| Communities | ~50,000 |
| Site expansion pads | +10–15% |
| Rent lift | +6–10% |
| Proptech revenue | +8–12% |
Sustained higher policy rates (Fed funds 5.25–5.50% and 10‑yr Treasury ~4.5% in mid‑2025) push ELS borrowing costs higher and compress acquisition returns. Cap‑rate expansion of roughly 100 basis points across CRE since 2021 can reduce NAV and blunt deal accretion. Increased equity issuance to fund growth is more dilutive, slowing external expansion and weighing on total returns.
More frequent hurricanes, floods and wildfires elevate property damage risk for Equity LifeStyle; NOAA recorded 28 separate billion-dollar U.S. weather/climate disasters in 2023 totaling about $82 billion, underscoring rising exposure. Insurance premiums and deductibles may rise materially, squeezing margins and raising policy non-renewal risk. Business interruption from evacuations and repairs can disrupt seasonal revenue peaks, while cumulative damage increases long-term asset impairment risk.
Local and state initiatives — e.g., California’s AB 1482 cap (5% plus regional CPI) and expanded municipal tenant protections — may impose rent caps, longer notice periods, or fee limits that reduce pricing flexibility. Compliance with varied rules across states increases legal and administrative costs and operational complexity. Constraints on rent growth compress NOI for a portfolio concentrated in family and age-restricted communities, while policy shifts around the 2024 US election cycle heightened planning uncertainty.
Recessions, fuel spikes (US gasoline peaked ~$4.11/gal June 2022) or health scares can sharply curb RV travel and discretionary stays; US hotel RevPAR fell ~47% in 2020, illustrating short-stay elasticity. Mixed-portfolio diversification lowers but does not remove demand swings and forecast error risk rises at resort assets.
Institutional buyers and REIT peers have intensified bidding for high-quality manufactured-home and RV assets, putting upward pressure on prices; cap rates compressed to mid-single digits in 2024, lowering forward returns. Competitors increasingly outspend on amenities and marketing, risking share and pricing power in select markets.
Higher policy rates (Fed funds 5.25–5.50%, 10‑yr ~4.5% mid‑2025) and ~100bps cap‑rate expansion since 2021 raise borrowing costs and compress NAV; mid‑single‑digit cap rates in 2024 limit forward returns. Climate losses (28 US billion‑dollar disasters in 2023, ~$82B) and rising insurance/repair costs increase impairment risk. Demand shocks (RevPAR -47% in 2020), fuel spikes and regulatory rent caps erode NOI and growth optionality.
| Threat | Metric | Impact |
|---|---|---|
| Rates/cap rates | Fed 5.25–5.50%, cap +100bps | Higher financing costs, lower NAV |
| Climate/insurance | 28 events, $82B (2023) | Rising premiums, impairments |
| Demand/regulation | RevPAR -47% (2020), rent caps | Compressed NOI, growth limits |


