
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
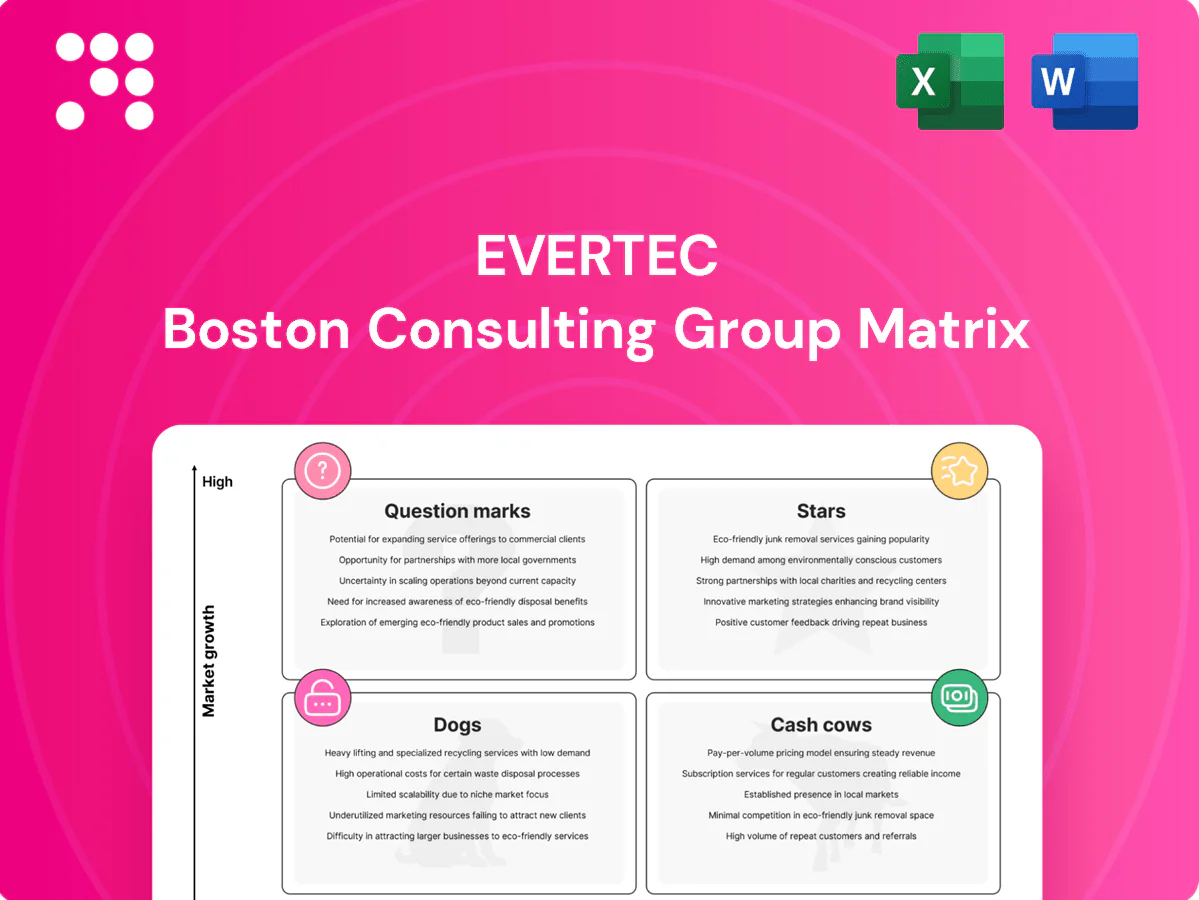
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
The EVERTEC BCG Matrix snapshot shows where its payment products sit today—who’s winning market share, who’s funding growth, and where risks hide. Want the full picture? Purchase the complete BCG Matrix for quadrant-by-quadrant placements, data-driven recommendations, and an actionable plan to reallocate capital and boost returns. It’s delivered in Word and Excel so you can present and act immediately—skip the guesswork and get strategic clarity now.
EVERTEC leads Puerto Rico merchant acquiring with deep bank partnerships and the densest POS footprint on the island. The market is rapidly shifting to digital and contactless, driving climbing transaction volumes. Defending share requires continued spend on terminal upgrades and partner promotions. Sustained investment can convert the current surge into durable cash flow.
Real-time payments rails are scaling across Puerto Rico and the Caribbean with instant transfers and account-to-account use cases growing rapidly; by 2024 over 60 countries operated real-time systems, underscoring broad momentum. EVERTEC’s incumbent infrastructure gives it a head start and early regional share, though growth soaks up capex and bank-onboarding costs. Double down now to lock in network effects.
Online checkout and tokenized payments are surging in LatAm, with card-not-present volumes up roughly 25% YoY in 2024 and regional e-commerce GMV approaching USD 200B, positioning EVERTEC in the flow via gateway, risk, and settlements to capture the mix shift. Market growth is high and EVERTEC retains solid share in core geographies (Puerto Rico, Caribbean, Mexico). Continue expanding PSP partnerships and alt-pay support to remain first call.
Government disbursements are shifting from checks to cards and accounts; EVERTEC already powers core rails across Puerto Rico, Caribbean and growing US programs, so once embedded program volumes expand and stick. Growth is strong while adoption ramps, but scaling requires compliance and service investments to meet government SLAs. Worth the spend to cement category leadership in 2024.
Fraud and risk services sit in the Stars quadrant as chargeback pressure and rising cross‑border traffic make controls mission critical; EVERTEC leverages issuing and acquiring signals from billions of annual transactions across Puerto Rico, the Caribbean and Latin America to boost model quality and win rates. Demand is climbing with ecommerce expanding >10% annually, keeping the business in the fast lane; invest to widen the moat via real‑time decisioning and machine learning.
EVERTEC’s Stars (merchant acquiring, real‑time rails, online payments, gov disbursements, fraud services) show high growth and share: CNP +25% YoY (2024), LatAm e‑commerce GMV ≈ USD 200B, real‑time in 60+ countries (2024). Sustained capex and compliance spend will convert surge into durable cash flow and widen a data-driven moat.
| Segment | 2024 Growth | Key metric |
|---|---|---|
| CNP/payments | +25% YoY | GMV ≈ USD 200B |
| Real‑time rails | rapid | 60+ countries |
 Detailed Word Document
Concise BCG Matrix review of EVERTEC's units with strategic moves for Stars, Cash Cows, Question Marks and Dogs.

 Customizable Excel Spreadsheet
One-page BCG Matrix for EVERTEC—clearly maps units into quadrants, ready to export, share, and present to execs fast.
Core card processing PR: issuing, switching and settlement for incumbent banks remain stable and sticky, underpinning EVERTEC (NYSE EVTC) recurring fee streams. A high share in a mature Puerto Rico market produces reliable transaction fees while upgrades occur periodically, keeping opex lean. Focus is to milk the base and automate operations to lift margins through efficiency gains.
ATM and POS network services show modest transaction growth but deliver high client retention via network density and >99.9% uptime; Evertec processed about 6.5 billion transactions in 2023, illustrating scale. Pricing is predictable with low churn and recurring fee mixes that stabilize cash flow. Capex has been steady after the prior multi‑year build‑out; optimizing routing and preventative maintenance can further boost free cash flow.
B2B bill pay for large enterprises is a defendable cash cow for EVERTEC: entrenched integrations drive recurring volumes and 2024 service contracts preserved gross margins north of 30% while supporting industry-standard SLAs (≈99.99% uptime). The category is mature in core Latin American and Caribbean territories, so top-line growth is calm; focus on light feature add-ons and harvesting cash via scale and contract renewals.
Legacy batch clearing remains a cash cow for EVERTEC; as of 2024 many banks still run nightly batch processes even as real‑time adoption rises, providing steady transaction volumes and predictable fees. It is low‑growth but high‑margin revenue with limited competition in end‑to‑end clearing. Most cost bases are known and largely depreciated, so prioritize stability, avoid gold‑plating, and harvest the yield.
Hosted issuer services are cash cows for EVERTEC: outsourced issuing platforms generate annuity‑like fees with high switching costs that make the client base durable; EVERTEC reported roughly $1.07B revenue in FY2024 and recurring services exceeded 60% of sales. Market growth is low (single‑digit payments CAGR in 2024) yet margins stay healthy at scale; focus on reliability and modest product enhancements to retain share.
Core card processing, ATM/POS, bill pay, legacy clearing and hosted issuer services generate annuity‑like fees, low incremental cost and high retention for EVERTEC. FY2024 revenue ≈ $1.07B; recurring >60%; 2023 processed ~6.5B transactions. Focus: automate ops, preserve SLAs and harvest cash.
| Metric | Value |
|---|---|
| FY2024 revenue | $1.07B |
| Recurring revenue | >60% |
| 2023 transactions | ~6.5B |
| Bill pay gross margin | ~30% |
| Typical SLA uptime | ≈99.99% |
The file you're previewing is the exact EVERTEC BCG Matrix you'll receive after purchase. No watermarks, no demo content—just the fully formatted, ready-to-use report built for clear strategic decisions. It’s crafted by analysts and market-savvy designers, so there are no surprises. Buy once and download the editable, presentation-ready document immediately.
Dogs:
Bespoke on‑prem installs require disproportionate support for small accounts, with legacy maintenance consuming ~60% of IT spend (2024 industry average) and revenue growth under 5% YoY; change orders erode project margins by roughly 10–15%. Cross‑sell potential is minimal. Prune and migrate to standardized cloud stacks—case studies show 25–40% TCO reduction—and reallocate resources to scalable products.
Standalone IVR payments are a Dogs position: usage is declining as mobile apps and web channels dominate, while fixed maintenance and telephony costs persist, eroding margins. Not a growth area and not strategic for EVERTEC’s digital-first roadmap. Recommend consolidating IVR capabilities into an omnichannel platform and retiring redundant standalone services to cut costs and refocus investment.
Single-country niche modules with hard-coded local features fail to scale, tying up roadmap time and engineering spend while capturing minimal share; 80/20 dynamics in 2024 industry analyses show roughly 20 percent of SKUs deliver ~80 percent of value, underscoring weak defensibility for tiny segments and poor ROI for EVERTEC.
Noncore print and mail sits outside EVERTEC's strategic payments growth; industry mailed-bill volumes fell about 7% year-over-year in 2024 per Pitney Bowes, leaving print marginally profitable at best and operationally distracting.
EVERTEC has no sustainable edge versus specialized vendors; outsourcing or divesting this service frees capacity for core payment processing and investment in digital channels.
Dogs: paper checks, bespoke on‑prem, IVR payments and single-country modules face low growth, shrinking volumes (U.S. checks down >50% since 2000; mailed-bill volumes −7% YoY in 2024), high maintenance (~60% IT spend) and compressed margins. Streamline, automate, migrate to cloud, consolidate or divest to redeploy capital.
| Asset | 2024 metric | Recommended action |
|---|---|---|
| Paper checks | Volumes −50% vs 2000 | Sunset/automation |
| On‑prem | IT spend ~60% | Migrate to cloud |
| IVR | Usage declining | Consolidate |
Remittances and merchant settlements are surging globally, but EVERTEC’s footprint in cross‑border payout corridors remains early stage. Margins can be solid—typically 1–3% on payouts—if FX and compliance are tightly managed. Scaling requires bank partners, local licenses and compliance infrastructure. Invest selectively in priority corridors to prove unit economics before broader roll‑out.
SMB software + payments bundles can raise take rates via embedded invoicing, inventory, and pay‑ins; merchant processing fees typically run 1.5–3.5%, so platform-driven add‑ons materially boost revenue. SMEs account for ~90% of businesses and ~50% of employment globally (World Bank, 2024), making this a fast‑growing, high‑value segment. EVERTEC is newer and faces crowded competition; needs deeper product breadth and channel reach or should focus where vertical fit is strongest or exit quickly.
Bank APIs enable account verification, PFM and risk scoring, positioning EVERTEC in a high-growth open banking segment estimated at about $9.5B globally in 2024 with ~23% projected CAGR to 2030. Growth potential is large but commercialization remains fuzzy, and EVERTEC’s current share is low versus global API leaders (Plaid/TrueLayer ~55% share in 2024). Recommend piloting with anchor banks in key markets and monetizing discrete use cases first—account verification and PFM—to build revenue paths and prove unit economics.
Question Marks: Wallets and QR acceptance — consumer adoption is rising in pockets of LatAm (eg PIX in Brazil drove broad instant-pay use) but remains uneven across markets; EVERTEC provides rails and merchant onboarding yet lacks consumer brand pull; scaling requires partnerships with transit systems, government payouts, or major retailers to drive habitual use; recommend targeted pilots in high-traffic micro-markets, then scale or exit based on KPI thresholds.
Merchants demand installments at checkout both online and in‑store; BNPL global GMV topped an estimated $200B in 2024, underscoring fast category growth, but funding and credit risk designs remain complex; EVERTEC’s market share is early as underwriting models and partnerships still form.
Question Marks: high-growth pockets (remittances, SMB bundles, open banking, wallets/QR, BNPL) show large TAM but low EVERTEC share; 2024 benchmarks: BNPL GMV ~$200B, open‑banking ~$9.5B, SME share ~90% of firms. Recommend targeted pilots, bank partnerships, KPI gating (MAU, txn growth, loss rates) and scale-or-exit thresholds.
| Segment | 2024 | Key KPI |
|---|---|---|
| BNPL | $200B GMV | loss rate, funding share |


