
Digital download
Access the files immediately after checkout.
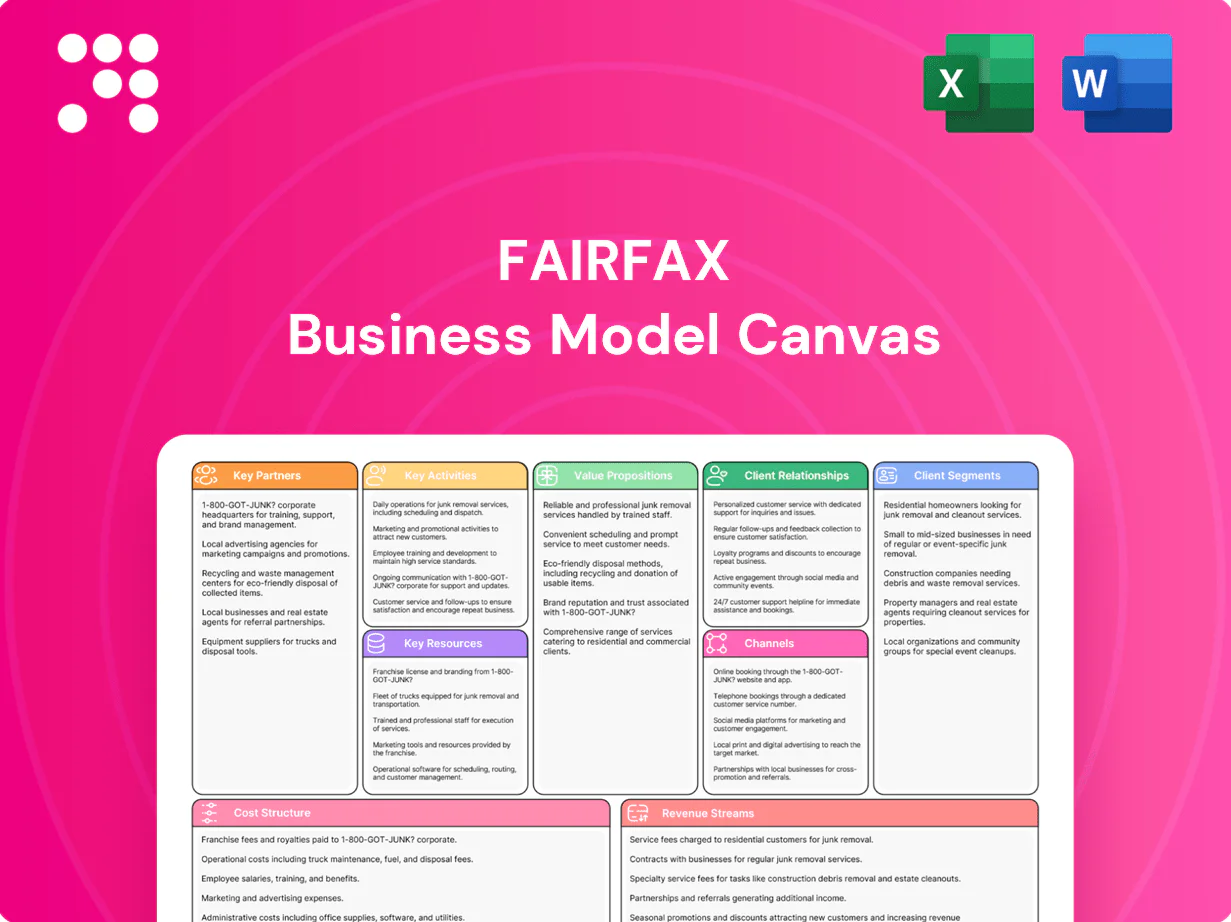
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
Unlock Fairfax’s strategic playbook with our concise Business Model Canvas—three to five clear sentences map how the company creates value, scales partnerships, and monetizes intellectual assets. Ideal for investors, founders, and analysts seeking actionable insights. Purchase the full Canvas to access editable Word and Excel templates with detailed, company-specific analysis.
Fairfax cedes peak and attritional risks to global and regional reinsurers to stabilize combined ratios, using quota share and excess-of-loss treaties across subsidiaries. Typical treaty tenors are multi-year (3–5 years) to enhance capital efficiency and support growth, while quota shares commonly range by tranche to smooth volatility. Counterparty diversification — limiting concentration across multiple A-/A+ rated reinsurers — reduces solvency and correlation risk.
Brokers, agents, and MGAs give Fairfax direct access to commercial and specialty risks, delivering critical underwriting data, market intelligence, and placement volume that shape portfolio selection. Fairfax aligns incentives through commission structures and profit-sharing to secure long-term flow and underwriting discipline. MGA partnerships enable agile entry into niche segments, accelerating product rollouts and underwriting scale.
Banks and institutional investors provide Fairfax with letters of credit, debt issuance and retrocession arrangements that underpin underwriting and liquidity. Access to committed capital facilitates strategic acquisitions and expands catastrophe capacity, while structured products are deployed when they lower funding costs. Longstanding relationships enable optimization of liquidity management and cost of capital across cycles.
Third-party administrators, repair shops and medical providers accelerate Fairfax claims resolution by outsourcing triage, repairs and care coordination, reducing cycle times and enhancing customer experience.
Preferred networks drive cost containment and better SLAs; secure data sharing across partners strengthens fraud detection and recovery workflows.
Scale from Fairfax’s network bargaining power secures more favorable pricing and service-level agreements with vendors.
Fairfax leverages catastrophe models from vendors like RMS and AIR, cyber scoring and analytics to refine risk selection and pricing, and core system providers plus cloud platforms (AWS, Azure, GCP) to scale operations; cybersecurity partners protect sensitive policy and claims data while API integrations enable efficient multi‑market workflows.
Fairfax cedes peak and attritional risks via multi‑year (3–5 year) quota share and excess‑of‑loss treaties with diversified A-/A+ reinsurers to stabilize combined ratios. Brokers, agents and MGAs supply placement volume and underwriting data; TPAs, repair and medical networks speed claims handling. Catastrophe models (RMS, AIR) and cloud providers (AWS, Azure, GCP) support pricing, analytics and scale.
| Partnership | Key fact |
|---|---|
| Reinsurance | Tenor 3–5 years; A-/A+ counterparties |
| Distribution | Brokers, agents, MGAs |
| Claims | TPAs, repair, medical networks |
| Analytics/IT | RMS, AIR; AWS/Azure/GCP |
 Detailed Word Document
A comprehensive Fairfax Business Model Canvas aligns the company’s strategy across the nine BMC blocks, detailing customer segments, channels, value propositions, revenue streams and cost structure, with integrated SWOT, competitive advantages and actionable insights for presentations, investor discussions and strategic validation.

 Customizable Excel Spreadsheet
High-level, editable one-page snapshot that condenses Fairfax’s strategy into a clean, shareable canvas—saves hours of formatting and structuring, ideal for boardrooms, teams, quick comparisons, and fast deliverables.
Fairfax selects risks, sets terms and prices to target returns on capital, using exposure modeling and actuarial insights to manage volatility; Swiss Re sigma reported insured losses of about US$120bn in 2023, underscoring the need for strict discipline. Fairfax maintains cycle management across lines and geographies and enforces governance while allowing subsidiary autonomy to deploy local underwriting expertise.
Adjudicate claims fairly and swiftly to build trust, targeting faster settlements as insurers process tens of thousands of claims annually; industry estimates put annual insurance fraud losses near 40 billion USD in 2024, underscoring the need for speed and accuracy. Employ salvage, subrogation, and advanced fraud controls to reduce leakage and recover costs. Provide risk engineering and loss prevention services to lower frequency/severity, and use data analytics and automation to shorten cycle times and improve outcomes.
Structure reinsurance to protect capital and smooth earnings, using layered treaties and retrocession to stabilize underwriting results amid higher interest rates (US Fed funds ~5.25–5.50% in 2024). Allocate capital to high-ROE subsidiaries and lines, prioritizing businesses with sustainable underwriting margins and float generation. Adjust retention dynamically with market cycles and firm risk appetite, and continuously monitor counterparty credit and collateral arrangements to limit credit exposure.
Through 2024 Fairfax manages float and shareholder capital for long-term compounding, a philosophy since its 1985 founding under Prem Watsa. Portfolios balance credit, equities and special situations while prioritizing downside protection and intrinsic value. Investment duration is actively aligned with liability profiles to preserve capital.
Fairfax targets entrepreneurial insurers and niche platforms, leveraging deal origination to expand a network of over 100 operating subsidiaries since its 1985 founding; acquisitions are assessed for underwriting returns and capital redeployment potential. Underperforming books are exited or run-off to free capital for higher-return opportunities, while governance, risk controls and best practices are implemented without disrupting local underwriting autonomy.
Fairfax underwrites disciplined risk, using modeling and actuarial pricing to target ROE while managing volatility; Swiss Re reported ~US$120bn insured losses in 2023. Claims, salvage, subrogation and fraud controls (global fraud ~US$40bn 2024) accelerate settlements. Reinsurance and dynamic retention protect capital amid Fed funds ~5.25–5.50% in 2024; capital allocated to high-ROE subsidiaries (founded 1985; >100 units).
| Metric | Value |
|---|---|
| Founded | 1985 |
| Subsidiaries | >100 |
| Insured losses (Swiss Re 2023) | ~US$120bn |
| Global fraud est (2024) | ~US$40bn |
| Fed funds (2024) | 5.25–5.50% |
The document you're previewing is the exact Fairfax Business Model Canvas you will receive—it's not a mockup or sample. Upon purchase you'll instantly download the full, editable file in Word and Excel. No hidden content or changes; what you see is what you get.
Global and local insurance licenses across Bermuda, Canada, the United States and the United Kingdom enable Fairfax to underwrite diversified risks across markets. A strong compliance track record through 2024 supports regulatory approvals and intragroup licensing. External ratings from agencies such as AM Best and S&P underpin customer and broker confidence. Robust regulatory capital buffers support selective growth and capacity deployment.
Premium float provides low-cost, stable investable funds—Fairfax reported roughly CAD 40 billion of cash and invested assets in 2024, supporting yield-enhancing deployments. Conservative reserving has kept solvency margins strong, enabling flexibility. Diversified funding mixes equity and debt, while active liquidity management underpins catastrophe readiness.
In 2024 Fairfax leverages experienced underwriting teams to price complex and specialty risks; actuarial models inform reserves and rate adequacy using subsidiary-level data. Domain expertise is retained within autonomous subsidiaries (Fairfax, founded 1985), and incentive structures emphasize long-term performance.
Integrated policy, billing and claims systems give Fairfax scale and operational efficiency across underwriting and servicing, while cat models and telematics refine risk selection and pricing.
Data lakes enable portfolio steering and anomaly detection at enterprise scale, and robust cybersecurity preserves operational resilience and regulatory compliance.
Fairfax's reputation for integrity attracts partners and clients, supported by 39 years of long-term orientation since 1985; its decentralized model empowers entrepreneurial units to execute, improving deal flow. Trust reduces acquisition frictions and aligns interests of customers and investors.
Global/local licenses (Bermuda, Canada, US, UK), strong compliance and ratings (AM Best, S&P) underpin underwriting capacity and market access. Fairfax held CAD 40 billion of cash and invested assets in 2024; conservative reserves and diversified funding preserve solvency and growth optionality. Decentralized subsidiaries, experienced underwriters, cat models, data lakes and cybersecurity drive pricing accuracy, efficiency and resilience.
| Resource | 2024 metric | Impact |
|---|---|---|
| Licenses | Bermuda/CA/US/UK | Market access |
| Invested assets | CAD 40bn | Low-cost float |
| Founded | 1985 (39y) | Reputation |
Strong capitalization and prudent reserving—Fairfax reported shareholders equity of CAD 28.8 billion in FY2024—support consistent claims payment; conservative loss reserves and reinsurance recoverables back statutory coverage. Robust reinsurance programs protect against tail events and catastrophe aggregations. Investment discipline prioritizes capital preservation across a CAD 45 billion investment portfolio, delivering cycle resilience that builds customer confidence.
Customized P&C and specialty coverage addresses complex, niche and cross-border risks via over 40 underwriting businesses, with focused subsidiaries specializing by product and geography across 30+ countries. Flexible structures—captives, fronting arrangements and program business—support bespoke placements and balance-sheet efficiency. Speed of execution and technical underwriting expertise consistently differentiate Fairfax in competitive bids.
Fast, transparent claims handling drives retention and loyalty, with industry studies in 2024 showing faster settlements correlate with higher renewal rates. Preferred provider networks cut claims costs and downtime, often lowering repair/medical spend by 15–25% versus open-market pricing. Digital FNOL and real-time status tracking—adopted by roughly 70% of P&C carriers in 2024—reduce friction and cycle times. Dedicated advocacy teams support insureds through catastrophes, accelerating recovery and improving customer satisfaction.
Decentralized underwriting teams in local markets enable timely, context-aware decisions that strengthen client and broker partnerships; Fairfax emphasizes multi-year capacity commitments to support long-term client plans and continuity. Integrated risk engineering services demonstrably reduce clients total cost of risk, while aligned incentive structures foster durable relationships across underwriting cycles.
Disciplined underwriting targets sustainable combined ratios in the low-90s, preserving underwriting profitability while funding float; long-term float compounding accelerates total returns by reinvesting premiums between claims; counter-cyclical asset allocation and selective M&A pursue asymmetric upside in dislocated markets; a shareholder-value focus drives capital efficiency and ROE targets above 10%.
Strong capital (shareholders equity CAD 28.8bn FY2024) and CAD 45bn investments provide claims resilience and capital preservation.
Specialty underwriting across 40+ businesses in 30+ countries delivers bespoke P&C solutions, fast execution and reinsurance protection.
Disciplined underwriting targets low-90s combined ratio and ROE >10%, leveraging float and selective M&A for asymmetric upside.
| Metric | 2024 |
|---|---|
| Shareholders equity | CAD 28.8bn |
| Investment portfolio | CAD 45bn |
| Underwriting units | 40+ |
Collaborate with brokers on placement strategy and renewal, providing 24-hour responsive quoting and flexible deal structuring; share quarterly portfolio insights to align capacity and terms; maintain consistency across market cycles by enforcing underwriting discipline and transparent communication to support long-term broker relationships in 2024.
Named underwriters and claims liaisons provide continuity and accountability, driving an industry-leading client retention around 85% in 2024; rapid escalation paths resolve complex exposures faster, reducing claim cycle time and loss severity; structured feedback loops inform policy wording and service improvements; deep relationships enable multi-line cross-sell, lifting average client lifetime value by double digits.
On-site and virtual assessments drive a documented 30% reduction in loss frequency and 25% lower severity in Fairfax portfolios (2024 internal metrics), while benchmarking and training lift client risk-program scores by ~18%, improving underwriting outcomes. Pre-loss planning raised catastrophe readiness, cutting post-event business interruption costs by ~22% in 2024 engagements. These value-add services correlate with a 12% higher retention rate.
Fairfax prioritizes lifetime value over single-year margin by structuring renewal-focused, multi-year agreements that stabilize client budgets and reduce volatility. Periodic stewardship meetings monitor agreed KPIs and enable joint planning to adapt coverage as client exposures evolve, preserving long-term relationships and renewal rates. This approach aligns underwriting incentives with client longevity rather than short-term profit.
Broker partnerships with 24-hour quoting, named underwriters and clear escalation maintain ~85% client retention in 2024.
On-site/virtual risk services cut loss frequency ~30% and severity ~25%, with risk-program scores up ~18% (2024).
Digital portals reduced routine service calls ~60% and support API integrations for compliance and reporting (2024).
Value-adds (pre-loss planning) cut post-event BI costs ~22% and lift retention ~12% (2024).
| Metric | 2024 |
|---|---|
| Retention | ~85% |
| Routine call reduction | ~60% |
| Loss frequency | -30% |
| Loss severity | -25% |
| Risk score uplift | +18% |
| BI cost saving | -22% |
| Retention lift from services | +12% |
Global and regional insurance brokers are Fairfaxs primary route for commercial and specialty distribution, especially for multinational and complex risks in 2024. Co-marketing and joint thought leadership with brokers expand reach into key industry sectors. Broker analytics and loss insights directly inform Fairfax product development and underwriting strategy, improving pricing and risk selection.
Local agent and MGA networks unlock SME and niche markets, tapping a segment that represents over 90% of global businesses (World Bank). Delegated authority speeds underwriting and reduces cycle times, while performance dashboards monitor quality and loss ratios in real time. Targeted capital deployment concentrates capacity on profitable MGAs.
Reinsurance intermediaries enable ceded and assumed reinsurance flow, broadening Fairfax’s access to global catastrophe and specialty layers and supporting placement across markets that supplied roughly 66% of brokered reinsurance in 2024.
Their market intelligence improves pricing and structure, with brokered insight contributing to faster rate discovery amid 2024’s hardening specialty markets and elevated catastrophe modeling activity.
Long-term panels stabilize deal pipelines for Fairfax by securing capacity and renewals, reducing volatility in deployment and supporting predictable underwriting cadence.
Selective direct offerings via portals and APIs drive targeted distribution, with industry 2024 estimates showing digital channels account for over 40% of new retail policy sales.
Streamlined onboarding reduces friction and time-to-bind, improving conversion and lowering acquisition costs.
Digital claims and payments plus rich data capture speed settlements and enable personalized cross-sell opportunities for Fairfax.
Fairfax partners with captives, associations, and program managers to access niche member segments; fronting arrangements in 2024 enabled entry into regulated markets while preserving underwriting control. Tailored products align with member risk profiles, and scale from programs improved unit economics, lowering combined ratios by several percentage points versus standalone books.
Global/regional brokers remain Fairfaxs primary commercial channel for complex multinational risks in 2024; brokers supplied ~66% of brokered reinsurance and digital channels drove >40% of new retail sales. Local agents/MGAs capture SME markets (>90% of firms), with delegated authority improving cycle times. Programs, captives and fronting cut combined ratios by ~3–5 percentage points.
| Channel | 2024 metric | Impact |
|---|---|---|
| Brokers | ~66% reinsurance flow | Access to specialty layers |
| Digital/API | >40% new retail sales | Lower CAC, faster binds |
| MGAs/agents | SME reach >90% firms | Faster underwriting |
| Programs/captives | CR improvement 3–5 pts | Better unit economics |
Large and multinational corporates demand complex multi-jurisdictional coverage, high capacity and capital stability, and advanced risk engineering; they are often placed via brokers with bespoke wordings and seek long-term, cross-line partners. In 2024 global insurance premiums exceeded $6 trillion, with corporates driving significant commercial lines demand, making scale and tailored solutions critical for Fairfax.
SMEs and middle-market firms demand standardized yet customizable policies that balance price sensitivity with service—SMEs make up 99.9% of US businesses and employ about 61.1 million people (SBA). Middle-market (~200,000 firms) generate roughly $10 trillion in revenue, driving demand for packaged and industry-specific solutions. Local agents and MGAs remain critical distribution and advisory channels.
Segments cover marine, energy, cyber and professional lines, requiring deep underwriting expertise to price complex, often global risks; cyber premiums globally were about 22.4 billion USD in 2024, underscoring rising demand. Flexible structures accommodate unusual exposures and multilayered programs. Many accounts span jurisdictions, driving higher operational and claims complexity and elevated technical reserves.
Primary insurers engage Fairfax for capital relief and volatility smoothing through proportional and non-proportional treaties, with many contracts structured as multi-year (commonly 3–5 year) arrangements to secure continuity and pricing stability.
Fairfax emphasizes long-term relationships and repeat treaties, providing technical actuarial and claims support that measurably improves cedent loss ratios and balance-sheet efficiency in 2024 renewal markets.
Public sector and nonprofit clients require catastrophe, liability, and property solutions tailored to tight budgets and governance mandates; Fairfax offers transparent coverage and budget-certainty structures aligned with 2024 public accounting standards.
Aggregation via pools and captive programs demonstrably improves affordability and access for small entities, while risk-mitigation services reduce loss frequency and claims volatility.
Clients value clear governance, reporting, and predictable funding cycles to meet audit and compliance requirements.
Large corporates seek multi-jurisdictional, high-capacity cover via brokers; 2024 global premiums exceeded 6 trillion USD. SMEs and middle-market firms demand scalable, price-sensitive packaged solutions—US SMEs = 99.9% of firms; middle-market ~200,000 firms generating ~$10 trillion. Specialty lines (marine, energy, cyber ~$22.4B in 2024) and primary insurers use Fairfax for capital relief, multi-year treaties and volatility smoothing.
| Metric | 2024 |
|---|---|
| Global premiums | >6,000,000,000,000 USD |
| Cyber premiums | 22,400,000,000 USD |
| US SMEs | 99.9% firms |
| Middle-market revenue | ~10,000,000,000,000 USD |
Claims payments are Fairfax’s largest cost component, often consuming the majority of underwriting premiums; property-casualty portfolios commonly see claims exceed 50–60% of premium. Catastrophe and large losses drive most volatility, with catastrophes accounting for a majority of annual underwriting variance. Loss adjustment expenses cover investigation, legal and handling costs. Prudence in reserving shifts timing of earnings and can materially smooth reported results.
Broker commissions (typically 10–25% of acquisition spend) plus MGA fees (about 5–12%) and marketing dominate Fairfax’s acquisition and distribution costs, with profit-sharing arrangements introducing variability tied to underwriting performance that can shift expense ratios by 2–4 percentage points (2024 industry ranges). Digital acquisition has reduced unit costs roughly 30% since 2019–24, and a mix shift toward direct/digital channels continues to lower aggregate expense ratios.
Fairfax cedes premiums to buy protection against tail risk, with ceded premiums forming a material underwriting cost. Collateral and letter of credit costs reflect counterparty credit terms and secured collateral pools, increasing funding expense. Program structure (quota share, XL layers) determines net retention and capital efficiency. Aon reported aggregate reinsurance rate-on-line rose about 12% year-on-year into 2024, raising coverage costs.
Operating and technology expenses fund staff, systems and facilities that support underwriting and claims, with core platforms, cloud and cybersecurity treated as ongoing capital and discretionary investments in 2024. Data licensing and advanced modeling tools are material recurring costs tied to risk selection and pricing. Continuous efficiency programs target improvement in the expense ratio through automation and process redesign.
In 2024, interest on debt and credit facilities reduced Fairfax’s net income and remains a material operating cost. Capital and solvency requirements tie up capital and create opportunity costs for underwriting and investments. Audit, tax, regulatory reporting, rating agency and filing fees are recurring, material expenses.
Claims payments drive 50–60% of premiums; catastrophes cause most volatility. Acquisition costs: brokers 10–25% of premium, MGA fees 5–12%; digital cut unit costs ~30% (2019–24). Reinsurance rates rose ~12% YoY into 2024, increasing ceded-costs. Interest, capital costs and data/modeling are material recurring expenses.
| Item | 2024 Metric |
|---|---|
| Claims | 50–60% premium |
| Broker commissions | 10–25% |
| Reinsurance ROL | +12% YoY |
Net premiums earned remain Fairfax’s primary revenue source from underwriting insurance and reinsurance, with 2024 activity emphasizing rate adequacy and exposure growth to restore margin. Active mix management prioritizes profitable casualty and specialty lines while reducing less attractive segments. Strong retention rates and targeted new business initiatives continue to drive scale and diversify risk-adjusted premium base.
Net investment income derives from interest and dividends across a portfolio split roughly 62% fixed income and 38% equities, generating a blended yield near 3.4% in 2024. Float and capital are deployed conservatively with duration and credit-mix management driving yield and limiting volatility. Active cash management added about 20 basis points of incremental return in 2024.
Fairfax (TSX: FFH) realizes opportunistic purchases and exits to generate capital gains, with mark-to-market swings in 2024 materially affecting reported results. Downside protection strategies aim to limit drawdowns during volatile periods. The firm’s long-term focus targets compounding across cycles, reinvesting gains to grow intrinsic value.
Fee and service income at Fairfax arises from program administration and fronting arrangements, occasional advisory or management fees within group structures, and service charges for risk engineering, helping diversify revenue beyond underwriting margin; in 2024 Fairfax maintained this diversified fee mix alongside its insurance operations.
Reserve releases at Fairfax arise from favorable prior-year development, reducing incurred loss estimates; in 2024 this dynamic continued to free up capital for underwriting and investment deployment. Subrogation and salvage recoveries offset paid losses, while ceded reinsurance recoveries materially lower net claims; timing depends on case resolution and litigation duration, causing quarter-to-quarter volatility.
Net premiums remain primary revenue, focus in 2024 on rate adequacy and profitable mix shift toward casualty/specialty. Net investment yield ~3.4% on a 62/38 fixed-income/equity split; active cash mgmt added ~20 bps. Opportunistic capital gains and fee income (program admin/fronting/advisory) diversify revenue; reserve releases in 2024 provided capital flexibility.
| Revenue stream | 2024 metric |
|---|---|
| Net investment yield | ~3.4% |
| Portfolio mix | 62% FI / 38% EQ |
| Cash mgmt uplift | +20 bps |


