
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Understanding the competitive landscape is crucial for EfTD's success, and Porter's Five Forces provides a powerful framework. This analysis illuminates the key pressures shaping EfTD's market, from the bargaining power of buyers to the intensity of rivalry.
The complete report reveals the real forces shaping EfTD’s industry—from supplier influence to threat of new entrants. Gain actionable insights to drive smarter decision-making.
A concentrated supplier base significantly amplifies the bargaining power of suppliers. In the global tire manufacturing sector, for instance, a handful of giants like Michelin, Pirelli, Bridgestone, Continental, and Goodyear dominate. This means distributors such as Fintyre often face a limited number of viable sourcing options for popular tire brands.
This market structure grants these large tire manufacturers considerable leverage. Their substantial market share and extensive brand recognition reduce the alternatives available to distributors. Consequently, Fintyre, like many in its position, finds its ability to negotiate favorable terms constrained by the limited choices for acquiring a diverse range of tires.
Major tire brands like Michelin, Goodyear, and Bridgestone enjoy significant consumer loyalty and brand recognition. This strong brand equity allows them to maintain premium pricing and exert considerable influence over their distribution partners. For a distributor like Fintyre, this means a reliance on stocking these sought-after brands to satisfy market demand.
Fintyre's dependence on these established brands inherently limits its bargaining power. The need to offer popular, high-demand tires means Fintyre must accept the supply terms and pricing dictated by these powerful manufacturers. This dynamic directly impacts Fintyre's ability to negotiate favorable terms or drive down costs, as the brand's inherent value is a significant factor in the purchasing decision.
For Fintyre, switching tire suppliers presents significant hurdles. The process involves not just finding a new manufacturer but also overhauling logistical networks, integrating entirely new product lines, and potentially re-educating staff on different tire specifications and performance characteristics. These operational complexities and the potential for supply chain disruptions inherently bolster the bargaining power of Fintyre's current tire manufacturers.
Tire manufacturers are increasingly differentiating their products through significant investments in research and development. This focus on specialized and technologically advanced tires, including those designed for electric vehicles, smart tires equipped with sensors, and sustainable, eco-friendly compounds, directly impacts Fintyre's ability to switch suppliers. For instance, in 2024, the global automotive tire market saw substantial R&D expenditure, with major players allocating billions to innovation, particularly in areas like EV-specific tires which require unique performance characteristics.
This technological advancement creates a barrier to easy substitution. Fintyre cannot simply swap one tire supplier for another without potentially compromising on the specific performance, durability, or technological features demanded by its automotive clients. The complexity and proprietary nature of these advanced tire technologies mean that a direct, cost-effective, and quality-equivalent replacement is often not readily available, thereby strengthening the bargaining power of these specialized tire suppliers.
The potential for suppliers to integrate forward into the buyer's industry can significantly influence their bargaining power. For instance, major tire manufacturers, while not universally pursuing this strategy, could bolster their leverage by expanding their direct distribution networks or even acquiring existing smaller distributors. This possibility, even if perceived as a distant threat, compels companies like Fintyre to cultivate strong supplier relationships, aiming to preempt any moves that could introduce direct competition.
This forward integration threat is particularly potent when suppliers possess substantial resources and market presence. In 2024, the global automotive aftermarket, which includes tire distribution, was valued at over $400 billion, indicating the scale of investment required for successful forward integration by tire manufacturers. Such a move would directly challenge Fintyre's business model, giving suppliers an edge in price negotiations and contract terms.
Suppliers wield considerable power when they are few in number and the buyer has limited alternatives, as seen with major tire manufacturers like Michelin and Bridgestone. This concentration means distributors such as Fintyre have fewer options, forcing them to accept supplier-dictated terms. The brands' strong customer loyalty further limits a distributor's negotiation leverage.
The bargaining power of suppliers is amplified when their products are unique or highly differentiated, making them difficult to substitute. Tire manufacturers invest heavily in R&D, particularly for specialized tires like those for electric vehicles, which requires billions in global investment annually. This technological advancement creates barriers, as distributors like Fintyre need these specific products, thus increasing supplier influence.
Suppliers can also leverage their power by threatening to integrate forward into the buyer's industry. For instance, tire manufacturers could expand their direct distribution or acquire existing distributors. Given the global automotive aftermarket's value exceeding $400 billion in 2024, this forward integration is a credible threat that compels distributors to maintain favorable supplier relationships.
| Factor | Impact on Supplier Bargaining Power | Example (Tire Industry) | 2024 Data/Context |
|---|---|---|---|
| Supplier Concentration | High | Few dominant tire manufacturers (Michelin, Bridgestone) | Limited alternative suppliers for distributors. |
| Product Differentiation | High | R&D in EV tires, smart tires | Over $5 billion invested globally in tire R&D for advanced solutions. |
| Switching Costs | High | Logistical changes, new product integration | Complexities deter distributors from switching brands. |
| Forward Integration Threat | Moderate to High | Potential for manufacturers to distribute directly | Automotive aftermarket valued over $400 billion, indicating resources for integration. |
 Detailed Word Document
This analysis unpacks the competitive forces impacting EfTD, revealing the intensity of rivalry, buyer and supplier power, and the threat of new entrants and substitutes.

 Customizable Excel Spreadsheet
Quickly identify and address competitive threats by visually mapping the intensity of each Porter's Five Forces on an intuitive radar chart.
Fintyre's customer base is highly fragmented, comprising a multitude of tire retailers and workshops across Italy. This means that no single customer, or even a small group of customers, typically holds significant leverage over Fintyre due to their individual purchasing volume.
With thousands of independent businesses relying on Fintyre for their tire supply, the bargaining power of any one customer is inherently limited. This dispersion of demand means that Fintyre doesn't face the pressure of a few large buyers dictating terms, which is a common challenge in industries with concentrated customer bases.
Customers, specifically tire retailers and workshops, face very low switching costs. They can easily source tires from a variety of distributors or even directly from smaller manufacturers, meaning their loyalty to a single supplier like Fintyre isn't deeply entrenched.
This ease of switching directly empowers these customers. It allows them to readily compare prices and terms across different suppliers, giving them significant leverage to negotiate for more competitive pricing or more favorable business arrangements. For instance, in 2024, the global tire market saw numerous new entrants and expanded distribution networks, further intensifying this competitive landscape for suppliers.
The price sensitivity of end-consumers significantly impacts the tire industry. For instance, in 2024, average car maintenance costs, including tire replacement, remained a key consideration for households, with many actively seeking deals and discounts.
This direct consumer price sensitivity creates a ripple effect, putting pressure on retailers and workshops to offer competitive pricing. Consequently, these businesses are compelled to negotiate harder with their suppliers, including distributors like Fintyre, for more favorable wholesale prices.
Fintyre's customers, therefore, leverage this downstream price pressure to their advantage, effectively increasing their bargaining power. They can demand lower purchasing costs, knowing that their own profitability hinges on their ability to pass on competitive prices to the ultimate car owner.
The Italian tire distribution market is characterized by a healthy number of players, offering retailers and workshops a variety of choices beyond Fintyre. This competitive landscape directly empowers customers.
With multiple distributors available, customers can readily compare pricing, product availability, and service terms. This ability to shop around significantly strengthens their bargaining position, as they can leverage alternative offers to secure more favorable deals.
For instance, in 2024, the average profit margin for tire distributors in Italy hovered around 5-8%, a figure that can be pressured downwards when customers have numerous viable alternatives.
The proliferation of e-commerce platforms has drastically increased information transparency within the tire retail sector. Consumers can now effortlessly compare prices, product specifications, and customer reviews across numerous online vendors. This accessibility directly impacts the bargaining power of customers, enabling them to identify the most competitive offers available in the market.
For a company like Fintyre, this means customers are better equipped to negotiate or seek out alternative suppliers. For instance, in 2024, online tire sales continued to grow, with platforms offering detailed comparisons that highlighted price differences of up to 15% for identical tire models from different retailers. This heightened awareness forces retailers to maintain competitive pricing strategies to retain their customer base.
The bargaining power of customers in the tire industry is substantial due to several factors. The fragmented customer base means no single buyer holds significant sway, but the ease with which retailers and workshops can switch suppliers empowers them collectively. This is amplified by end-consumer price sensitivity, forcing intermediaries to seek lower wholesale prices.
The competitive distribution landscape in Italy, with numerous distributors beyond Fintyre, allows customers to easily compare prices and service terms, strengthening their negotiation leverage. For instance, in 2024, distributors in Italy typically saw profit margins between 5% and 8%, a figure susceptible to customer pressure from alternative suppliers.
The rise of e-commerce further bolsters customer power by increasing price transparency. In 2024, online platforms showed price differences of up to 15% for identical tires, enabling customers to negotiate better deals or switch to more cost-effective options, thereby squeezing retailer margins.
| Factor | Impact on Customer Bargaining Power | 2024 Data/Trend |
|---|---|---|
| Customer Concentration | Low concentration limits individual customer power. | Fintyre's customer base is highly fragmented. |
| Switching Costs | Low switching costs increase customer leverage. | Retailers can easily switch suppliers, facing minimal disruption. |
| Price Sensitivity | Downstream price sensitivity pressures suppliers for lower wholesale costs. | End-consumer focus on deals impacts retailer pricing strategies. |
| Availability of Substitutes | Numerous alternative distributors empower customers to negotiate better terms. | The Italian market offers multiple tire distribution choices. |
| Information Transparency | E-commerce increases price visibility, enabling better negotiation. | Online platforms in 2024 highlighted price differences up to 15% for identical tires. |
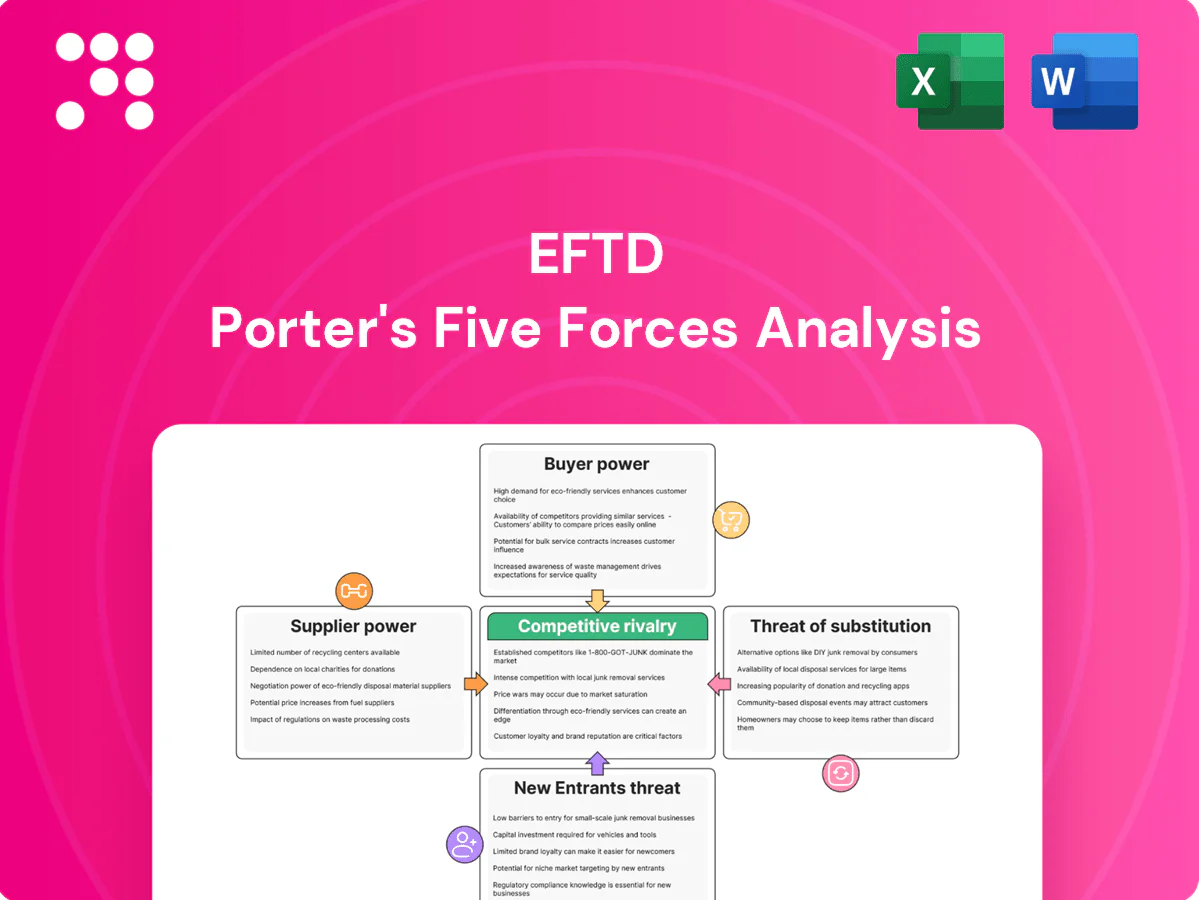
This preview showcases the complete EfTD Porter's Five Forces Analysis, offering a thorough examination of competitive forces within the industry. The document you see here is precisely the same professionally formatted and ready-to-use analysis you will receive immediately after purchase, ensuring no surprises or placeholders.
The Italian tire distribution market is characterized by a significant number of competitors, encompassing both large national players and numerous regional and specialized distributors. This diversity means Fintyre faces competition not only from established, well-known entities but also from smaller, agile firms that may cater to specific market niches or geographical areas.
In 2024, the Italian automotive aftermarket, which includes tire distribution, saw continued activity from major European manufacturers and their established distribution networks. For instance, companies like Bridgestone Europe and Michelin Italy maintain strong presences, often operating through their own extensive dealer networks alongside independent distributors.
Fintyre's competitive set includes these large manufacturers' direct channels and other significant independent distributors such as Autocenter and centers affiliated with large retail groups. The presence of these varied players, from global brands to local businesses, intensifies the rivalry for market share.
The Italian tire market is anticipated to experience growth, with the aftermarket segment expected to be a key contributor. This moderate expansion can unfortunately fuel more intense competition among existing players as they vie for increased market share.
In 2024, the Italian automotive aftermarket, which includes tires, showed resilience, with tire replacement sales accounting for a substantial portion of the sector's revenue. This dynamic means companies might resort to aggressive pricing or promotional strategies to capture a larger slice of this expanding, yet competitive, pie.
Fintyre's strategy of offering a broad range of tire brands and sizes addresses diverse customer needs, but the core product itself is largely undifferentiated. This means that while variety exists, the fundamental tire remains a commodity. Consequently, competition often shifts to non-product attributes.
In 2024, the automotive aftermarket, including tire sales, saw continued price sensitivity. For instance, a significant portion of consumers surveyed indicated that price was the primary driver in their tire purchase decisions, often outweighing brand loyalty or specific product features. This highlights how the standardized nature of tires intensifies rivalry based on cost and accessibility.
The tire distribution market is highly competitive, with many players vying for market share. This intense rivalry often leads to aggressive pricing strategies and frequent promotional activities as companies try to win over tire retailers and workshops. For instance, during 2024, several major tire distributors reported increased spending on marketing and promotional discounts to counter competitive pressures.
This environment can significantly impact profitability. When competitors offer lower prices, extended payment terms, or bundled deals, it forces others to follow suit to remain competitive. This dynamic can compress profit margins for all involved, including companies like Fintyre, as the cost of acquiring and retaining customers rises due to these price-based strategies.
High capital investments in warehousing, logistics infrastructure, and maintaining substantial inventory levels can create significant exit barriers for distributors. These sunk costs make it economically challenging for companies to simply walk away from the market, even when facing persistent losses.
This situation often leads to a scenario where struggling competitors remain active longer than they otherwise might, intensifying price competition. For instance, in the automotive parts distribution sector, a significant portion of a company's assets are tied up in physical inventory and specialized warehousing, making it difficult to divest efficiently.
Competitive rivalry in the Italian tire distribution market is fierce due to a fragmented landscape with numerous players, from large manufacturers' direct channels to independent distributors. This intense competition often translates into aggressive pricing, frequent promotions, and a focus on non-product attributes like payment terms to attract business.
In 2024, the Italian automotive aftermarket, including tire sales, saw continued price sensitivity among consumers, with many prioritizing cost in their purchasing decisions. This dynamic fuels price wars among distributors, impacting overall profitability. For example, major distributors reported increased marketing spend in 2024 to counter competitive pressures.
High capital requirements for warehousing and inventory create significant exit barriers, meaning less profitable firms may remain in the market longer, further intensifying competition and potentially compressing profit margins for all participants.
| Competitive Tactic | Prevalence in 2024 | Impact on Margins |
| Aggressive Pricing | High | Negative |
| Promotional Offers | High | Negative |
| Flexible Payment Terms | Moderate | Neutral to Negative |
| Inventory Management Costs | High | Negative |
For commercial vehicle tires, retreading and repair services present a significant threat. These options offer substantial cost savings compared to new tires, directly impacting Fintyre's potential sales volume in segments like trucks and buses. For instance, the global tire retreading market was valued at approximately USD 12.5 billion in 2023 and is projected to grow, indicating a strong demand for these alternatives.
Advances in tire technology, like the introduction of new composite materials and improved tread designs, are significantly extending tire lifespan. For instance, by mid-2024, some premium tire manufacturers were reporting lifespan increases of up to 20% compared to models available just a few years prior. This means consumers may delay tire replacements, directly impacting sales volumes for companies like Fintyre.
The burgeoning trend of Mobility-as-a-Service (MaaS) presents a significant threat of substitution for traditional tire sales. As platforms like Uber, Lyft, and various car-sharing services gain traction, consumers may opt for these convenient, on-demand transportation solutions over personal vehicle ownership. This shift directly impacts the demand for replacement tires, as fewer privately owned vehicles on the road mean fewer tire purchases through conventional retail channels.
In 2024, the global MaaS market is projected to continue its robust growth, with ride-hailing services alone facilitating billions of rides annually. For instance, companies like Uber reported a substantial increase in active drivers and riders throughout 2023 and into early 2024, indicating a sustained preference for these services. This growing reliance on shared mobility reduces the necessity for individual car maintenance, including tire replacement, posing a long-term, indirect substitute for the automotive tire industry.
The rise of e-commerce direct-to-consumer (DTC) models presents a significant threat of substitutes for traditional wholesale distributors like Fintyre. Online platforms, whether operated by tire manufacturers themselves or specialized e-retailers, are increasingly enabling end-consumers and smaller workshops to purchase tires directly, bypassing intermediaries.
This shift bypasses traditional distribution networks, offering an alternative purchasing route. For instance, in 2024, online tire sales continued their upward trajectory, with platforms like Tire Rack and Discount Tire experiencing robust growth, indicating a clear preference for direct purchasing among a segment of the market. This trend directly challenges the necessity of wholesale models that rely on stocking and distributing to numerous smaller entities.
The threat of substitutes for traditional tires is evolving with advancements in automotive technology. While electric vehicles (EVs) currently necessitate specialized, often more durable tires due to their weight and instant torque, innovations like regenerative braking systems are being integrated into a wider range of vehicles. This technology can reduce the physical wear on brake pads and, by extension, potentially influence tire wear patterns by altering the forces applied during deceleration.
Furthermore, the ongoing drive for lighter vehicle designs across both EV and internal combustion engine (ICE) segments could also impact tire longevity. Lighter vehicles generally exert less force on their tires, which could lead to extended tire life. For instance, by 2024, many manufacturers are targeting significant weight reductions in their new models, with some aiming for 10-15% less weight compared to previous generations. This shift could alter aftermarket demand for replacement tires, a critical revenue stream for tire manufacturers.
The long-term implications of these technological shifts present a notable substitute threat. If vehicle technologies consistently reduce tire wear rates, the frequency of tire replacements could decrease. This would directly impact the volume of sales in the tire aftermarket, which represents a substantial portion of the global tire market. For example, the global tire market was valued at approximately $270 billion in 2023, with aftermarket sales comprising a significant share.
The threat of substitutes for traditional tires is multifaceted, encompassing cost-effective alternatives like retreading and repair services, which offer significant savings. Additionally, advancements in tire technology are extending lifespan, meaning consumers may delay replacements. The rise of Mobility-as-a-Service (MaaS) and direct-to-consumer (DTC) online sales models also present alternative purchasing and usage patterns that bypass traditional channels.
Technological shifts in vehicles, such as regenerative braking and lighter designs, could further impact tire wear rates and, consequently, aftermarket demand. For instance, the global tire retreading market was valued at approximately USD 12.5 billion in 2023, highlighting the appeal of these cost-saving alternatives. Similarly, online tire sales continued their upward trajectory in 2024, with platforms like Tire Rack experiencing robust growth.
| Substitute Category | Key Characteristics | Market Data/Trends (2023-2024) |
|---|---|---|
| Retreading & Repair | Cost savings, environmental benefits | Global retreading market ~USD 12.5 billion (2023); growing demand |
| Extended Tire Lifespan | New materials, improved designs | Up to 20% lifespan increase in premium tires (mid-2024 reports) |
| Mobility-as-a-Service (MaaS) | Shared transportation, reduced personal ownership | Billions of rides facilitated annually by ride-hailing; sustained user growth |
| Direct-to-Consumer (DTC) Online Sales | Bypasses intermediaries, convenience, price transparency | Robust growth for online tire retailers; increasing manufacturer DTC investment |
| Vehicle Technology | Regenerative braking, lighter designs | Targeted 10-15% weight reduction in new vehicle models (2024) |
Establishing a tire distribution business, akin to Fintyre's operations, demands considerable capital. This includes setting up warehousing, stocking a wide array of tire brands and sizes, and maintaining a dedicated logistics fleet. These significant upfront investments create a substantial hurdle for potential new competitors entering the market.
Established players in the tire distribution market, such as Fintyre, already leverage significant economies of scale. This means they can purchase tires in bulk, store them efficiently, and transport them at a lower per-unit cost than a newcomer could. For instance, in 2024, major tire distributors reported operating margins that benefited from these scale advantages, allowing them to absorb logistical costs more effectively.
A new entrant would face considerable challenges in matching these cost efficiencies from the outset. Without the established volume of business, they would likely pay higher prices for inventory and incur greater per-mile transportation costs, making it difficult to compete on price with incumbents like Fintyre. This cost disadvantage acts as a substantial barrier to entry.
Fintyre's deeply entrenched distribution network, cultivated through decades of strong relationships with leading tire manufacturers and an extensive web of retailers and workshops throughout Italy, presents a formidable barrier. New entrants would struggle immensely to replicate this established market access and supplier loyalty.
In established markets, a company's brand reputation and the loyalty it cultivates among customers represent a significant barrier to new entrants. For instance, in the tire distribution sector, where Fintyre operates as a wholesale distributor, a long-standing reputation for dependable service and product quality is paramount. New competitors entering this space would face the considerable challenge of replicating this trust, a process that typically demands substantial time and financial investment.
Building brand loyalty isn't just about marketing; it's about consistent delivery and customer relationships. For example, in 2023, customer retention rates in the automotive aftermarket sector, which includes tire distribution, often exceeded 80% for companies with strong brand equity. This high retention rate means new entrants must offer a compelling value proposition to lure customers away from trusted suppliers like Fintyre, a difficult feat in a mature market.
The automotive aftermarket and tire industry are heavily regulated, with stringent standards for product safety, emissions, and environmental impact. For instance, in the US, the Environmental Protection Agency (EPA) sets standards for tire fuel efficiency and noise emissions, impacting product design and manufacturing processes. Obtaining certifications like ECE R117 for tire noise and rolling resistance in Europe requires significant investment in testing and compliance, creating a substantial barrier for new entrants looking to compete on a global scale.
Navigating these complex and often evolving regulatory landscapes, alongside obtaining necessary certifications, can be a time-consuming and costly endeavor for new companies. This process demands specialized expertise and resources, which can be prohibitive for smaller or less established players. For example, the REACH (Registration, Evaluation, Authorisation and Restriction of Chemicals) regulation in the EU impacts the materials used in tire production, requiring extensive data submission and risk assessments.
The threat of new entrants in the tire distribution market is significantly mitigated by high capital requirements for warehousing, inventory, and logistics. Furthermore, established players benefit from substantial economies of scale, leading to lower per-unit costs and higher operating margins, as seen in 2024 industry reports. Newcomers struggle to match these cost efficiencies, facing higher inventory prices and greater transportation expenses, making price competition difficult against incumbents like Fintyre.
| Barrier Type | Description | Example Impact |
|---|---|---|
| Capital Requirements | Significant upfront investment for infrastructure and stock. | New entrants may require millions in capital to establish basic operations. |
| Economies of Scale | Lower per-unit costs due to high-volume purchasing and logistics. | In 2024, major distributors reported cost advantages contributing to stronger margins compared to smaller players. |
| Distribution Network | Established relationships with manufacturers and retailers. | Replicating Fintyre's extensive network takes years and substantial effort. |
| Brand Loyalty & Reputation | Customer trust built over time through reliable service. | High customer retention rates (often >80% in aftermarket) make customer acquisition costly for new entrants. |
| Regulatory Hurdles | Compliance with safety, environmental, and performance standards. | Certification costs (e.g., ECE R117) can be hundreds of thousands of dollars, delaying market entry. |


