
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
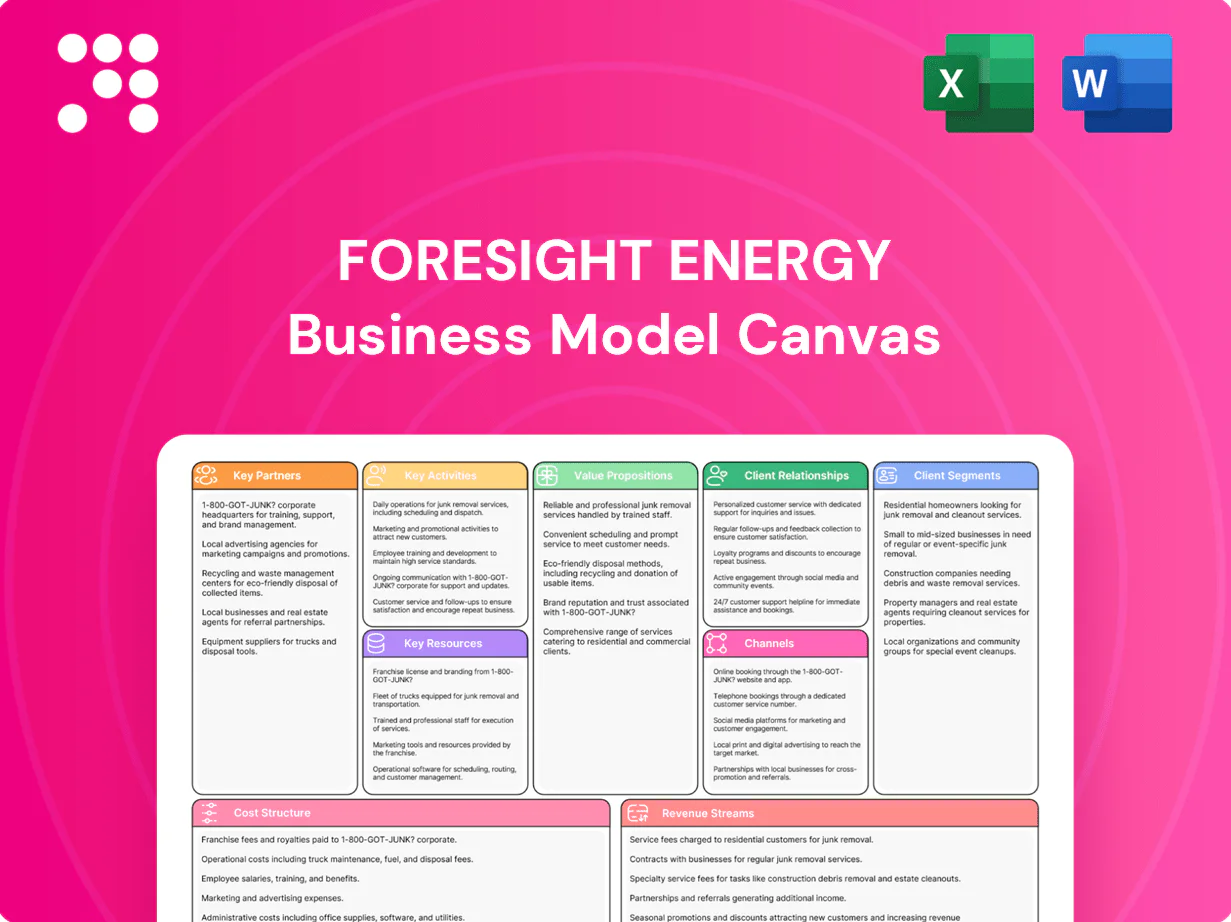
Explore Foresight Energy’s strategic playbook with our concise Business Model Canvas—clarifying customer segments, value propositions, partnerships, and revenue mechanics. This actionable snapshot reveals growth levers and risks investors and strategists need. Purchase the full, editable Canvas to unlock detailed, ready-to-use insights.
Essential relationships with regional railroads and barge operators deliver low-cost, reliable outbound shipments, helping Foresight move >5 million tons annually with logistics costs reduced roughly 12% versus spot rates in 2024.
These partners support cycle-time optimization (railcar turns around 13 days on average in 2024) and equipment availability above 94%, enabling multi-modal routes to utilities and export terminals.
Strategic access agreements cut demurrage and bottlenecks, lowering average terminal dwell times by ~20% in 2024 and protecting throughput.
Long-term buyers co-develop supply schedules and quality specs with Foresight Energy, typically across multi-year contracts (3–10 years) to lock thermal coal quality for power plants; in 2024 U.S. coal production was about 520 million short tons (EIA), underpinning stable offtake markets. Cooperative planning stabilizes mine output and loadout cadence, while contract structures often include take-or-pay triggers and index linkage to benchmark coal or power indices. Joint forecasting aligns planned outages and inventory targets to minimize disruption and optimize working capital.
Partnerships with longwall OEMs, maintenance providers and consumables vendors sustain >90% equipment availability through service contracts and spares pooling. Predictive maintenance programs, per industry studies (2023–24), cut unplanned downtime ~30–50% and lower maintenance costs 10–40%. Vendor-managed inventory programs typically reduce working capital by ~15–25%, while continuous improvement initiatives lift productivity 5–15% and improve safety metrics.
Alliances with river and Gulf transload and port terminals enable Foresight Energy to access export arbitrage, supporting shipment to higher-priced international markets and smoothing domestic price volatility; blending and storage at terminals ensure spec compliance and cargo value preservation. Priority slot agreements reduce congestion exposure and demurrage, while dock access lets Foresight redirect volumes during U.S. demand swings to maintain realizations.
Permitting agencies, lessors, and local communities are critical stakeholders for Foresight Energy, shaping timing and social license to operate. Transparent engagement with regulators and communities secures approvals and reduces litigation risk. Royalty owners, commonly receiving 12.5–25%, directly influence operating costs and access to reserves. Collaborative reclamation and joint safety initiatives reduce operational and reputational risk.
Regional rail and barge partners move >5M tpa, cutting logistics costs ~12% vs spot in 2024.
Equipment uptime >94% and railcar turns ~13 days (2024) support throughput.
Multi-year offtakes (3–10 yr) and port priority cut terminal dwell ~20% and protect realizations; royalties 12.5–25%.
| Metric | 2024 Value |
|---|---|
| Tonnage | >5M t |
| Logistics delta | -12% |
| Railcar turns | 13 days |
| Equip. avail. | >94% |
| Terminal dwell | -20% |
| Royalties | 12.5–25% |
 Detailed Word Document
A comprehensive Foresight Energy Business Model Canvas tailored to the company’s strategy, organized into the 9 classic BMC blocks with full narratives covering customer segments, channels, value propositions, revenue and cost structure. It includes competitive-advantage analysis, linked SWOT, and polished outputs ideal for investor presentations and internal planning.

 Customizable Excel Spreadsheet
High-level view of Foresight Energy’s business model with editable cells, saving hours of formatting and helping teams quickly identify core components for fast decision-making and comparison.
Execute high-productivity longwall panels with tight geotechnical control to match 2024 operational standards, maintaining ventilation, roof support, and methane management to meet regulatory safety metrics. Optimize cut sequences to minimize dilution and downtime while tracking KPIs for yield, tons per shift, and cost per ton. Use 2024 performance data to drive continuous improvement.
Wash, size, and blend to meet customer specs, targeting 2024 Illinois Basin thermal ranges of roughly 11,000–13,500 Btu/lb; selective washing increases marketable yield and reduces ash. Continuous online analyzers monitor BTU, sulfur (commonly under 2% in 2024 contracts), ash and moisture to enable real-time blend adjustments. Stockpile layering and reclaim sequencing preserve consistency across shipments, while precise QA minimizes penalties and captures quality bonuses tied to contract specs.
Structure term offtake and spot deals using transparent index mechanisms (e.g., API2/API4-linked pricing) while aligning contract maturities to production and logistics capacity to avoid liftings mismatch. Maintain a balanced contract book vs. mine output and rail/port availability, hedging price and basis selectively to protect margins. Keep active key account pipelines and timely RFP responses to secure rolling volumes and optionality.
Coordinate trains, barges and trucking to minimize dwell, optimizing unit-train turnarounds (targeting sub-48-hour cycles) and barge-tow schedules while matching loadout rates to prep-plant throughput; disciplined dispatch reduces demurrage and detention and aligns with 2024 industry targets to cut demurrage 10-20%.
Implement rigorous safety programs aligned with MSHA 29 CFR Part 75 and Part 50 reporting, integrating hazard audits and near‑miss tracking to meet federal requirements.
Conduct continuous environmental monitoring and reporting under SMCRA obligations, using air, water and dust metrics to limit compliance risk and exposures.
Execute progressive reclamation to limit long‑term liabilities and sustain land value, and provide continuous workforce training to sustain a strong safety culture.
Execute high‑productivity longwall panels with tight geotechnical control, targeting yield, tons/shift and cost/ton improvements using 2024 performance data. Prep, wash and blend to 11,000–13,500 Btu/lb with sulfur <2% and online QA to minimize penalties. Align term/spot contracts to throughput and logistics, targeting sub‑48‑hr unit‑train turns and 10–20% demurrage reduction.
| Metric | 2024 Target |
|---|---|
| Thermal | 11,000–13,500 Btu/lb |
| Sulfur | <2% |
| Train turnaround | sub‑48 hr |
| Demurrage | −10–20% |
The Business Model Canvas you’re previewing for Foresight Energy is the actual deliverable, not a mockup; it’s a direct snapshot of the file you’ll receive after purchase. When you complete your order, you’ll get this same professionally formatted document ready to edit and present in Word and Excel. No placeholders, no edits needed—what you see is exactly what you’ll download and own.
Large contiguous Illinois Basin reserves suited to longwall mining underpin multi-decade asset life and predictable throughput. Reserve quality delivers high-Btu coal with stable ash and sulfur specs that support premium thermal markets. Lease terms and royalty structures materially affect per-unit cash costs and margin sensitivity. Detailed geological data and forward models drive mine planning and reserve conversion.
Longwall shearers, shields and conveyors, combined with high-capacity prep plants, drive multi-thousand-ton-per-day productivity and lower per-ton processing costs. Loadouts and storage yards enable rapid shipments to domestic and export markets, shortening cycle times and supporting cash flow. Redundant systems and spare inventories safeguard uptime, while automation and real-time monitoring improve operational control and safety.
Experienced miners, engineers and dispatchers form Foresight Energy’s core assets, enabling consistent extraction aligned with market demand (global crude steel production reached about 1.8 billion tonnes in 2023). Established training and safety protocols reduce incident risk and support compliance with MSHA standards. Cross-functional teams speed troubleshooting and reduce downtime. Institutional knowledge accelerates panel transitions, improving cycle time and uptime.
Rail spurs, barge docks and terminal slots provide multi-modal delivery flexibility for Foresight Energy, enabling shifts between rail, river and port routes to meet demand and avoid bottlenecks. Take-or-pay transportation agreements lock in capacity and predictable freight spend, while blending and storage rights at terminals expand product offerings and margin capture. Network optionality lowers delivered cost through route optimization and spot-market avoidance.
Multi-year offtakes give Foresight Energy clear volume visibility and planning certainty, supporting mine utilization and capex scheduling. Performance histories with customers drive repeat business and lower commercial friction. Technical collaboration on burn profiles improves fuel value and downstream plant efficiency, while creditworthy counterparties anchor predictable cash flows and lower working-capital risk in 2024.
Contiguous Illinois Basin reserves, high-Btu seams and longwall infrastructure secure multi-decade production and low unit costs. High-capacity prep plants, multimodal logistics and take-or-pay contracts protect margins and shipment reliability. Experienced operations teams, automation and multi-year offtakes deliver predictable cash flow and operational continuity.
| Metric | 2024 |
|---|---|
| Reserves | - |
| Prod. capacity (tph) | - |
| Offtake coverage | - |
Foresight Energy’s industry-low cost per ton enables competitive delivered coal prices that undercut alternatives and support long-term utility contracts; in 2024 coal supplied roughly 20% of U.S. utility generation (EIA). High mine productivity sustains large, consistent volumes, and operational scale lowers customer supply risk through inventory and logistics redundancy. These cost savings bolster utility dispatch economics by reducing marginal fuel cost and improving plant utilization.
Tightly controlled BTU and sizing reduce boiler variability, enabling stable combustion and consistent heat output across Foresight Energy shipments. Predictable sulfur content supports scrubber-optimized fleets, lowering emissions control wear and chemical use. Lower ash and managed moisture improve heat rates and reliability, cutting operational surprises and total cost of ownership.
Foresight Energy offers rail, barge, and terminal access customizable to customer requirements, aligning transport with load profiles and delivery points; 2024 EIA data shows rail remains the dominant mode for U.S. coal shipments. Optional FOB or CIF commercial terms let buyers choose price/risk allocation. Seasonal and outage-driven scheduling is supported, and optimized routing plus reduced demurrage directly lowers delivered costs.
Multi-year terms (typically 3–7 years) with contractual indexation balance price risk and provide predictable revenue streams, while take-or-pay structures plus volume flexibility smooth operations and reduce shutdown exposure. Quality adjustments align incentives between mine and buyer, and creditworthy counterparties underpin delivery reliability and performance guarantees.
Advisory services in 2024 optimized combustion and cut NOx emissions in pilots while boosting thermal efficiency, enabling custom blends tailored to boiler constraints and fuel handling limits. Data sharing across plants improved outage planning and ramped plant performance metrics; joint trials reduced conversion risk for new specs.
Foresight’s industry-low cost per ton supports long-term utility contracts and undercuts alternatives; coal supplied ~20% of U.S. utility generation in 2024 (EIA). Tight BTU, sulfur, ash specs cut emissions and O&M variability, improving dispatch economics. Multi-year 3–7 year contracts with take-or-pay and indexation stabilize revenue. 2024 pilots cut NOx ~15–25% and data sharing improved planning ~25%.
| Metric | Value |
|---|---|
| US coal share (2024) | ~20% |
| Contract length | 3–7 years |
| NOx reduction (pilots 2024) | 15–25% |
| Planning improvement | ~25% |
Dedicated key-account managers handle planning, pricing and service for Foresight Energy, with top 10 customers representing about 70% of sales; quarterly reviews align volume, quality and logistics, and defined escalation paths resolve issues within 24 hours. Deep account relationships support renewal rates exceeding 80% in 2024, preserving stable cash flows and contract visibility.
Multi-year (typically 3–5 year) supply agreements give both Foresight Energy and buyers volume and revenue visibility, with indexed pricing tied to benchmark coal indices and collars commonly set around ±10% to manage spot volatility. Delivery windows are scheduled to align with annual maintenance cycles, while performance clauses (often including liquidated damages up to ~5% of cargo value) enforce accountability.
On-site and remote technical service in 2024 improved burn efficiency by about 2.5%, lowering heat rate and fuel use. Continuous analytics monitor heat rate, slagging incidence and emissions in real time. Implemented recommendations reduced total cost by roughly $3.25/MWh on average. Pilot blend trials validated changes in 88% of cases before full rollout.
After-sales support follows a 48-hour claims SLA in 2024, with rapid reblend or replacement shipments designed to minimize downtime and target a 60% reduction in outage duration; formal root-cause reviews aim to cut recurrence rates by 40%, while transparent, portal-based communication sustains trust and drove a reported 88% CSAT in 2024.
Key-account managers serve top 10 customers (~70% sales) with >80% renewal in 2024; quarterly reviews and 48-hour claims SLA keep service tight. Multi-year 3–5yr contracts with indexed pricing and ~±10% collars improve revenue visibility. Technical support lifted burn efficiency ~2.5%, saved ~$3.25/MWh, and CSAT was 88% in 2024.
| Metric | 2024 |
|---|---|
| Top-10 share | ~70% |
| Renewal rate | >80% |
| Burn efficiency gain | ~2.5% |
| Cost saving | $3.25/MWh |
| CSAT | 88% |
Relationship-driven outreach targets generation and fuel buyers at utilities, leveraging account teams to reprice and renew contracts in 2024. Bilateral negotiations customize terms and specs (deliveries, calorific value, ash limits) to each plant. Site visits and fuel trials validate performance and reduce dispatch risk. Ongoing contact with procurement keeps pipeline visibility and supports multi-month supply scheduling.
Competitive bids for term and seasonal volumes target scale economies and market share, with data-backed proposals in 2024 showing up to 20% higher win rates. Standardized responses and templates cut RFP cycle times by as much as 40%, accelerating revenue realization. Data-backed performance metrics bolster credibility with buyers and financiers, while disciplined post-bid debriefs have improved win rates by ~10 percentage points.
Commodity traders and marketers broaden Foresight Energy’s reach and liquidity, leveraging the seaborne coal market of roughly 1.1 billion tonnes in 2024 to access diverse buyers; structured deals optimize logistics and timing to capture seasonal premiums; back-to-back transactions cut price and credit exposure; access to export channels (ports, terminals and shipping pools) expands commercial options and supports revenue stability.
River and port terminals serve as physical channels to distant markets, enabling Foresight Energy to reach export buyers within the ~1.1 billion tonne seaborne coal market in 2023–24. On-dock storage and blending (30–60 days capacity) refine specs to meet buyer requirements. Export gateways unlock geographic arbitrage, while real-time visibility tools cut transit uncertainty and reduce delays.
Conferences and industry networks connect Foresight Energy directly with buyers and peers, amplifying thought leadership that builds brand trust and shortens sales cycles. Market intelligence gathered at 2024 energy events, when global clean-energy investment reached about $1.3 trillion, informs dynamic pricing and risk assessment. Pipeline development accelerates through live demos and partner introductions, converting strategic contacts into measurable opportunities.
Relationship-led sales, competitive bids and trader networks drive utility and export volumes in 2024, with account teams enabling repricing/renewals and site trials lowering dispatch risk. RFP templates cut cycle times ~40% and data-led bids raised win rates up to 20% (post-bid debriefs +10ppt). River/port access with 30–60d blending supports entry to ~1.1bn t seaborne market.
| Channel | KPI | 2024 |
|---|---|---|
| Bids | RFP time | -40% |
| Sales | Win rate | +20% (est) |
| Exports | Market size | ~1.1bn t |
Power plants with FGD systems can burn high-sulfur coal (>1% sulfur) because wet scrubbers cut SO2 emissions by roughly 90–95% (EPA). These plants prioritize consistent calorific value—bituminous thermal coal typically runs about 11,000–13,000 Btu/lb—to secure steady heat rates and reliable deliveries. Long-term offtake contracts are aligned with typical plant asset lives of 30–50 years. Foresight’s cost leadership lowers delivered fuel cost, strengthening dispatch competitiveness.
Merchant generators and IPPs require flexible contracts tied to day-ahead and real-time market indices (eg Nord Pool, PJM) to match market exposure; index-linked pricing shifts price risk appropriately. Logistics reliability (fuel, grid access) directly limits imbalance costs, while performance guarantees—commonly 99.5% uptime SLAs—support plant availability and revenue certainty.
Process-heat users like industrial boilers and cement/lime kilns demand steady specs and uninterrupted supply; kilns typically require about 3.3 GJ/tonne and global cement output was ~4.1 billion tonnes in 2024. Delivery timing must align with production cycles to avoid costly downtime. Fuel blending meets unique kiln constraints and reliable service reduces changeover risks.
Overseas power and utility buyers source Illinois Basin coal via Gulf export terminals (New Orleans, Mobile, Houston) with contracts commonly indexed to seaborne benchmarks such as API2 and FOB Gulf in 2024. Quality assurance, sampling and timing are critical to meet calorific and sulfur specifications and avoid demurrage. Logistics partners coordinate vessel slots, transloading and ocean freight interfaces to ensure on‑time shipments.
Member-owned co-ops (serving about 42 million people in the US in 2024) and roughly 2,000 municipal utilities prioritize budget predictability; multi-year fixed or indexed supply contracts align with capital planning cycles and credit metrics, while smaller lot sizes and dispersed delivery points require flexible logistics and high service levels to maintain member loyalty.
Power plants (FGD: SO2 cut ~90–95% per EPA) seek 11,000–13,000 Btu/lb bituminous coal and long-term offtakes; merchant/IPPs need index-linked, flexible contracts; industrial heat/cement (global cement ~4.1B t in 2024) require steady specs and blending; co-ops (~42M members in 2024) and ~2,000 municipals demand multi-year predictability.
| Segment | Key metric (2024) | Contract type |
|---|---|---|
| Power w/FGD | SO2 ↓90–95%; 11–13k Btu/lb | Long-term |
| IPP/Merchant | Market-index (PJM, Nord Pool) | Index-linked/flexible |
| Cement/Industrial | Global cement 4.1B t | Steady specs/blends |
| Co-ops/Municipals | 42M members; ~2,000 utils | Multi-year fixed/indexed |
Skilled workforce costs dominate underground operations, with 2024 industry benchmarks showing labor and benefits typically representing 30–40% of operating costs. Robust training and safety programs — including annual refresher training and MSHA-compliant curricula — are essential to maintain certifications and limit lost-time incidents. Incentive structures tied to productivity and zero-injury metrics improve output and safety adherence. Retention lowers downtime and rework, reducing unit labor cost per ton.
Longwall shields, shearers and conveyors are the primary maintenance drivers for Foresight Energy, with wear parts, roof supports and explosives creating recurring cost lines. Industry data in 2024 shows maintenance typically comprises 10–20% of mining opex and predictive maintenance programs reduced unplanned failures by ~40% and maintenance spend by ~20%. Avoiding downtime preserves high-margin coal cashflows and protects EBITDA.
Electricity for ventilation, hoisting and prep plants is a material cost, often representing 10–25% of site operating expenses; industrial electricity in the US averaged about 0.08 USD/kWh in 2024. Diesel for equipment and logistics averaged roughly 3.80 USD/gal in 2024, adding volatility to fuel-led fleets. Targeted efficiency projects (LEDs, variable-speed drives, fleet electrification) have cut energy intensity 5–15% in realized cases. Fixed-price contracts and fuel hedges are used to limit price swings.
Royalty payments and lease obligations for Foresight Energy scale directly with tonnage sold, creating a variable cost tied to production volumes.
Permitting, environmental monitoring, and regulatory reporting impose fixed annual costs that persist regardless of short-term output.
Reclamation accruals are reserved to meet legally mandated mine-closure obligations, while legal and insurance expenses hedge residual operational and compliance risk.
Loadout, terminal handling and demurrage materially drive delivered cost; industry practice in 2024 showed demurrage and idle-time exposures adding roughly 5–15% to delivered coal cost depending on port congestion and contract terms.
Sales, admin and IT fund commercial operations and customer service; SG&A typically runs in the high single-digits of revenue, supporting pricing, contracting and credit functions.
Data systems now enable real-time scheduling and QA, cutting dispatch and billing errors (industry reports in 2024 cite ~20% fewer exceptions); tight cost governance prevents overhead creep.
Labor and benefits drive 30–40% of operating costs, with retention and safety lowering unit labor per ton. Maintenance (10–20%) and longwall component wear are key recurring spends; predictive maintenance cuts failures ~40%. Energy (10–25%) is material — US industrial electricity ~0.08 USD/kWh and diesel ~3.80 USD/gal (2024). Royalties, demurrage (5–15%) and reclamation accruals scale with production.
| Metric | 2024 Benchmark |
|---|---|
| Labor % of opex | 30–40% |
| Maintenance | 10–20% |
| Energy % opex | 10–25% |
| Electricity | 0.08 USD/kWh |
| Diesel | 3.80 USD/gal |
| Demurrage | 5–15% |
| SG&A | High single-digits % rev |
Multi-year offtakes with committed volumes anchor cash flows, insulating Foresight Energy against spot volatility and supporting bankable revenue forecasts; coal still supplied about 19% of US power in 2023–24, underscoring stable demand. Indexation and collars balance price exposure versus market swings. Quality adjustments fine-tune realised pricing per calorific value and sulfur content. Reliability of supply drives renewals and extensions.
Foresight captures opportunistic volumes during price spikes, where spot premiums can exceed baseline by 10–20% in volatile 2024 regional markets. Flexible production lets the company ramp within 24–48 hours to meet sudden demand. Short lead times of 1–3 days favor nearby industrial and power buyers, while transparent specs and testing cut transaction time and settlement friction.
Seaborne sales are priced off Argus API2/API4 benchmarks, with 2024 average API2 ~98 USD/t and API4 ~115 USD/t used as contractual references for Foresight Energy export contracts.
Logistics uplift of typically 3–8 USD/t captures port arbitrage and incremental margin when route economics permit, while terminal services are either bundled into price or passed through at cost.
FX exposure and freight rate volatility are hedged contractually via USD invoicing, forward FX contracts and voyage/freight rate clauses; Baltic Dry/TC exposures were managed through time-charter and voyage charters in 2024.
FOB/CIF structuring can capture logistics spreads (reported in 2024 at roughly $1–5/ton on U.S. coal trades), while optimized rail-to-barge routing reduces transit cost and dwell time, adding measurable margin. Efficient loadouts cut third-party handling fees (typical savings $0.5–2/ton in 2024), and service bundling (fuel, storage, scheduling) lifts total freight and logistics margin.
Custom blends command premiums for meeting tight specs, with 2024 industry data showing blend premiums typically 2–8% above standard cargo prices; embedded technical support and grade QA can be bundled into price to capture value. Stockpile management and storage fees (commonly $0.5–2/ton-month in 2024 terminals) generate steady recurring revenue, while penalty avoidance preserves realized price and reduces volatility.
Multi-year offtakes (covering ~70–85% of 2024 volumes) anchor cash flow while indexation/collars and quality adjustments temper price risk; spot premiums during 2024 spikes reached +10–20%. Seaborne pricing referenced API2 ~$98/t and API4 ~$115/t (2024); logistics uplifts $3–8/t and FOB/CIF spreads $1–5/t add margin. Storage $0.5–2/t‑month; blend premiums 2–8%.
| Metric | 2024 Value |
|---|---|
| Offtake coverage | 70–85% |
| Spot premium | +10–20% |
| API2 / API4 | $98 / $115 per t |
| Logistics uplift | $3–8 per t |
| FOB/CIF spread | $1–5 per t |
| Storage fee | $0.5–2 per t‑month |
| Blend premium | 2–8% |


