
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
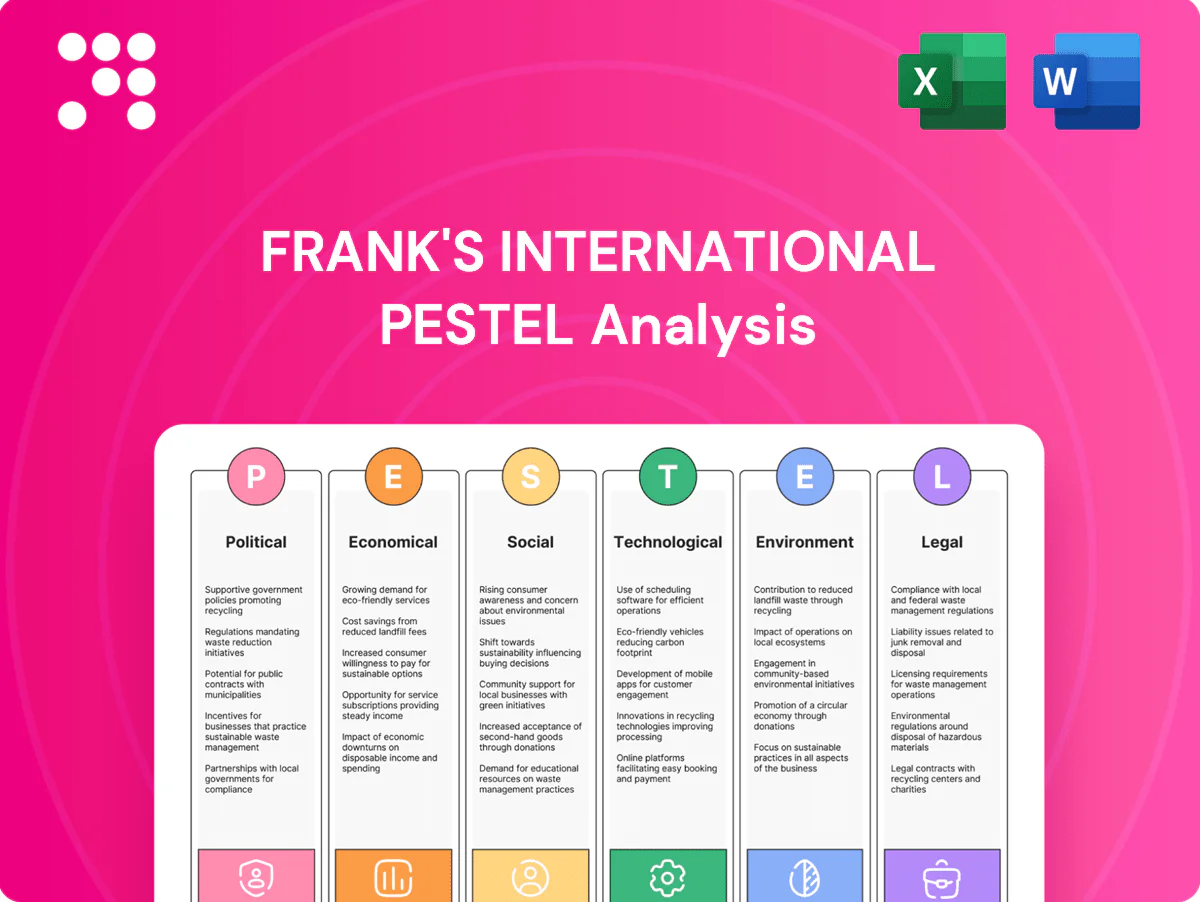
Gain a strategic edge with our PESTLE Analysis of Frank's International—uncover political, economic, social, technological, legal and environmental forces reshaping its market position. Ideal for investors, advisors, and strategists, this concise briefing highlights risks and growth levers. Purchase the full, editable report for detailed data, scenarios, and actionable recommendations to drive smarter decisions.
Government shifts between hydrocarbons and renewables directly affect drilling volumes and service demand; renewables made roughly 43% of global power capacity additions in 2024 (IEA), reducing long‑term upstream growth in some markets.
Subsidies, licensing rounds and local content rules can swing project NPV by tens of percentage points; several 2024 licensing rounds in West Africa and Brazil reopened multi‑billion dollar development pipelines.
Post‑merger Expro/Frank’s presence across 20+ jurisdictions diversifies revenue but raises regulatory complexity and compliance costs; continuous monitoring of national energy strategies is critical to forecast order pipelines.
Operations span politically volatile regions where sanctions, conflict or regime change can halt projects; global military spending rose to $2.24 trillion in 2023 (SIPRI), reflecting heightened risk. Offshore hotspots like the South China Sea, claimed by six states and carrying roughly 30% of global shipping, pose maritime‑boundary sensitivities. Sanctions from US/EU/UK constrain contracts and supply chains, forcing risk‑adjusted pricing and contingency planning to protect margins.
Tubulars, connections and equipment commonly face import duties up to 25% in key markets and periodic anti-dumping measures that raise landed costs and restrict quotas. Shifting trade alliances and route changes have lengthened shipping lead times by 20–35% on some corridors since 2022, raising inventory carrying costs. Local manufacturing incentives—often requiring 30–40% local content—make in‑country assembly or JV partnerships attractive; strategic procurement and a localized footprint mitigate cost and delay risks.
Infrastructure and permitting—port capacity, customs efficiency and permitting speed—directly affect job execution and cost; typical offshore permitting delays range 6–18 months and can trigger budget overruns and liquidated damages equal to 0.1–0.5% of contract value per delayed week in recent project cases (2024–2025).
Contract awards in higher-corruption jurisdictions increase governance risk for Frank; Transparency International's Corruption Perceptions Index (2023) reports a global average of 43/100, highlighting systemic exposure in many markets. Strict anti-bribery compliance (e.g., OECD/US FCPA standards) reduces legal risk but often lengthens deal cycles and diligence time. Political instability can threaten workforce safety and mobilization, making rapid evacuation or access restrictions likely. Robust ethics programs and third-party due diligence are essential risk mitigants.
Government energy shifts and subsidies reshape drilling demand—renewables accounted for ~43% of global power capacity additions in 2024 (IEA). Licensing rounds in 2024 reopened multi‑billion pipelines while sanctions, conflicts and $2.24T global military spend (2023, SIPRI) raise operational risk. Import duties up to 25%, 30–40% local content rules and 6–18 month permitting delays materially affect project economics.
| Metric | Value |
|---|---|
| Renewables (2024) | ~43% |
| Military spend (2023) | $2.24T |
| Import duties | up to 25% |
| Local content | 30–40% |
| Permitting delays | 6–18 months |
 Detailed Word Document
Provides a concise PESTLE evaluation of Frank's International, examining Political, Economic, Social, Technological, Environmental, and Legal factors with data-driven insights and trend context to identify risks and opportunities for executives, investors, and strategists; formatted for direct use in reports and planning.

 Customizable Excel Spreadsheet
A concise, visually segmented PESTLE summary of Frank's International that can be dropped into presentations or shared across teams to enable quick alignment, focused discussion of external risks and market positioning, and editable notes for specific regions or business lines.
Brent crude averaged about $85–90/bbl in 2024 and into early 2025, and E&P capex rose roughly 10% in 2024 per Rystad Energy, so demand for tubular running services closely tracks Brent/WTI cycles. Downturns defer drilling while upcycles drive offshore and deepwater activity; Frank's-Expro must scale capacity to capture peaks without overspending in slumps. Flexible cost structures and variable staffing are therefore essential.
Higher policy rates (US fed funds ~5.25–5.50% mid‑2025; 10‑yr Treasury ~4.2%) raise project hurdle rates and customer borrowing costs, delaying FIDs. Supplier financing and leasing alternatives can sway award timing and terms. The merged entity’s higher capital costs compress pricing competitiveness versus lower‑cost rivals. Prudent leverage (target net debt/EBITDA ~1.5–2.5) and strong liquidity buffers boost resilience.
Steel tubulars, threading and logistics costs remain volatile as steel (HRC) averaged about $700/t in 2024 and container freight rates, while down from 2021 peaks, stayed roughly 1.5x pre-pandemic levels. Lead times of 8–20 weeks drive job readiness delays and higher inventory holding costs. Index-linked contracts and pass-through clauses have protected margins in 2023–24, while vendor diversification cuts single-point failure risk.
Global expansion (IMF 2024–25 growth ~3.1%) supports transport and petrochemical demand, keeping upstream drilling robust as oil demand reached ~101.7 mb/d in 2024 and is seen near 102.5 mb/d in 2025 (IEA). Efficiency gains and rising EV/renewable penetration dampen long-run oil-demand growth to below 1%/yr. Multi-year offshore rebounds (offshore capex +~20% in 2024) can clear service backlogs; scenario planning aligns capacity with demand paths.
Energy price cycles (Brent ~$85–90/bbl 2024–25) and higher rates (Fed ~5.25–5.50% mid‑2025; 10y ~4.2%) raise project hurdles, so flexible staffing, indexed contracts and prudent leverage (net debt/EBITDA ~1.5–2.5) are critical. Steel HRC ~$700/t and 8–20 week lead times push inventory and pass‑through clauses protect margins. FX exposure (USD ~59% reserves 2024) requires hedging and USD/EUR pricing.
| Metric | Value |
|---|---|
| Brent | $85–90/bbl (2024–25) |
| Fed rate | ~5.25–5.50% (mid‑2025) |
| Steel HRC | ~$700/t (2024) |
| USD reserves | ~59% (2024) |
The preview shown here is the exact Frank's International PESTLE Analysis you’ll receive after purchase—fully formatted and ready to use. The layout, content, and structure visible are identical to the downloadable file, with no placeholders or teasers. After checkout you’ll instantly get this final, professionally structured document.
High-risk offshore environments demand stringent HSE practices and often compliance with standards such as ISO 45001 and industry-led guidelines; Total Recordable Incident Rate (TRIR) is measured per 200,000 work-hours and is a key contracting metric. Clients increasingly award contracts based on safety records and TRIR, with leading operators linking prequalification to safety performance. Merging best practices improves training and incident prevention, while transparent reporting strengthens stakeholder trust.
Experienced rig crews and technicians remain scarce after industry downturns that saw the global offshore rig count fall roughly 50% post-2014, pressuring frontline capacity. Scaled training pipelines and apprenticeships are essential to rebuild skills and meet demand. Competition for subsea, digital and automation talent is intensifying, driving premium hiring. Strong retention reduces costly downtime and rework, protecting margins.
Host communities increasingly expect local hiring, procurement and social investment, with local content targets commonly set between 20–40% and leading firms allocating roughly 1–3% of profits to CSR. Poor engagement can spark protests and permit delays—often affecting up to a third of large extractive projects. Structured CSR and local content plans improve the licence to operate, and measuring outcomes (KPIs, third‑party audits) enhances credibility and investor confidence.
Operators now prioritize vendors that enable emissions reduction and responsible operations; routine gas flaring was about 145 billion cubic meters in 2022, making solutions that cut rig time and flaring especially valued. Over 90% of S&P 500 firms published sustainability reports by 2022, and transparent ESG disclosures are increasingly table stakes in tenders. Aligning services to client ESG targets measurably boosts win rates.
Societal pressure to decarbonize is reshaping policy and investor appetite, pushing Frank's International to highlight emissions controls and low‑carbon services; companies framed as enabling safer, cleaner operations face lower regulatory and investor scrutiny. Messaging on efficiency and integrity management strengthens trust and capital access.
Skilled offshore crews remain scarce after the post‑2014 downturn, driving higher hiring costs and need for apprenticeships. Clients award contracts on safety: TRIR per 200,000 hrs is a key prequalification metric. Host communities demand 20–40% local content and 1–3% CSR allocations; emissions focus persists (flaring ~145 bcm, 2022) and ESG disclosure is table stakes.
| Metric | Value |
|---|---|
| TRIR basis | per 200,000 hrs |
| Local content | 20–40% |
| CSR spend | 1–3% profits |
| Flaring | ~145 bcm (2022) |
| ESG reports | >90% S&P 500 (2022) |
High-spec premium tubular connections enhance well integrity in HP/HT environments (>10,000 psi, >150°C) and deepwater settings typically beyond 1,500 m, reducing leak and fatigue risk. Continuous innovation is required to meet tightening operating envelopes and material limits. Strategic partnerships with steel mills and OEMs accelerate metallurgy and design advances, while rigorous qualification testing and field validation underpin industry adoption.
Real-time torque-turn monitoring, automation and QA data can lower non-productive time by up to 20% in drilling operations, improving cycle times and cost-per-well. Integrated digital platforms enhance traceability and enable remote support across assets, consolidating logs and alerts for faster decisions. Rig-performance analytics drive continuous improvement and dynamic pricing (uptime gains ~10–15%), while cybersecurity rises in importance as average breach costs reached about 4.45 million USD per IBM 2023 report.
Automated pipe handling can cut personnel on deck by up to 50% and has been associated with roughly 30–40% fewer rig-floor incidents in industry case studies. Robotics standardize repetitive tasks, improving consistency and reducing non-productive time; vendors report rig-time savings of 5–15% that help justify high capex. Retrofit-friendly designs shorten installation to weeks, speeding fleet adoption.
Advances in corrosion-resistant alloys, coatings and thread compounds extend asset life in corrosive, sour and subsea environments, reducing intervention frequency; NACE International estimated corrosion costs at about 2.5 trillion USD globally (2013 estimate, widely cited). Collaboration with clients to match metallurgy to reservoir chemistry and optimize lifecycle costs differentiates Frank's International in tenders and service contracts.
Skills in well integrity, tubulars and intervention map directly to CCS, geothermal and P&A workflows; early pilots and tech adaptation unlock aftermarket and project revenue. Global CCS capture reached ~45 MtCO2/yr in 2024 and geothermal capacity is ~16 GW, underscoring market scale as standards and certifications evolve.
High-spec tubulars, corrosion-resistant alloys and automation reduce NPT by up to 20% and improve uptime ~10–15%, while real-time torque/analytics and retrofit robotics deliver 5–15% rig-time savings and ~30–40% fewer rig-floor incidents. CCS (≈45 MtCO2/yr in 2024) and geothermal (~16 GW) create adjacent markets; cybersecurity risk remains material (IBM breach cost $4.45M, 2023).
| Metric | Value |
|---|---|
| NPT reduction | up to 20% |
| Uptime gains | 10–15% |
| Rig-time savings | 5–15% |
| Rig-floor incident cut | 30–40% |
| CCS scale (2024) | ≈45 MtCO2/yr |
| Geothermal capacity | ≈16 GW |
| Average breach cost (2023) | $4.45M |
Strict offshore safety rules govern lifting, handling and pressure systems; major standards and certifications such as ISO 45001 have 100,000+ certified sites globally (ISO 2023). Non-compliance risks shutdowns, fines (US OSHA maximum serious-violation penalty rose to $156,259 in 2023) and reputational damage. Continuous audits and mandatory training are required, and harmonizing procedures post-merger reduces compliance gaps.
Discharge, emissions and waste rules are tightening globally—EU Carbon Border Adjustment Mechanism entered its transitional phase in October 2023 and pressures permit regimes. Permits and monitoring requirements increase administrative load, with the World Bank projecting global municipal solid waste will rise 70% by 2050 without action. Failure can jeopardize contracts and future bids, while proactive compliance reduces litigation and bid-risk.
Equipment and services destined for China, Russia, Iran or sanctioned entities often require export licenses; violations can trigger multi-million-dollar fines, criminal charges and debarment from government contracting. Robust, automated screening of end-users and intermediaries against sanctions lists and denied-party lists is essential. Compliance programs must update controls continuously to match rapidly changing regimes and license policies.
Indemnities, warranties and liquidated damages can shift project risk and, per WIPO 2024 data showing ~4.0m patent filings in 2023, IP protection for connection designs and data is commercially vital; clear ownership clauses in joint developments reduce costly disputes and strong contract management improves margin certainty and predictability.
Rotational offshore workforces depend on visas, cabotage and local labor rules; regulatory shifts can cut crew availability and lift mobilization costs. BIMCO/ICS project a seafarer shortfall of about 147,500 by 2025, heightening wage pressure. Compliance with STCW working-hour limits and union agreements is vital, and local partnerships ease permitting and crew sourcing.
Strict offshore safety, emissions and export-control laws raise shutdown, fine and contract-risk; non-compliance can trigger six-figure penalties and debarment. IP, indemnities and contract terms shift project P&L and litigation exposure. Crew, visa and cabotage rules (≈147,500 seafarer shortfall by 2025) raise mobilization costs.
| Risk | 2023–25 datapoint | Impact |
|---|---|---|
| Safety | ISO 45001: 100,000+ sites (ISO 2023) | Shutdowns/fines |
| Fines | OSHA max serious penalty $156,259 (2023) | Cash loss |
| Emissions | EU CBAM live Oct 2023 | Permit burden |
| IP | WIPO ~4.0m filings (2023) | Contract risk |
| Labor | BIMCO/ICS shortfall ~147,500 by 2025 | Wage & mobilization cost |
Clients increasingly favor efficiency-focused providers as tenders demand emissions measurement and disclosure under rules like the EU CSRD (applying to ~50,000 companies from 2024); Scope 3 often represents up to 80% of oilfield-services value-chain emissions, so reducing rig time and optimizing logistics materially cuts reported footprints. Investment in lower-carbon equipment, such as hybrid/electric rigs that can reduce fuel use by up to 40%, enhances competitiveness.
Tubular handling errors can cause well-control incidents, as seen in Deepwater Horizon where BP incurred roughly 65 billion USD in cleanup and settlements. Strong procedures and containment plans significantly reduce environmental harm. Rapid-response capability is a commercial differentiator. Comprehensive insurance plus regular crew training lower residual financial and operational risk.
Thread protectors, lubricants and packaging create distinct waste streams that can represent roughly 12–18% of Frank's supply‑chain material waste; improper disposal risks regulatory penalties under hazardous waste rules. Recycling and reuse programs have been shown to cut disposal and material costs by about 10–25%, and supplier collaboration can raise recycled-content rates toward 30%+, improving material circularity and lowering lifecycle costs.
Hurricanes, cyclones and heatwaves increasingly disrupt offshore schedules and supply chains, with climate-driven extreme events contributing to global weather-related economic losses estimated at roughly $200bn–$300bn annually by 2024; Frank's operations see seasonal peak delays of up to 30% in high-risk basins. Resilient logistics, seasonally adjusted planning and asset hardening have reduced downtime by as much as 35% in 2024 pilot programs, while geographic diversification spreads exposure and limits single-basin losses.
Offshore operations intersect sensitive habitats and marine life, with rising scrutiny as 8.9% of oceans were designated protected areas by 2024 and the 30x30 target pushing stricter controls through 2030. Noise, discharges and seabed disturbance face regulatory limits; environmental baseline studies and mitigation plans are often mandated. Baseline surveys typically cost $0.5–3M and mitigation can add 2–5% to CAPEX, while compliance smooths permitting and stakeholder acceptance.
Clients demand emissions disclosure (EU CSRD ~50,000 firms from 2024); Scope 3 can be ~80% of oilfield-services emissions so rig-time and logistics cuts matter. Hybrid/electric rigs cut fuel use up to 40%; recycling reduces waste costs 10–25%. Extreme weather causes up to 30% seasonal delays; asset hardening cut downtime ~35% in 2024 pilots.
| Metric | Value |
|---|---|
| CSRD coverage | ~50,000 firms (2024) |
| Scope 3 share | Up to 80% |
| Fuel reduction | Up to 40% |
| Waste cost cut | 10–25% |
| Weather delays | Up to 30% |
| Downtime reduction | ~35% (2024 pilots) |


