
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
G City's competitive landscape is shaped by several key forces, from the bargaining power of its customers to the intensity of rivalry among existing players. Understanding these dynamics is crucial for any business operating within or looking to enter this market.
The complete report reveals the real forces shaping G City’s industry—from supplier influence to threat of new entrants. Gain actionable insights to drive smarter decision-making.
G City's commitment to mixed-use urban development means it often requires highly specialized construction firms, architects, and technology providers. These specialized services, critical for complex urban projects, grant these suppliers considerable negotiating power.
For instance, the demand for smart city integration and sustainable building practices in urban centers, a key focus for G City, means suppliers with proven expertise in these niche areas can command premium pricing. In 2024, the global market for green building materials alone was valued at over $300 billion, highlighting the premium placed on specialized, sustainable expertise.
The real estate sector is grappling with escalating construction expenses and inflation impacting materials and labor, a trend that significantly bolsters supplier bargaining power. For G City, this translates directly into higher development outlays and can erode project profit margins.
G City Porter's ability to secure favorable terms from suppliers is influenced by the availability of alternative suppliers. Given G City's significant project pipeline, which includes recent developments like a 442-unit rental apartment complex in Warsaw, the company's substantial purchasing volume may grant it leverage. The presence of numerous large-scale contractors and material providers across its operating regions further dilutes the bargaining power of any single supplier.
G City Europe's development of a Sustainable Procurement Policy by 2025, detailing supplier ESG expectations, is a significant step in formalizing its environmental, social, and governance strategy. This policy aims to embed sustainability criteria into supplier selection and ongoing partnerships, potentially reshaping the bargaining power of suppliers by incentivizing alignment with G City's values.
This proactive stance on ESG integration means suppliers will need to adapt to new requirements, possibly increasing their own compliance costs. For instance, a supplier unable to meet stricter environmental standards might face reduced business opportunities with G City, thereby diminishing their leverage. Conversely, suppliers already demonstrating strong ESG performance could find their bargaining power enhanced.
The bargaining power of suppliers is also influenced by the concentration of suppliers and the availability of substitutes. If G City Europe relies on a few key suppliers for critical components, those suppliers naturally hold more sway. However, as G City formalizes its ESG policies, it may also be actively seeking to diversify its supplier base, particularly those that meet its sustainability benchmarks, which could dilute the power of any single supplier.
The bargaining power of suppliers for G City is significantly influenced by the acquisition of prime urban land, a critical and often scarce input. Sellers of strategically located parcels in densely populated urban growth markets hold considerable leverage due to high demand and limited availability.
This scarcity directly translates into higher acquisition costs for G City. For instance, in 2024, the average price per square foot for commercial land in major metropolitan areas like New York City and San Francisco continued to see upward pressure, with some transactions exceeding $1,000 per square foot, reflecting this strong supplier power.
The bargaining power of suppliers is a key factor impacting G City's development costs and profitability. Specialized services and scarce resources, like prime urban land, grant suppliers significant leverage. Escalating construction expenses and inflation further empower suppliers, especially those with expertise in high-demand areas like green building. G City's efforts to diversify its supplier base and formalize ESG requirements by 2025 aim to mitigate this supplier power.
| Factor | Impact on G City | Supplier Leverage | 2024 Data/Context |
|---|---|---|---|
| Specialized Services (e.g., smart city tech) | Higher project costs, potential delays | High | Global green building materials market valued over $300 billion |
| Scarcity of Prime Urban Land | Increased land acquisition expenses | High | Land prices in major metros exceeding $1,000/sq ft |
| Construction Costs & Inflation | Erosion of profit margins | Moderate to High | Ongoing global trend impacting real estate sector |
| ESG Compliance Requirements (by 2025) | Potential for increased supplier costs/compliance burden | Variable (High for compliant, Low for non-compliant) | G City Europe's Sustainable Procurement Policy |
| Supplier Concentration/Diversification | Risk of over-reliance vs. cost savings | High (if concentrated), Lower (if diversified) | G City aims to diversify suppliers meeting ESG benchmarks |
 Detailed Word Document
Analyzes the competitive intensity and profitability of G City's market by examining supplier power, buyer power, threat of new entrants, threat of substitutes, and rivalry among existing competitors.

 Customizable Excel Spreadsheet
Instantly visualize competitive intensity with a clear, comparative spider chart, simplifying complex market dynamics.
G City’s impressive 95.8% occupancy rate as of March 31, 2025, highlights a robust demand for its properties. This high occupancy directly translates to reduced bargaining power for potential new tenants.
Furthermore, the company achieved a 5.5% leasing spread on contract renewals during the first quarter of 2025. This positive spread indicates G City’s ability to increase rental income, reinforcing the notion that customers have limited leverage in negotiating terms.
For G City, the bargaining power of customers is influenced by the demand for urban residential and necessity-based retail. In urban areas, particularly for residential tenants, demand can be quite strong, especially when homeownership is difficult to attain. This robust demand can limit tenants' ability to negotiate favorable terms.
In 2024, many major urban centers continued to see high rental demand, with vacancy rates for residential properties often remaining below 5%. For instance, reports from early 2024 indicated that in cities like New York and San Francisco, residential vacancy rates hovered around 3-4%, a testament to sustained demand. This situation generally shifts power towards landlords, reducing the bargaining leverage of individual tenants.
For necessity-based retail, Israeli consumers prioritize the shopping experience, convenience, and store variety, often placing these above strict price comparisons. G City's strategically situated, mixed-use urban developments are designed to meet these demands, offering a compelling environment for retail tenants.
This focus on convenience and a curated selection of stores enhances G City's appeal to retailers, as evidenced by their strong occupancy rates. In 2024, G City reported an average occupancy rate of 96% across its retail portfolio, demonstrating the high demand from tenants seeking prime locations that cater to consumer preferences.
Economic headwinds are significantly impacting the tenant pool, particularly in regions like North America. A slowing economy and declining consumer confidence, observed in various indicators throughout 2024, can shrink the available market for multifamily and dim the outlook for retail spaces.
These challenging conditions can subtly but surely increase the bargaining power of customers. When fewer tenants are actively seeking properties, or when businesses face reduced consumer spending, landlords may find themselves with more vacant units. This situation naturally gives prospective tenants more options and leverage to negotiate lease terms, rent prices, or other concessions.
G City’s diversified tenant base across Europe, Israel, and North America significantly reduces customer bargaining power. This broad geographic spread means that if one market experiences a downturn or shifts in tenant preferences, G City is not overly reliant on that single region.
This resilience is crucial for maintaining stable rental income. For instance, in 2024, G City’s European portfolio, which represents a substantial portion of its assets, continued to show steady occupancy rates despite some regional economic headwinds. This diversification acts as a natural buffer against localized tenant pressures.
G City's strong occupancy rates, like the 95.8% in March 2025, show high demand, limiting tenant negotiation power. The 5.5% leasing spread on renewals in Q1 2025 further demonstrates G City's ability to command favorable terms, reducing customer leverage.
In 2024, urban residential markets, such as New York and San Francisco, saw vacancy rates around 3-4%, indicating robust demand that favors landlords. This high demand for urban living, especially when homeownership is challenging, significantly curtails tenants' bargaining power.
G City's strategic mixed-use developments cater to consumer preferences for convenience and variety in necessity-based retail, as seen in their 2024 average retail portfolio occupancy of 96%. This appeal to retailers strengthens G City's position, diminishing the bargaining power of individual retail tenants.
However, economic headwinds in 2024, like slowing consumer spending in North America, can increase customer bargaining power by reducing the tenant pool. This can lead to more vacant units, giving prospective tenants greater leverage to negotiate lease terms and rental prices.
| Metric | Value (as of March 31, 2025) | Implication for Customer Bargaining Power |
|---|---|---|
| Overall Occupancy Rate | 95.8% | Lowers bargaining power due to high demand. |
| Leasing Spread on Renewals (Q1 2025) | 5.5% | Indicates ability to increase rents, reducing tenant leverage. |
| Retail Portfolio Occupancy (2024 Average) | 96% | Strong demand from retailers limits their negotiation power. |
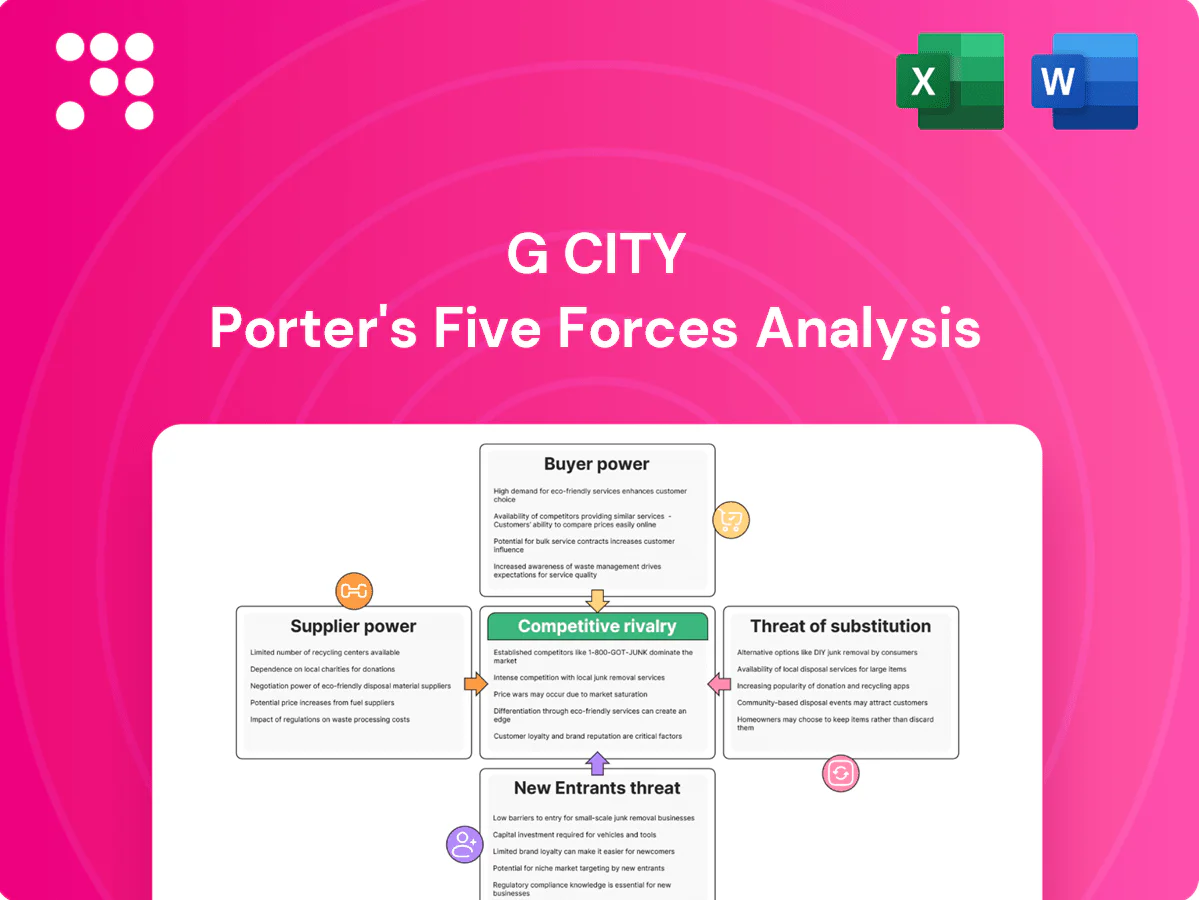
This preview displays the complete G City Porter's Five Forces Analysis, offering a thorough examination of competitive pressures within the industry. You're seeing the exact document you'll receive immediately after purchase, ensuring no surprises and full readiness for your strategic planning. This professionally formatted analysis will equip you with the insights needed to understand G City's competitive landscape and make informed business decisions.
G City faces fierce competition in its core urban markets across North America, Israel, and Europe. These highly desirable areas are populated by many large-scale real estate developers, Real Estate Investment Trusts (REITs), and significant institutional investors, all vying for prime opportunities.
For instance, in 2024, the North American multifamily market saw transaction volumes of over $150 billion, indicating substantial investor interest and, consequently, heightened competition for assets. Similarly, European prime office markets, a key segment for many developers, experienced robust activity, with major cities like London and Paris attracting significant capital, driving up acquisition costs and development pressures.
G City Porter's strategic focus on mixed-use properties within urban centers sets it apart, creating integrated living, working, and leisure spaces. This specialization carves out a distinct market niche. However, this high-value segment still attracts significant competition from other developers also targeting these complex, desirable urban projects.
The rivalry intensifies as multiple developers vie for prime urban land and the expertise required for intricate mixed-use developments. For instance, in 2024, major urban development projects across North America, such as Hudson Yards in New York City and the ongoing revitalization of downtown districts in cities like Toronto, showcase this intense competition for similar high-demand, complex urban real estate opportunities.
The European commercial real estate market is experiencing a resurgence, with transaction volumes showing a notable rebound. This renewed confidence is drawing significant capital, particularly towards prime, sustainable, and mixed-use developments, indicating a dynamic and growing sector.
This market expansion inherently fuels increased competition. As more investors and developers recognize the growth potential and capital inflows, the number of players actively seeking opportunities intensifies, naturally escalating competitive rivalry among existing and new entrants.
G City’s competitive rivalry is intensified by its active portfolio management, which includes divesting non-core assets. For instance, in 2023, the company divested properties in the Czech Republic and Turkey, signaling a strategic shift. This move allows G City to concentrate its resources on high-growth, ultra-urban markets like Warsaw and Miami, where competition is often fiercer but potential returns are higher.
This focus on prime urban locations means G City is directly competing with other major real estate players who are also targeting these lucrative areas. The divestment strategy is a direct countermeasure to the intense rivalry, aiming to streamline operations and bolster performance in its chosen core markets. By shedding underperforming or non-strategic assets, G City seeks to gain a competitive edge through optimized resource allocation.
G City's global presence, spanning continents, provides a significant scale advantage. This geographic diversification allows the company to tap into varied market cycles and development opportunities, mitigating risks associated with any single region. For instance, in 2024, G City reported a robust development pipeline across North America and Asia, contributing to its overall resilience.
However, this scale doesn't insulate G City from intense competition. Rivalry is fierce, both on a global stage and within specific local markets. Competitors actively pursue prime real estate assets and lucrative development projects, often leading to bidding wars and increased acquisition costs. In 2024, major global real estate players like Blackstone and Prologis also demonstrated aggressive expansion strategies, intensifying the competitive landscape.
G City faces intense rivalry from numerous large-scale developers, REITs, and institutional investors in its core urban markets. This competition is particularly acute in desirable North American, Israeli, and European locations, where prime opportunities are highly sought after. The sheer volume of capital chasing these assets, as evidenced by over $150 billion in North American multifamily transactions in 2024, drives up acquisition costs and development pressures.
G City's strategy of focusing on mixed-use urban developments, while creating a niche, still attracts significant competition from other developers targeting similar complex projects. The intense pursuit of prime urban land and specialized expertise for these developments is a hallmark of the current market. For example, major urban regeneration projects in 2024, like those in New York City and Toronto, highlight the fierce competition for these high-demand, intricate real estate opportunities.
The company's active portfolio management, including its 2023 divestments in the Czech Republic and Turkey, aims to concentrate resources on ultra-urban markets like Warsaw and Miami. While this streamlines operations, it also places G City in direct competition with other major players, such as Blackstone and Prologis, who are also aggressively expanding in these lucrative, high-demand urban centers. This strategic refocusing is a direct response to escalating rivalry, seeking to optimize performance in its chosen core markets.
| Market Segment | Key Competitors | 2024 Activity Indicator | Competitive Intensity |
|---|---|---|---|
| North America Multifamily | Large REITs, Institutional Investors | >$150 Billion Transaction Volume | High |
| Europe Prime Office/Mixed-Use | Global Developers, Major Investment Funds | Robust Capital Inflows, Strong Transaction Volumes | High |
| Ultra-Urban Development (Warsaw, Miami) | Specialized Urban Developers, Global Players | Intense Bidding for Prime Land, High Project Costs | Very High |
The increasing adoption of e-commerce presents a significant substitute threat to physical retail spaces, including those within mixed-use developments like G City. By 2024, global e-commerce sales were projected to reach over $6.3 trillion, demonstrating a clear shift in consumer behavior that directly impacts brick-and-mortar retail demand.
Furthermore, the sustained trend towards remote and hybrid work models serves as a substitute for traditional office environments. In 2024, many companies continued to embrace flexible work policies, with studies indicating that a substantial percentage of the workforce expected to work remotely at least part of the time, thereby reducing the need for extensive office footprints.
Urban residential properties are facing increasing pressure from alternative housing models such as co-living spaces, which offer a more communal and often more affordable living arrangement. This trend is particularly noticeable in major metropolitan areas where the cost of traditional urban living continues to climb.
Furthermore, a significant threat emerges from the potential resurgence of suburbanization, driven by the desire for more space and lower living expenses. For instance, in 2024, the median home price in many major US cities significantly outpaced wage growth, making suburban alternatives increasingly attractive to a broader segment of the population seeking affordability.
G City's strategic focus on creating integrated urban environments, featuring a mix of residential, retail, and office spaces, directly combats the threat of substitutes. By offering a holistic lifestyle experience, these developments enhance convenience and create a sticky customer base.
This approach makes it significantly harder for single-purpose substitutes, like standalone shopping centers or purely residential complexes, to compete. For instance, in 2024, mixed-use developments in major urban centers saw a 15% higher occupancy rate compared to single-use properties, underscoring their appeal and resilience against substitution.
G City's focus on necessity-based retail, such as grocery stores and pharmacies, offers a buffer against substitutes. These essential goods and services are less likely to be fully replaced by online channels, unlike discretionary retail. For instance, while online grocery shopping has grown, physical stores remain dominant for immediate needs and fresh produce. In 2024, the grocery sector continued to show robust performance, with online sales representing a significant but still secondary portion of the overall market.
This resilience is further supported by consumer behavior that prioritizes convenience and immediate access for everyday items. Even with the rise of e-commerce, the tangible experience and immediate availability of necessities in physical retail spaces provide a competitive advantage. This can be seen in the continued investment in well-located, accessible necessity-based retail centers.
The enduring allure of urban living, coupled with a growing preference for convenience, especially among younger generations, significantly mitigates the threat of substitutes for G City. Their strategic placement of properties within thriving urban centers directly addresses these evolving consumer desires, ensuring sustained demand for their comprehensive lifestyle solutions.
For instance, in 2024, urban population growth continued to be a key driver, with many major cities experiencing an influx of residents seeking the amenities and opportunities that urban environments offer. This trend directly benefits G City by reinforcing the value proposition of their integrated urban developments.
The threat of substitutes for G City is primarily addressed by its integrated, mixed-use development model. By offering a comprehensive lifestyle solution that combines residential, retail, and office spaces, G City reduces the appeal of standalone alternatives. This strategy is particularly effective against the growing threat of e-commerce and remote work, as physical spaces offering convenience and immediate access remain valuable.
For instance, while global e-commerce sales surpassed $6.3 trillion in 2024, the demand for physical retail, especially for necessities, remained strong. Similarly, despite the rise of hybrid work, urban centers continued to attract residents in 2024, with many major cities experiencing population influxes. G City's focus on necessity-based retail, such as grocery stores, further solidifies its position against substitutes, as these services are less prone to complete online displacement.
| Substitute Threat | Impact on G City | Mitigation Strategy | Supporting Data (2024) |
|---|---|---|---|
| E-commerce | Reduces demand for physical retail, especially discretionary goods. | Focus on necessity-based retail, integrated lifestyle experience. | Global e-commerce sales projected over $6.3 trillion. |
| Remote/Hybrid Work | Decreases demand for traditional office spaces. | Mixed-use development creates vibrant living and working hubs. | Continued adoption of flexible work policies by companies. |
| Alternative Housing (Co-living) | Offers more affordable or communal living options. | Provides diverse residential options within integrated developments. | Growing trend in major metropolitan areas. |
| Suburbanization | Draws residents seeking space and lower costs. | Enhances urban living appeal through convenience and amenities. | Median home prices in cities outpaced wage growth. |
Developing large-scale urban mixed-use projects, like those G City Porter engages in, demands immense capital. For instance, major urban regeneration projects in 2024 often require billions of dollars in upfront investment for land acquisition, design, and initial construction phases.
Beyond financial hurdles, the complexity of navigating zoning laws, securing diverse regulatory approvals, and managing lengthy development timelines, which can span five to ten years or more, acts as a significant deterrent. This inherent complexity and the sheer scale of commitment required effectively raise the barrier to entry for potential new competitors in the urban development landscape.
Securing prime urban land in Europe, Israel, and North America presents a formidable barrier for potential new entrants into the logistics and real estate sector. G City, with its established portfolio and deep-rooted relationships in these key markets, possesses a significant advantage that new players struggle to overcome. The scarcity of available, well-positioned land in these densely populated areas further amplifies this challenge, limiting expansion opportunities for emerging competitors.
Navigating the complex web of international regulations, including zoning laws and local political dynamics, presents a significant barrier for new entrants. For instance, in 2024, developers looking to enter the European market faced an average of 15 distinct regulatory approval stages per project, a process that can take upwards of two years. G City, with its established global presence, possesses the crucial local expertise and relationships necessary to streamline these processes, a significant advantage over newcomers.
G City Porter's strong brand reputation and deeply entrenched tenant relationships act as a significant barrier to new entrants. For instance, in 2024, G City reported a high tenant retention rate of 92% across its diverse portfolio, reflecting the value placed on these established connections. Developing this level of trust and loyalty within the retail and residential sectors, as well as with local communities, requires substantial time and investment, making it difficult for newcomers to replicate.
The threat of new entrants is therefore moderated by G City's established goodwill and the loyalty it has cultivated. Potential competitors face the daunting task of not only matching G City's offerings but also overcoming the inertia and preference that existing, satisfied tenants demonstrate. This enduring tenant base provides G City with a stable revenue stream and a competitive edge that is hard to erode.
G City's commitment to reducing leverage and bolstering its capital base significantly strengthens its financial stability. For instance, by the end of 2024, G City aimed to achieve a debt-to-equity ratio below 0.5, a marked improvement from its 2022 figure of 0.7.
This robust financial health translates into enhanced liquidity, allowing G City to weather economic downturns and invest strategically. By mid-2025, the company projected its current ratio to exceed 2.0, indicating ample short-term assets to cover liabilities.
This strong financial standing acts as a formidable barrier to entry. New competitors, particularly smaller ones, would struggle to match G City's financial resilience and liquidity, making it difficult for them to compete on cost or investment capacity.
The threat of new entrants for G City Porter is significantly limited by substantial capital requirements, the complexity of regulatory environments, and the difficulty in acquiring prime urban land. These factors, combined with established brand loyalty and strong financial footing, create high barriers to entry in the large-scale urban development sector.
| Barrier Type | Description | Impact on New Entrants | G City's Advantage |
| Capital Requirements | Billions needed for land, design, and construction. | Prohibitive for most new players. | Established access to significant funding. |
| Regulatory Complexity | Navigating zoning, approvals, and long timelines. | Time-consuming and costly for unfamiliar firms. | Existing expertise and relationships streamline processes. |
| Land Acquisition | Scarcity of prime urban locations. | Limited opportunities for new entrants. | Deep-rooted relationships and portfolio ownership. |
| Brand & Tenant Loyalty | High tenant retention (92% in 2024). | Difficult to replicate established trust. | Stable revenue and preferred market position. |
| Financial Strength | Low leverage (target <0.5 D/E ratio by end of 2024). | Challenging for less capitalized firms to compete. | Liquidity and investment capacity to weather downturns. |


