
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Genesco's SWOT highlights resilient retail brands and omnichannel gains, balanced by supply-chain pressures and competitive retail headwinds; opportunites include expansion of footwear categories and international growth. Want deeper, research-backed insights and strategic tools? Purchase the full SWOT for a professionally formatted Word report and editable Excel model to plan, pitch, and invest with confidence.
Genesco’s diversified footwear portfolio spans four banners—Journeys, Schuh, Little Burgundy and Johnston & Murphy—covering teen, young‑adult and premium dress‑casual segments, which spreads demand risk across demographics and price points. Operating across North America and the UK, the breadth enables cross‑banner trend learning and merchandising, and supports buying scale via relationships with hundreds of vendors.
Genesco operates a blended network of brick-and-mortar and e-commerce channels—about 1,270 retail locations alongside expanding online sales—meeting customers where they shop. Buy-online-pickup-in-store and ship-from-store capabilities have improved inventory turns and convenience, helping omnichannel sales grow materially in recent years. This model can lift conversion and reduce markdowns, and it buffers traffic volatility in any single channel.
Genesco designs, sources and markets a mix of owned and licensed brands across banners like Journeys, Johnston & Murphy and Schuh, capturing more of the value chain and reducing reliance on third‑party suppliers. Vertical design and sourcing shorten lead times and enable faster trend response and banner‑specific customization, improving assortments. Controlled product differentiation supports margins by reducing markdown exposure, while licensing expands breadth without full development or inventory investment.
Journeys and Little Burgundy provide Genesco direct visibility into teen/young-adult fashion cycles and sneaker culture, enabling assortments, limited drops and collaborations that resonate; Journeys operates over 1,000 stores (2024). Rapid read-and-react merchandising limits fashion risk and boosts sell-through. Community and event marketing deepen local relevance and loyalty.
Genesco (NYSE: GCO) extends beyond the U.S. through Schuh in the UK and Ireland and Little Burgundy in Canada, giving the company a presence in three countries. That international scale diversifies revenue, delivers earlier trend signals, strengthens supplier leverage across regions, and enables cross-border best practices to improve systemwide operations.
Genesco (NYSE: GCO) benefits from a diversified footwear portfolio across four banners, spreading demand risk across teen, young‑adult and premium segments. The company operates ~1,270 retail locations with omnichannel capabilities (BOPIS, ship‑from‑store) and Journeys alone runs over 1,000 stores (2024). Vertical design, sourcing and owned/licensed brands shorten lead times, improve margins and enable faster trend response across three countries.
| Metric | Value | Note |
|---|---|---|
| Retail locations | ~1,270 | Stores + concessions |
| Journeys stores | >1,000 | 2024 |
| Banners | 4 | Journeys, Schuh, Little Burgundy, Johnston & Murphy |
| Countries | 3 | US, UK/Ireland, Canada |
| Omnichannel | BOPIS, SFS | Improves turns & conversion |
 Detailed Word Document
Provides a concise strategic overview of Genesco’s internal strengths and weaknesses and its external opportunities and threats, assessing competitive position, growth drivers, operational gaps, and key risks shaping the company’s future.

 Customizable Excel Spreadsheet
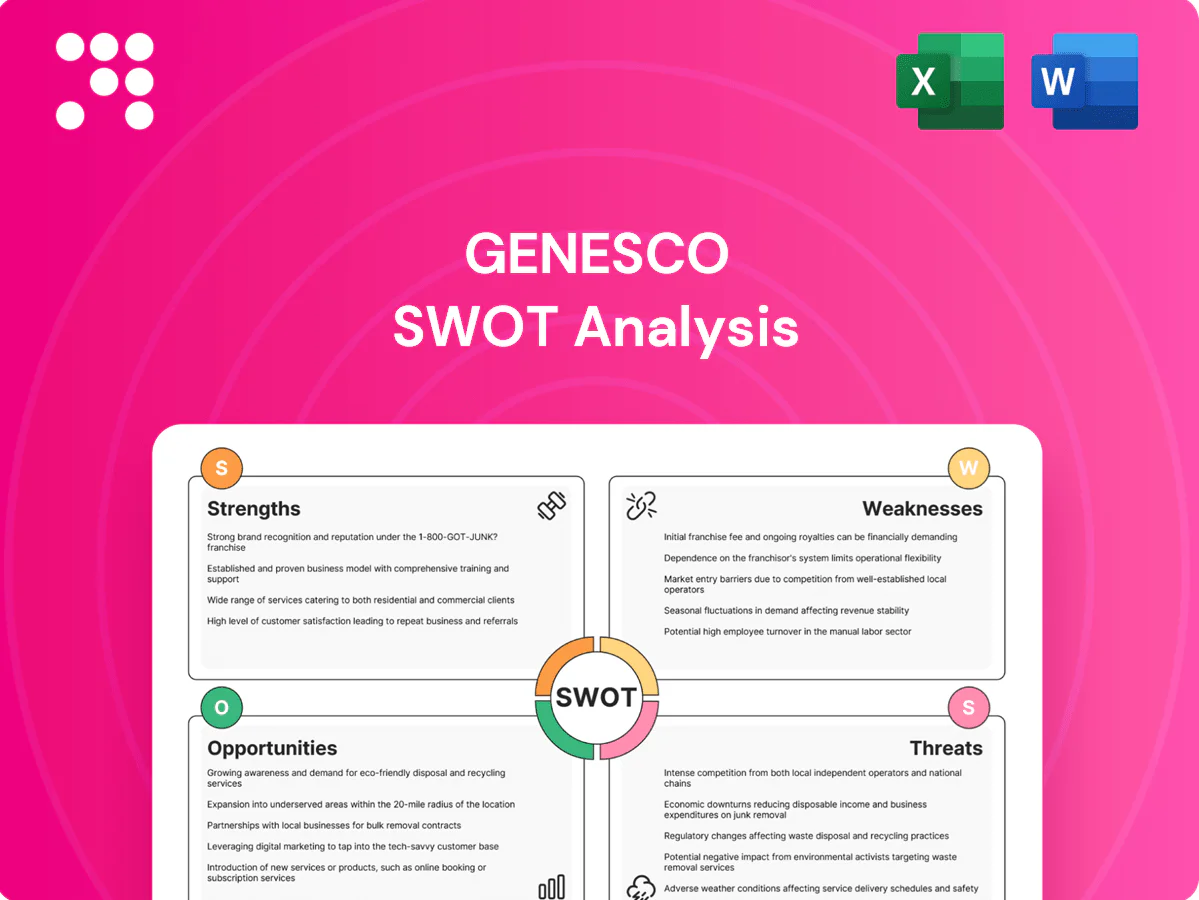
Provides a concise, visual SWOT matrix tailored to Genesco for fast strategic alignment and stakeholder-ready summaries; editable format enables quick updates to reflect retail trends, brand portfolio shifts, and operational priorities.
Footwear and teen apparel carry acute cyclicality with short trend windows, so fashion misreads quickly force markdowns and inventory write-downs. Reliance on a few hot brands and silhouettes increases revenue volatility across quarters. Maintaining the necessary buzz requires sustained, often rising, marketing and promotional spend. These dynamics amplify margin pressure when trends shift unexpectedly.
Many Genesco locations remain in malls and high-street zones highly sensitive to footfall declines; with FY2024 net sales near $1.8 billion, lower mall traffic can disproportionately hit store revenues. Rent and fixed labor costs create operating leverage on downturns, pressuring margins when same-store sales fall. Traffic shifts online—e-commerce growth in 2024 increased reliance on digital sales—reduces four-wall profitability, while inflexible leases slow rapid footprint optimization.
Vendor concentration—particularly reliance on marquee third-party brands—gives suppliers pricing and allocation power; Genesco acknowledged this risk in its 2024 Form 10-K. Scarcity or vendor DTC prioritization can constrain Journeys and other banners, limiting access to high-demand releases and reducing store and online traffic. If must-have brands demand higher wholesale costs, Genesco's margin mix can erode as it absorbs or passes through price increases.
Exposure in the UK and Canada introduces currency volatility that can swing reported results; hedging programs reduce but cannot remove translation and transaction noise. Cross-border logistics, tariffs and regulatory compliance increase operating cost and supply-chain complexity. Local consumer cycles in those markets can decouple from U.S. trends, complicating inventory and promotional planning.
Operational margin pressure stems from rising freight, wages and return costs that have inflated SG&A and COGS, contributing to a compressed margin profile; Genesco reported approximately $1.12 billion in net sales in fiscal 2024, limiting leverage. E-commerce growth increases fulfillment and return expenses and can dilute margins absent scale efficiencies, while heavy promotional cadence in footwear squeezes gross margin. Near-term EBIT faces headwinds from required investments in digital and data platforms.
Fashion cyclicality and dependence on a few hot brands create rapid markdown risk and revenue volatility; mall-heavy footprint and UK/Canada exposure amplify traffic and FX sensitivity. Rising freight, wages and return costs plus necessary digital investments compress near-term margins; Genesco reported $1.12 billion in net sales in FY2024.
| Weakness | 2024 datapoint |
|---|---|
| Revenue scale | Net sales $1.12B (FY2024) |
| Vendor risk | Noted in 2024 Form 10-K |
This is the actual SWOT analysis document for Genesco you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full SWOT report you'll get; purchase unlocks the entire in-depth version. The file is the real, editable report ready to use for strategy, valuation, or presentations.
Scaling Genesco’s e-commerce, mobile apps and loyalty programs can lift customer lifetime value as digital sales accelerate; personalization and recommendation engines have been shown to increase basket size by roughly 10–15% (McKinsey). Omnichannel services improve conversion and lower returns by smoothing buy-online/pick-up and returns flows, while enhanced data capture from apps and web behavior strengthens merchandising and inventory allocation decisions.
Expanding owned and licensed products can lift gross margins—industry data shows private-label programs often add roughly 200–300 basis points to margins—while Journeys' ~1,200-store footprint lets retailer exclusives drive traffic and differentiate banners. Faster design-to-shelf cycles enable Genesco to capitalize on micro-trends, and collaborations with artists and influencers have proven to amplify reach and boost sell-through rates in comparable footwear launches.
Rightsizing underperforming Genesco locations and relocating off-mall can improve ROIC by concentrating sales per square foot and lowering mall rents; JLL 2024 notes landlords offered lease concessions averaging 10–20% in many U.S. retail renewals. Smaller, experience-led formats cut fixed costs and raise conversion rates. Inventory pooling and ship-from-store boost inventory turns and fulfillment speed. Lease renegotiations can unlock meaningful rent savings.
Selective expansion of Schuh and Little Burgundy deepens Genesco non-U.S. presence, leveraging brands that contributed to the company’s global revenue mix after FY2024 when Genesco reported approximately $1.9 billion in net sales. Digital-first entry into adjacent geographies lowers capital risk by prioritizing e-commerce channels and marketplace launches. Wholesale partnerships and localized assortments can seed brand awareness and unlock incremental regional demand.
Johnston & Murphy's heritage enables premiumization across dress-casual and comfort lines to lift average unit retail and margin capture; Genesco reported fiscal 2024 net sales of approximately $1.1 billion. Strengthening DTC stores and e-commerce sharpens brand control and improves gross margins. Expanding accessories and benefiting from corporate/occasion wear recovery can increase wallet share and revenue per customer.
Scaling e-commerce, apps and loyalty can raise CLV as digital sales grow; personalization can boost basket size ~10–15% and private-label programs add ~200–300 bps to gross margin. Omnichannel, ship-from-store and lease renegotiations (JLL 2024: concessions 10–20%) improve turns and ROIC. Selective international, DTC and premium AUR moves leverage FY2024 net sales ~$1.9B to drive margin expansion.
| Opportunity | Metric/Impact |
|---|---|
| E‑commerce personalization | +10–15% basket |
| Private‑label | +200–300 bps GM |
| Lease renegotiation | 10–20% concessions (JLL 2024) |
Direct-to-consumer pushes by major brands and platforms — led by Amazon, which accounted for roughly 40% of US e-commerce in 2024 — intensify margin pressure on Genesco while specialty peers and fast-fashion (Shein, Zara) undercut on speed and price. Limited-release allocation battles and a growing resale market (projected to hit about $30 billion by 2030) divert store and online traffic. Category fragmentation raises customer-acquisition costs and compresses promotional power.
Footwear and accessories are highly discretionary and vulnerable to income shocks, making Genesco sales sensitive to consumer pullback. Recessions typically drive trade-down behavior and purchase delays, reducing average order values and SKU velocity. Higher interest rates—federal funds around 5.25–5.50% (mid‑2025)—can damp consumer credit‑fuelled spending. Macro volatility complicates inventory turns and pricing decisions, raising markdown risk.
Factory shutdowns, port congestion, and logistics bottlenecks can delay Genesco product flows, pushing inventory into higher storage costs and stockouts. Input cost spikes—raw materials, freight and duties—compress gross margins and pressure the company’s already thin footwear and accessory margins. Longer lead times heighten fashion risk as styles miss seasons, while compliance changes and geopolitical tensions add unpredictable sourcing and cost volatility.
Minimum wage remains $7.25 federally while many states have higher rates, and staffing shortages are driving retail labor costs higher for Genesco, pressuring margins. New privacy laws such as California's CPRA and evolving consumer-protection rules raise compliance costs; stricter environmental/sourcing standards can lift COGS, and noncompliance risks fines and reputational damage.
Foreign exchange volatility in GBP and CAD can swing reported revenue and profit for Genesco—about 7% of FY2024 net sales (~$1.55B) came from the UK and Canada, so a 10% move alters reported revenue by roughly $10–15M and can compress margins when pricing adjustments lag; hedging reduces volatility but incurs cost and basis risk often in the low‑millions annually, and currency shifts also change tourist-driven store traffic.
Direct-to-consumer pressure (Amazon ~40% of US e-commerce in 2024) and fast-fashion/resale (resale ≈ $30B by 2030) erode margins and traffic. Discretionary footwear sales are rate- and income-sensitive (fed funds ~5.25–5.50% mid-2025), raising markdown risk. FX exposure (UK/Canada ≈7% of FY2024 ~$1.55B sales ≈ $108M) can swing reported revenue materially.
| Threat | Key metric | Estimated impact |
|---|---|---|
| DTC/competition | Amazon ~40% US e‑commerce (2024) | Margin compression |
| Macro/rates | Fed funds 5.25–5.50% (mid‑2025) | Lower AOV, markdowns |
| FX | UK/CAD ~7% of sales (~$108M) | 10% move ≈ $10–15M rev swing |


