
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
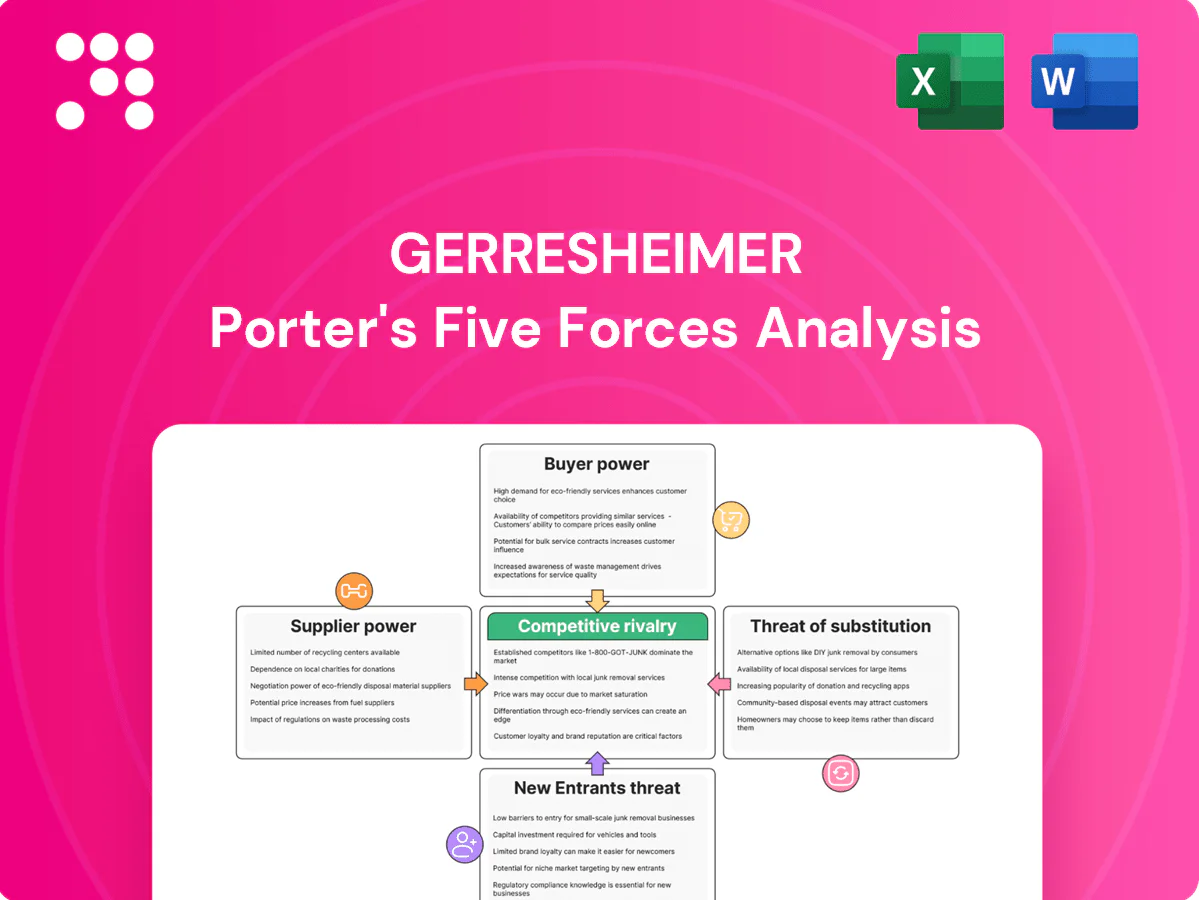
Gerresheimer faces significant competitive forces, from the bargaining power of its buyers in the pharmaceutical and healthcare sectors to the constant threat of new entrants seeking to disrupt the packaging market. Understanding these dynamics is crucial for any stakeholder.
The complete report reveals the real forces shaping Gerresheimer’s industry—from supplier influence to threat of new entrants. Gain actionable insights to drive smarter decision-making.
The bargaining power of suppliers for Gerresheimer is significantly shaped by the concentration of those providing essential raw materials. For instance, specialized glass, advanced polymers, and critical electronic components for sophisticated drug delivery devices are often sourced from a limited number of key players. If these suppliers are few and dominate their respective markets, they gain considerable leverage, potentially dictating pricing and supply conditions to Gerresheimer.
In 2024, the global market for pharmaceutical packaging materials, including specialized glass and polymers, showed continued consolidation. For example, the specialty glass sector, crucial for vials and syringes, saw major players like SCHOTT AG and Corning Incorporated holding substantial market share, indicating a concentrated supplier base for these high-specification inputs. This concentration means Gerresheimer must actively manage its supplier relationships to avoid unfavorable terms.
Gerresheimer faces significant supplier power due to high switching costs. For critical components in pharmaceutical packaging and drug delivery devices, changing suppliers involves extensive requalification processes, obtaining new regulatory approvals, and often acquiring specialized tooling. This complexity makes switching suppliers a lengthy and costly endeavor for Gerresheimer.
The stringent industry standards and validation requirements in the pharmaceutical sector mean that even minor changes to a supplier for a key component can necessitate a complete re-validation of the final product. This inherent inflexibility limits Gerresheimer's ability to negotiate aggressively with its established suppliers, as the cost and time to switch are substantial deterrents.
Suppliers providing highly specialized or proprietary components, especially for cutting-edge drug delivery devices, wield significant influence. For instance, if Gerresheimer depends on unique, patented materials or technologies from a sole provider, that supplier can effectively set the terms of engagement. This reliance can lead to strong interdependencies, often requiring close collaboration between Gerresheimer's research and development and design departments and these key suppliers.
The threat of suppliers integrating forward into Gerresheimer's business is a nuanced factor. If suppliers possess the capability and a strong incentive to produce finished packaging or device components themselves, their bargaining power naturally rises. This means they could potentially compete directly with Gerresheimer, dictating terms more forcefully.
For Gerresheimer, operating in specialized sectors like pharmaceutical packaging, this threat is generally considered lower. The complexity of regulatory compliance and specific market demands in pharmaceuticals makes it challenging for typical raw material suppliers to directly enter and compete in the finished product space. It's not as simple as a widget manufacturer deciding to make their own widgets.
However, the risk isn't entirely absent. For more standardized components within the packaging or device manufacturing process, the potential for supplier forward integration remains a valid consideration. For instance, a supplier of a common plastic resin might explore producing pre-formed containers if the market conditions are favorable and the investment is manageable.
Consider the broader packaging industry in 2024. While specific forward integration data for Gerresheimer's suppliers isn't publicly detailed, trends in material sourcing suggest a growing interest in value-added services. Suppliers who can offer more than just raw materials might see forward integration as a logical next step, especially if they perceive a gap in the market or an opportunity to capture more of the value chain.
The significance of Gerresheimer's business to its suppliers directly influences their bargaining power. When Gerresheimer accounts for a substantial percentage of a supplier's total sales, that supplier is likely to be more accommodating with pricing and service levels to retain this key customer. For instance, if a glass manufacturer derives 30% of its annual revenue from Gerresheimer, they have a strong incentive to maintain a positive relationship.
Conversely, if Gerresheimer represents only a minor portion of a supplier's revenue, the supplier's dependence on Gerresheimer is low. This reduced dependence allows the supplier to exert greater leverage in negotiations, potentially leading to less favorable terms for Gerresheimer. A supplier whose business is highly diversified across many clients would have less reason to concede to Gerresheimer's demands.
Consider the impact on specialized suppliers. If a supplier provides a unique component or raw material essential to Gerresheimer's production, and Gerresheimer is their primary or sole customer for that item, the dynamic shifts. In such cases, Gerresheimer might hold more sway due to the supplier's reliance on their specific order volume. However, if Gerresheimer is a small player for that specialized supplier, the supplier's power increases.
The bargaining power of suppliers for Gerresheimer is influenced by the concentration of providers for essential materials like specialized glass and polymers. In 2024, key players in the specialty glass sector, such as SCHOTT AG and Corning Incorporated, held significant market shares, indicating a concentrated supplier base for high-specification inputs. This concentration grants these suppliers considerable leverage in dictating pricing and supply conditions.
High switching costs, including extensive requalification processes and regulatory approvals, limit Gerresheimer's ability to negotiate aggressively with established suppliers. For critical components in pharmaceutical packaging, changing suppliers is a lengthy and costly endeavor, often requiring complete re-validation of final products due to stringent industry standards.
Suppliers of highly specialized or proprietary components, especially for advanced drug delivery devices, wield significant influence. This reliance on unique, patented materials from a sole provider can lead to strong interdependencies, necessitating close collaboration between Gerresheimer's R&D and its key suppliers.
The threat of supplier forward integration is generally low for highly specialized pharmaceutical packaging due to regulatory complexity, but suppliers of more standard components may pose a greater risk by integrating into finished product manufacturing to capture more of the value chain, a trend observed in 2024.
A supplier's dependence on Gerresheimer for a substantial portion of its revenue strengthens Gerresheimer's negotiating position. Conversely, if Gerresheimer represents only a minor portion of a supplier's revenue, the supplier's bargaining power is amplified, potentially leading to less favorable terms.
| Factor | Impact on Gerresheimer | 2024 Relevance |
|---|---|---|
| Supplier Concentration | High power for few specialized suppliers (e.g., glass, polymers) | Continued consolidation in pharmaceutical packaging materials |
| Switching Costs | High due to requalification and regulatory approvals | Significant barrier to changing suppliers for critical components |
| Component Specialization | High power for suppliers of proprietary/unique materials | Essential for advanced drug delivery devices, fostering interdependencies |
| Supplier Forward Integration | Low for specialized pharma packaging, higher for standard components | Suppliers increasingly interested in value-added services |
| Supplier Dependence on Gerresheimer | Low dependence increases supplier power; high dependence reduces it | Strategic importance of Gerresheimer's business can influence negotiation terms |
 Detailed Word Document
This analysis dissects Gerresheimer's competitive environment, detailing the intensity of rivalry, the bargaining power of suppliers and buyers, the threat of new entrants, and the impact of substitutes on its market position.

 Customizable Excel Spreadsheet
Instantly visualize competitive pressures with a dynamic Porter's Five Forces model, allowing Gerresheimer to quickly assess and navigate market dynamics.
The bargaining power of Gerresheimer's customers is considerable, largely because its key clients are major pharmaceutical, biotech, and cosmetics firms. These large companies often account for a significant share of Gerresheimer's revenue, granting them leverage to negotiate better pricing and terms. For instance, in 2023, Gerresheimer reported that its top customers represented a substantial portion of its sales, highlighting the importance of these relationships.
Switching costs for Gerresheimer's customers are notably high, acting as a significant deterrent to seeking alternative suppliers. These costs encompass rigorous regulatory requalification, extensive validation procedures, and the potential for significant disruption to their established drug manufacturing processes. For instance, a pharmaceutical company switching packaging providers might face a multi-month requalification period, impacting production timelines and incurring substantial testing expenses.
Customers' price sensitivity is a significant driver of bargaining power, particularly for Gerresheimer's high-volume, standard packaging products where product differentiation is minimal. For instance, in 2024, the pharmaceutical industry continued its focus on cost containment, with many major drug manufacturers actively seeking price reductions from their packaging suppliers to offset rising R&D and manufacturing expenses. This pressure is amplified when customers can easily switch between suppliers offering similar standard solutions.
However, this sensitivity diminishes considerably for highly specialized or innovative drug delivery systems. In these segments, pharmaceutical clients prioritize performance, reliability, and the unique capabilities of the packaging, rather than solely focusing on the lowest price. For example, advanced insulin pens or complex inhaler components often command premium pricing due to their critical role in patient adherence and therapeutic outcomes, making price a secondary consideration compared to the technology's efficacy.
The threat of customers backward integrating into manufacturing their own packaging or drug delivery components is generally low for specialized providers like Gerresheimer. While large pharmaceutical firms possess the financial clout, the immense capital outlay and specialized technical know-how for producing complex items like precisely engineered vials or advanced inhalation devices present substantial barriers. For instance, the global pharmaceutical packaging market, valued at approximately $116.3 billion in 2023, demands highly specific manufacturing capabilities and adherence to stringent regulatory standards, such as those from the FDA and EMA, which are difficult and costly for end-users to replicate internally.
The significant investment required for state-of-the-art manufacturing facilities, coupled with the need for deep expertise in materials science, precision engineering, and regulatory compliance, makes backward integration an economically unviable strategy for most customers. Gerresheimer's focus on highly specialized, often patented, product lines further diminishes this threat. The company’s 2023 revenue of €1.54 billion reflects its position as a key supplier in a niche market where its proprietary technologies and established quality systems are difficult to substitute.
Gerresheimer's focus on product differentiation significantly curbs customer bargaining power. By offering innovative drug delivery devices and high-quality specialty glass, the company creates unique value. For instance, their advanced insulin pens and inhalers, which boast features like precise dosage delivery and improved patient compliance, command a premium and reduce price sensitivity among pharmaceutical clients. This emphasis on innovation and quality means customers are less likely to switch to competitors based solely on price.
The value proposition extends beyond the product itself to include specialized services and a commitment to quality and safety. Pharmaceutical companies rely on Gerresheimer for solutions that meet stringent regulatory requirements and enhance patient outcomes. This deep integration into customer supply chains, particularly for critical drug delivery systems, further solidifies Gerresheimer's position.
Gerresheimer's customers, primarily large pharmaceutical and biotech firms, possess considerable bargaining power due to their significant purchase volumes and the high switching costs involved in changing suppliers for specialized packaging and drug delivery systems. While price sensitivity is a factor for standard products, it lessens for innovative solutions where performance and reliability are paramount.
The threat of customers backward integrating is low, given the substantial capital investment, technical expertise, and regulatory compliance required. Gerresheimer's focus on product differentiation through innovation in drug delivery devices and high-quality specialty glass further mitigates customer leverage, as these specialized offerings create unique value and reduce price-based decision-making.
| Factor | Impact on Gerresheimer's Customer Bargaining Power | Supporting Data/Reasoning |
|---|---|---|
| Customer Concentration | High | Major pharmaceutical clients represent a significant portion of Gerresheimer's revenue, granting them leverage. |
| Switching Costs | Low | High costs associated with regulatory requalification, validation, and production disruption deter customers from switching. |
| Price Sensitivity | Moderate (for standard products) to Low (for specialized products) | Cost containment efforts in 2024 increase sensitivity for standard items, but innovation in drug delivery systems reduces it. |
| Threat of Backward Integration | Low | Immense capital, technical expertise, and regulatory hurdles make internal production unviable for most customers. The global pharmaceutical packaging market's complexity, demanding specialized capabilities, reinforces this. |
| Product Differentiation | Reduces Power | Innovative drug delivery devices and high-quality specialty glass offer unique value, lessening price-based negotiations. Gerresheimer's R&D in areas like autoinjectors in 2024 highlights this strategy. |
This preview showcases the complete Gerresheimer Porter's Five Forces Analysis, offering a detailed examination of competitive forces within the industry. The document you see here is the exact, professionally formatted analysis you will receive immediately upon purchase, ensuring no discrepancies or missing information.
Gerresheimer operates in a market with a significant number of competitors, ranging from large, global pharmaceutical packaging and drug delivery device manufacturers to smaller, specialized companies. This diverse competitive set means rivalry is consistently high across various product categories.
The presence of both broad-portfolio giants and niche players intensifies competition as companies vie for market share. For instance, in 2024, major players like Amcor and Berry Global continue to hold substantial market positions, alongside specialized firms focusing on areas like advanced drug delivery systems.
Competitors actively compete on factors such as innovation, product quality, regulatory compliance, and pricing. This dynamic environment necessitates continuous investment in research and development to maintain a competitive edge, particularly in the evolving drug delivery device sector.
The pharmaceutical and biotech sectors generally show consistent growth, especially in advanced areas like biologics and injectables. However, specific segments within the packaging market can see quite different growth trajectories. When mature packaging segments experience slower expansion, competition can heat up significantly as companies battle for existing market share rather than benefiting from overall market growth.
This dynamic intensifies rivalry among packaging providers. Companies like Gerresheimer strategically focus on high-growth segments within the pharmaceutical packaging market, such as specialized vials and pre-filled syringes, to navigate these varying growth rates and reduce the pressure from slower-growing areas. For example, the global pharmaceutical packaging market was valued at approximately USD 112.5 billion in 2023 and is projected to grow at a compound annual growth rate (CAGR) of around 5.5% through 2030, with biologics packaging being a key driver.
Product differentiation plays a crucial role in the competitive landscape for companies like Gerresheimer. Rivalry isn't solely about offering the lowest price; it extends to innovation in areas like drug delivery systems and the quality of specialty glass. Companies actively differentiate themselves through advanced features, stringent regulatory adherence, and supplementary services such as bespoke design and digital integration.
Gerresheimer's strategic focus on developing cutting-edge drug delivery devices and high-quality specialty glass is a clear attempt to stand out from competitors. This differentiation strategy aims to foster customer loyalty and reduce the pressure of competing purely on cost, allowing them to command premium pricing for their specialized offerings.
High exit barriers, such as specialized assets and substantial investments in manufacturing facilities, can significantly increase competitive rivalry within the packaging industry. Companies like Gerresheimer, with their extensive capital expenditures in glass and plastic production, face considerable costs if they decide to exit. This can trap firms in the market, forcing them to continue competing even when profitability is low, potentially leading to price wars and overcapacity.
For instance, the specialized nature of pharmaceutical glass vial production requires highly specific machinery and quality control processes. Exiting this segment would mean these assets would have limited alternative uses, amplifying the financial penalty for leaving. Gerresheimer's diversified product portfolio, however, offers a degree of flexibility, allowing it to shift resources and focus on more profitable segments, thereby mitigating the impact of high exit barriers in any single market.
The strategic stakes in the glass and plastic packaging industry are exceptionally high, compelling companies like Gerresheimer to consistently invest heavily in research and development and expand their production capacities. This drive for innovation and scale is a direct response to the intense competition and the critical nature of their products for sectors like pharmaceuticals and food.
Mergers and acquisitions are a frequent occurrence, serving as a primary tool for companies to broaden their product offerings, extend their global presence, and enhance their technological prowess. For instance, in 2024, the packaging sector continued to see consolidation, with significant deals aimed at achieving economies of scale and market dominance. This M&A activity directly influences competitive rivalry by creating larger, more formidable players that can exert greater market influence.
Competitive rivalry at Gerresheimer is intense due to a fragmented market with numerous global and specialized players. Companies like Amcor and Berry Global, major forces in 2024, compete fiercely on innovation, quality, and regulatory adherence. This necessitates continuous R&D investment, particularly in advanced drug delivery systems, to maintain market position.
The market's structure, with high exit barriers like specialized assets and long-term contracts, traps firms, intensifying rivalry and potentially leading to price wars. Gerresheimer's strategic focus on high-growth segments, such as pre-filled syringes, helps navigate these pressures.
Consolidation through mergers and acquisitions is a key trend, with significant deals in 2024 reshaping the competitive landscape by creating larger, more dominant entities. This M&A activity heightens the strategic stakes, driving further investment in R&D and capacity expansion.
| Key Competitor Activities | 2024 Focus Areas | Impact on Rivalry |
| Innovation in Drug Delivery | Advanced injectables, smart packaging | Drives differentiation, increases R&D spending |
| M&A Activity | Market share consolidation | Creates larger competitors, intensifies pressure on smaller players |
| Sustainability Initiatives | Eco-friendly materials, circular economy | New competitive dimension, requires investment |
The threat of substitutes for traditional pharmaceutical packaging materials like glass and plastic is relatively low, primarily due to stringent regulatory hurdles. While innovations in alternative polymers or composite materials are ongoing, their adoption is hampered by the extensive testing and approval processes required for materials that come into contact with pharmaceuticals. For instance, the pharmaceutical industry's reliance on established, validated materials means that any new entrant faces significant time and cost barriers, making widespread substitution a gradual and challenging prospect.
The threat of substitutes for drug delivery devices hinges on alternative administration routes and technologies. For instance, a breakthrough in oral drug formulations could diminish the demand for injectable devices, while advanced transdermal patches might replace certain inhalers.
Gerresheimer actively addresses this by pioneering innovation across a wide array of delivery methods. This strategic focus allows them to adapt to shifting medical practices and patient preferences, ensuring their product portfolio remains relevant and competitive in a dynamic market.
Technological advancements present a significant threat of substitutes for Gerresheimer. Rapid progress in areas like material science and biotechnology could spawn entirely new methods for packaging and delivering pharmaceuticals. For example, smart packaging with embedded sensors or novel non-invasive drug delivery systems could emerge as viable alternatives to traditional glass and plastic solutions.
These innovations could bypass conventional packaging entirely, impacting Gerresheimer's core business. The company's commitment to research and development, including its investment in areas like advanced glass formulations and sustainable materials, is crucial for anticipating and adapting to these evolving substitute threats.
The attractiveness of a substitute for Gerresheimer's products hinges on its performance benefits, cost-effectiveness, and how easily it can be adopted. For instance, if a new material offered significantly better drug delivery or was substantially cheaper without compromising quality, it would pose a greater threat.
In the pharmaceutical sector, where patient safety and efficacy are paramount, any substitute must demonstrate clear advantages. This includes meeting rigorous regulatory standards, which can take years and substantial investment. For example, a new type of primary packaging for injectables would need to undergo extensive testing for leachables and extractables, a process that can cost millions and delay market entry.
Changes in regulatory frameworks, such as those impacting environmental sustainability or patient safety, can significantly increase the threat of substitutes for Gerresheimer's products. For instance, stricter regulations on single-use plastics could drive demand for alternative, more sustainable packaging solutions, potentially eroding market share for traditional offerings. By 2024, the global push for circular economy principles has intensified, with many regions introducing or strengthening bans on certain packaging materials.
New clinical guidelines or evolving medical practices might also favor alternative delivery systems or packaging designs that offer enhanced functionality or patient convenience. This could lead to a shift away from established products if competitors can quickly adapt to these emerging standards. For example, advancements in drug delivery technology might necessitate new types of vials or pre-filled syringes that are not currently core to Gerresheimer's portfolio.
Gerresheimer actively monitors these evolving regulatory landscapes and clinical trends to proactively adapt its product development and manufacturing processes. This includes investing in research for biodegradable materials and exploring innovative device designs to meet future compliance requirements and capitalize on emerging market opportunities. The company's commitment to innovation is crucial in mitigating the threat posed by these potential shifts.
The threat of substitutes for Gerresheimer's pharmaceutical packaging and drug delivery systems is generally moderate to low, primarily due to the high regulatory barriers and the need for proven efficacy and safety in the healthcare sector. While advancements in material science and alternative delivery methods exist, their widespread adoption is constrained by rigorous validation processes and significant investment requirements for new materials. For instance, the pharmaceutical industry's reliance on established, validated materials means that any new entrant faces substantial time and cost hurdles, making rapid substitution a challenging prospect.
The key factors influencing the attractiveness of substitutes are performance superiority, cost-effectiveness, and ease of integration into existing pharmaceutical manufacturing processes. For example, a new packaging material would need to demonstrate enhanced drug stability or patient usability, alongside a competitive price point, to pose a significant threat. By 2024, the push for sustainable packaging is increasing the viability of certain biodegradable or recyclable materials, though their pharmaceutical-grade compliance remains a critical hurdle.
Technological shifts, such as novel drug delivery systems or smart packaging solutions, represent a more dynamic substitute threat. These innovations could potentially bypass traditional packaging entirely. Gerresheimer's commitment to R&D, including investments in advanced glass formulations and sustainable materials, is vital for anticipating and adapting to these evolving threats, ensuring their continued relevance in a changing market landscape.
The pharmaceutical packaging and drug delivery device sector demands significant capital for advanced manufacturing, specialized equipment, and sterile environments. These substantial upfront costs create a formidable barrier for new companies looking to enter the market, protecting established players like Gerresheimer.
Stringent regulatory hurdles, such as those imposed by the FDA and EMA for pharmaceutical-grade materials and devices, present a significant barrier to entry for new companies in the packaging sector. Gerresheimer, for instance, must adhere to these evolving standards, requiring substantial investment in quality management systems, validation, and extensive documentation.
These compliance requirements are not only time-consuming but also financially demanding, creating a substantial upfront cost for any potential competitor. For example, the cost of obtaining and maintaining certifications for medical-grade packaging can run into millions of dollars, deterring many smaller or less-capitalized entrants.
Gerresheimer's deep well of proprietary technology and its commitment to R&D create a formidable barrier for newcomers. Their expertise in material science, intricate product design, and advanced manufacturing processes, particularly for sophisticated drug delivery systems, demands substantial and ongoing investment. For instance, in 2023, Gerresheimer reported significant R&D expenditures, underscoring their continuous innovation drive, which new entrants would struggle to match.
Gerresheimer leverages deep, long-standing relationships with major pharmaceutical and biotech clients, often spanning decades. These partnerships are vital, underpinned by the critical need for supply chain reliability, unwavering quality, and joint product development initiatives.
Newcomers struggle to penetrate these entrenched networks, facing significant customer inertia and a reluctance to transition from trusted, proven suppliers. This loyalty acts as a substantial barrier.
Existing players in the glass and pharmaceutical packaging industry, like Gerresheimer, benefit from substantial economies of scale. This means they can produce goods at a lower cost per unit due to high production volumes, efficient procurement of raw materials, and optimized distribution networks. For instance, in 2023, Gerresheimer reported revenues of €1.86 billion, indicating a significant operational footprint that allows for cost efficiencies.
The experience curve further solidifies the advantage of incumbents. Over years of operation, companies like Gerresheimer have developed refined manufacturing processes and accumulated specialized knowledge, leading to increased efficiency and reduced production costs. This accumulated expertise is difficult for new entrants to replicate quickly.
New companies entering the market face a significant hurdle in matching these cost advantages.
The threat of new entrants in the pharmaceutical packaging and drug delivery device sector is considerably low for Gerresheimer. High capital requirements for advanced manufacturing and sterile environments, coupled with stringent regulatory compliance like FDA and EMA standards, create substantial upfront costs, often in the millions of dollars for certifications. Gerresheimer’s significant R&D investments in proprietary technology and deep-rooted client relationships further solidify its market position, making it difficult for new players to compete on innovation or access established supply chains.
Economies of scale achieved by incumbents like Gerresheimer, which reported €1.86 billion in revenue for 2023, allow for lower per-unit production costs. This, combined with the experience curve effect from refined manufacturing processes and accumulated expertise, presents a significant cost disadvantage for new entrants. The substantial switching costs and rigorous supplier qualification processes for pharmaceutical companies also favor established, trusted providers, acting as a strong deterrent to new market participants.


