
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
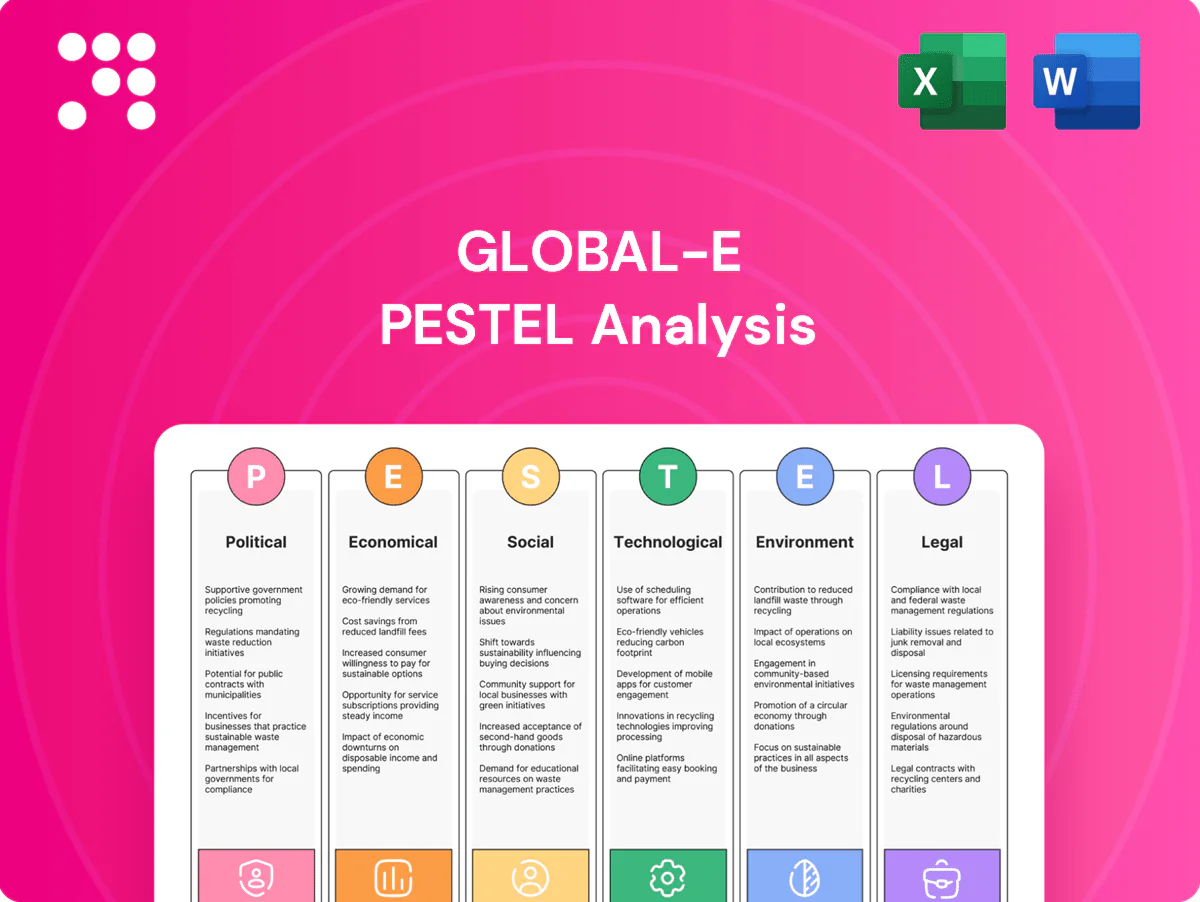
Gain strategic clarity with our PESTLE analysis of Global-e, revealing how political, economic and technological shifts shape cross-border e‑commerce. Ideal for investors, strategists and consultants, it translates macro trends into actionable risks and opportunities. Purchase the full report for the complete breakdown, editable charts and instant download.
Shifts in trade relations, sanctions and export controls—for example US-China tariffs covering roughly $360bn of goods—can immediately block merchant access to markets and specific SKUs. Tariff changes and customs duties raise landed costs and consumer prices, reducing conversion rates. Global-e, which serves merchants in over 200 markets, must dynamically adapt routing and compliance rules. Diversification across regions mitigates single-market shocks.
Variability in customs efficiency and rules across 200+ markets materially affects delivery SLAs and landed costs, driving longer transit times and higher exception fees. Political reforms can either streamline clearance or introduce new paperwork and delays. Global-e’s pre-calculation of duties and taxes must track frequent tariff and policy updates to remain accurate. Proactive communication reduces consumer disputes and cart abandonment, with unexpected costs cited by ~49% of shoppers as a top reason for checkout abandonment.
National pushes toward digital commerce expand Global-e’s addressable market—global e-commerce reached about $5.7 trillion in 2022, with continued growth into 2024. Conversely, new platform and data localization rules, including the EU Digital Markets and Services Acts effective 2024, add compliance and operational complexity. Aligning to local payment rails and government ID programs improves authorization and policy monitoring informs market-entry sequencing.
Brexit (UK exit finalized Jan 31 2020; new trade rules from Jan 1 2021) created divergent VAT and customs regimes as the UK left the EU Customs Union; the UK standard VAT rate remains 20% and the EU implemented the VAT e-commerce package on July 1, 2021. Global-e must maintain parallel rule sets, documentation templates and proactive merchant education to avoid cross-border compliance gaps.
Political stability drives investment in logistics, broadband and postal networks that underpin cross-border delivery; ITU reported about 67% global internet penetration in 2023, supporting e-commerce growth (Statista estimates global retail e-commerce ~6.3 trillion USD in 2024). Instability raises disruption and currency-control risks; scenario planning, rerouting and carrier reallocation plus insurance and contingency inventory preserve service levels.
Political shifts—tariffs (US-China ~$360bn), sanctions, data localization and platform rules (EU DMA/DSA 2024) materially alter market access, costs and compliance for Global-e (200+ markets). Customs variability and VAT reforms (EU e‑commerce VAT Jul 2021; UK VAT 20%) drive landed-cost volatility; e‑commerce reached ~$6.3trn in 2024, enlarging opportunity but raising regulatory burden.
| Indicator | Value/Year |
|---|---|
| Markets served | 200+ |
| Global e‑commerce | $6.3trn (2024) |
| US‑China tariffs | ~$360bn |
| EU VAT reform | Jul 2021 |
 Detailed Word Document
Explores how macro-environmental factors uniquely affect Global-e across Political, Economic, Social, Technological, Environmental and Legal dimensions, with data-backed trends and actionable, forward-looking insights. Designed to support executives, investors and strategists in scenario planning and opportunity/risk mitigation.

 Customizable Excel Spreadsheet
A concise, visually segmented Global‑e PESTLE summary that’s easily dropped into presentations, editable with contextual notes, and shareable across teams to streamline risk discussions, client reports, and strategic planning.
Inflation (US CPI ~3.4% in 2024) and unemployment (US ~3.7% 2024) squeezed real wages, reducing discretionary online spend and extending purchase decision cycles. Downturns push shoppers to promotions and BNPL; Global-e can protect conversions by optimizing dynamic pricing, upfront duties/taxes display and localized financing. Category mix matters: essentials consistently outperformed discretionary during weak cycles, preserving AOV and repeat rates.
Currency swings alter perceived prices and squeeze merchant margins; BIS data shows global FX turnover at about $7.5 trillion/day (2022), underlining scale of exposure. Transparent, localized pricing with hedging options and real-time FX plus rounding logic reduces checkout shock and lifts conversion. In volatile corridors merchants commonly add margin buffers to protect profitability.
Carrier base rates plus fuel surcharges—often 8–12% in 2024—plus peak-season uplifts (commonly 20–30%) materially raise total landed cost. Efficient carrier selection and label optimization can shave several percentage points off margins. Multi-node fulfillment and DDP reduce duty surprises and can lower return rates by ~15–25%. Performance SLAs should flex with seasonal capacity to avoid cost spikes.
Local tender availability and issuer behavior are primary drivers of approval; economic stress in 2023–24 correlated with higher fraud and chargebacks, squeezing authorization rates and margins. Offering wallets, BNPL and local alternatives materially expands reach, while intelligent retries and network tokenization have been shown to lift success rates by double digits in many merchant case studies.
Structural growth in cross-border e-commerce persists as merchants chase incremental demand abroad; cross-border now represents roughly 25% of global e-commerce and has been growing near a 10% CAGR through 2024. Penetration varies regionally, with mobile-led markets like Southeast Asia seeing >70% of online transactions on mobile, so Global-e can prioritize high-growth APAC–EU and US–APAC corridors and fast-growing categories such as beauty and apparel. Partnerships with marketplaces and logistics providers can accelerate merchant onboarding at scale, improving time-to-revenue and GMV conversion.
Higher inflation and tight labor (US CPI ~3.4% 2024; unemployment ~3.7% 2024) cut real wages, shifting shoppers to promotions and BNPL and lengthening purchase cycles, pressuring AOV. FX volatility (FX turnover ~$7.5T/day) and carrier fuel/peak surcharges (8–12% / peak +20–30% 2024) raise landed costs and margin risk. Cross-border growth (~25% share; ~10% CAGR through 2024) keeps upside if pricing, localized payments and DDP are optimized.
| Metric | Value |
|---|---|
| US CPI 2024 | ~3.4% |
| US Unemployment 2024 | ~3.7% |
| FX turnover | ~$7.5T/day (2022) |
| Cross-border share | ~25% (10% CAGR) |
This Global-e PESTLE Analysis preview is the exact, fully formatted document you’ll receive after purchase, with complete content, structure, and professional layout. No placeholders or teasers—what you see is the final file ready to download and use immediately.
Language, sizing, imagery and local holiday calendars materially shape conversion—localization can boost conversion rates by up to 40% in cross-border commerce. Local reviews and social proof significantly increase trust and purchase intent. Tailored checkout flows and culturally adapted copy reduce friction against a global cart abandonment average near 74% (Baymard Institute, 2024). A/B tests must reflect cultural nuances, not just translation.
Shoppers now expect upfront duties/taxes and precise delivery windows, with surveys reporting roughly 74% of consumers abandoning purchases after seeing unexpected fees; easy, transparent returns materially affect cross-border conversion given return rates often rise to 20–30% for international orders. Providing landed cost guarantees has been shown to reduce disputes and chargebacks by around 30–40%, while local return hubs typically lift repeat rates and loyalty metrics by double-digit percentage points.
In 2024 mobile drove roughly 70% of global e-commerce traffic and about 55% of purchases in many markets, making fast, simplified checkout flows and local wallets essential for conversion. Lightweight pages and one-tap pay have been shown to raise completion rates by around 20–30% versus multi-step checkouts. SMS and WhatsApp transactional messages deliver open rates near 90–98%, improving post-purchase engagement and LTV.
Discovery now often starts on social platforms, with global social commerce GMV projected at about $1.2 trillion by 2025 (Statista 2024), and influencer-driven purchases lifting impulse buys via seamless deep links into localized checkout flows. Creator-specific promo mechanics demand reliable attribution, routing and revenue-split capabilities, while region-specific endorsement rules (FTC, ASA, EU rules) must be embedded into seller onboarding and checkout.
Sustainability-conscious consumers increasingly weigh carbon footprint and packaging waste in purchase choices; 68% of global shoppers reported this influenced buying in 2024, pushing demand for greener logistics. Global-e can offer green shipping options, consolidated deliveries and returns-reduction tools to cut emissions and costs. Clear sustainability badges and disclosures—linked to verified carbon metrics—boost conversion and brand trust.
Localization (language, sizing, imagery) can lift cross-border conversion up to 40%, while global cart abandonment hovers near 74% (Baymard 2024). Mobile drives ~70% of e‑commerce traffic and social commerce GMV is ~ $1.2T by 2025 (Statista 2024). 68% of shoppers weigh sustainability; landed-cost transparency cuts disputes ~30–40% and boosts trust.
| Metric | Stat | Impact |
|---|---|---|
| Localization | +40% conv. | Higher sales |
| Cart abandonment | ~74% | Checkout focus |
| Mobile traffic | ~70% | Mobile UX |
| Social GMV | $1.2T (2025) | Creator commerce |
| Sustainability | 68% | Eco options |
Global-e must sustain near-100% availability—industry target of 99.99% SLA—across peak events and regions to protect cross-border revenue. Multi-cloud deployments with CDN and edge compute can cut latency by roughly 50%, improving conversion and AOV. Continuous observability plus chaos testing measurably harden reliability and reduce MTTR, while auto-scaling handles flash sales without degradation.
Intelligent routing across 300+ PSPs and APMs can lift cross-border checkout conversion about 20%, supporting Global-e’s revenue per shopper gains. Adaptive risk scoring with SCA orchestration cuts fraud losses up to 40% while lowering false declines. Device fingerprinting and behavioral analytics boost approvals ~15%; tokenization and network updates sustain ~99.99% payment uptime.
ML-driven localization tailors currency rounding, offers and content per market, supporting McKinsey findings that personalization can boost revenues roughly 10–15%; dynamic duty/tax estimation reduces surprise costs that drive cart abandonment (Baymard global rate ~69.8%). Predictive ETAs and carrier selection use analytics to cut delivery failures and improve on‑time rates. Continuous learning iteratively lifts conversion rates as models retrain on behavioral data.
Data security and privacy-by-design are table stakes for Global-e: end-to-end encryption, vaulting, and least-privilege access are core controls, supported by regular pen tests and compliance attestations that reassure enterprise merchants; IBM 2024 reports average breach cost at 4.45 million USD, while over 130 jurisdictions had data protection laws by 2024.
Global-e must deliver ~99.99% availability across regions; multi-cloud/CDN halves latency, lifting conversion and AOV. Intelligent routing across 300+ PSPs and adaptive SCA can raise checkout conversion ~20% and cut fraud losses up to 40%. ML localization increases revenues 10–15% and reduces Baymard 69.8% cart-abandon drivers; data breach avg cost $4.45M (IBM 2024).
| Metric | Value | Source |
|---|---|---|
| Availability target | 99.99% SLA | Industry |
| PSP integrations | 300+ | Global-e |
| Avg breach cost | $4.45M | IBM 2024 |
Compliance with GDPR (fines up to 4% of global turnover or €20m) and CCPA/CPRA (statutory penalties, including up to $7,500 per violation) is mandatory for Global-e’s cross‑border commerce. Robust consent management, DSR handling and lawful cross‑border transfers are operational musts. Clear data processing agreements must define controller/processor roles and safeguards, while privacy impact assessments measurably reduce regulatory risk.
Strong Customer Authentication under PSD2 (RTS effective 2019, phased enforcement through 2021–22) changed EU checkout flows by mandating SCA for most card-not-present payments, pushing adoption of 3-D Secure 2. 3DS optimization and regulated exemption streams (transaction risk analysis, low-value, recurring) balance fraud risk and friction. Licensing, PCI DSS v4.0 (published 2022, transition ended 31-Mar-2024) and local money-transmission rules demand compliance oversight. Country-specific payment rules and schemes must be encoded into routing and tax logic.
EU IOSS (since 1 July 2021) and UK VAT changes (from 1 Jan 2021) together with removal of de minimis mean tax collection point and liability shifted to sellers/platforms or importers, making virtually all low‑value imports VAT liable. Accurate HS codes and origin declarations are essential to determine duty/VAT and avoid customs holds. Choosing DDP versus DAP shifts cost, risk and last‑mile CX; DDP improves conversion but raises seller compliance. Continuous monitoring of rule updates is required to avoid fines and shipment blocks.
Cooling-off periods (EU standard 14 days) and pricing transparency/warranty terms differ by jurisdiction, forcing Global-e to localize T&Cs and disclosures; unclear fees drive cart abandonment (Baymard Institute 69.57% rate, extra costs cited by 49%). Accessible multilingual customer service channels and compliance reduce disputes, while EU/US dark-pattern scrutiny reshapes UX design.
Screening of buyers, destinations, and products is necessary; Global-e must check US, EU and UN lists, noting the US administers over 30 sanctions programs and the OFAC SDN list exceeded 10,000 entries as of 2025. Dual-use and embargo rules (EU Dual-Use Regulation, US EAR) can bar shipments or require licenses. Automated denial lists and license management cut compliance risk, and ongoing monitoring captures list updates promptly.
Global-e must comply with GDPR (up to 4% global turnover or €20m), CCPA/CPRA, PSD2 SCA, PCI DSS v4.0 (transition ended 31‑Mar‑2024) and VAT/IOSS/UK import rules; localization of T&Cs, returns and UX prevents fines and cart abandonment. Sanctions screening (OFAC SDN >10,000 in 2025) and dual‑use controls require automated denial/license workflows. Continuous monitoring and DPA clarity reduce legal exposure.
| Issue | Metric/Date |
|---|---|
| GDPR fine | 4% turnover or €20m |
| Cart abandonment | 69.57% (extra costs 49%) |
| PCI v4.0 | Transition ended 31‑Mar‑2024 |
| OFAC SDN | >10,000 (2025) |
Longer cross-border distances and reliance on air freight raise emissions intensity—air cargo emits roughly 10–100 times more CO2 per ton-km than ocean shipping. Offering slower, greener delivery options (surface-first routing) can cut shipment emissions substantially. Selecting carriers with verified sustainability metrics improves efficiency, while carbon reporting helps merchants disclose Scope 3 supply-chain emissions, which typically account for ~80% of retail footprints.
Right-sizing, recyclable materials and elimination of void fill can cut packaging volume and costs while lowering waste; e-commerce return rates average 10–30% by sector, amplifying packaging impact. Regulatory pressure has risen since the EU PPWR proposal in 2023, with reuse and recycled-content targets toward 2030. Clear merchant guidance standardizes eco practices, and branded returns packaging should be reusable where feasible.
High online return rates — about 20–40% for fashion and ~15–20% overall e-commerce — raise transport emissions and landfill risk. Improved fit guidance, localized sizing charts and clear product data can shrink returns materially. Consolidated return hubs have cut transport emissions by up to ~30% in pilots. Refurbish/resell programs tap a resale market projected near $350 billion by 2030, boosting circularity.
Cloud workloads drive Scope 2 emissions—data centers used ~1–1.5% of global electricity in 2023—and choosing providers with renewable targets (AWS, Google, Microsoft: 2025–2030 commitments) materially lowers Global-e’s footprint; efficient architectures, caching and CDNs can cut compute energy by 30–50%, and Scope 2 reporting aligns with TCFD/ISSB and EU CSRD disclosure timelines.
EPR, plastic taxes and emissions levies materially raise per-order costs and drive lighter or recyclable packaging choices; the EU non-recycled plastic levy of €0.80/kg and EU carbon prices near €90/tonne (mid-2025) directly affect cross-border fulfillment costs and SKU decisions. Regional variance demands configurable market settings and proactive compliance to avoid fines and reputational damage, while merchant education speeds rule adoption.
Cross-border air freight raises emissions (air 10–100x ocean per ton-km); Scope 3 often ~80% of retail footprints so carbon reporting is critical. Returns (10–40%) and packaging drive waste; resale market forecast ~$350B by 2030. Data centers ~1–1.5% global electricity (2023); cloud providers set 2025–2030 renewables targets. EU plastic levy €0.80/kg; carbon ~€90/t (mid-2025).
| Metric | Value |
|---|---|
| Air vs ocean CO2 | 10–100x |
| Scope 3 retail | ~80% |
| Returns | 10–40% |
| Data center electricity (2023) | 1–1.5% |
| EU plastic levy / carbon | €0.80/kg / ~€90/t |
| Resale market | $350B by 2030 |


