
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
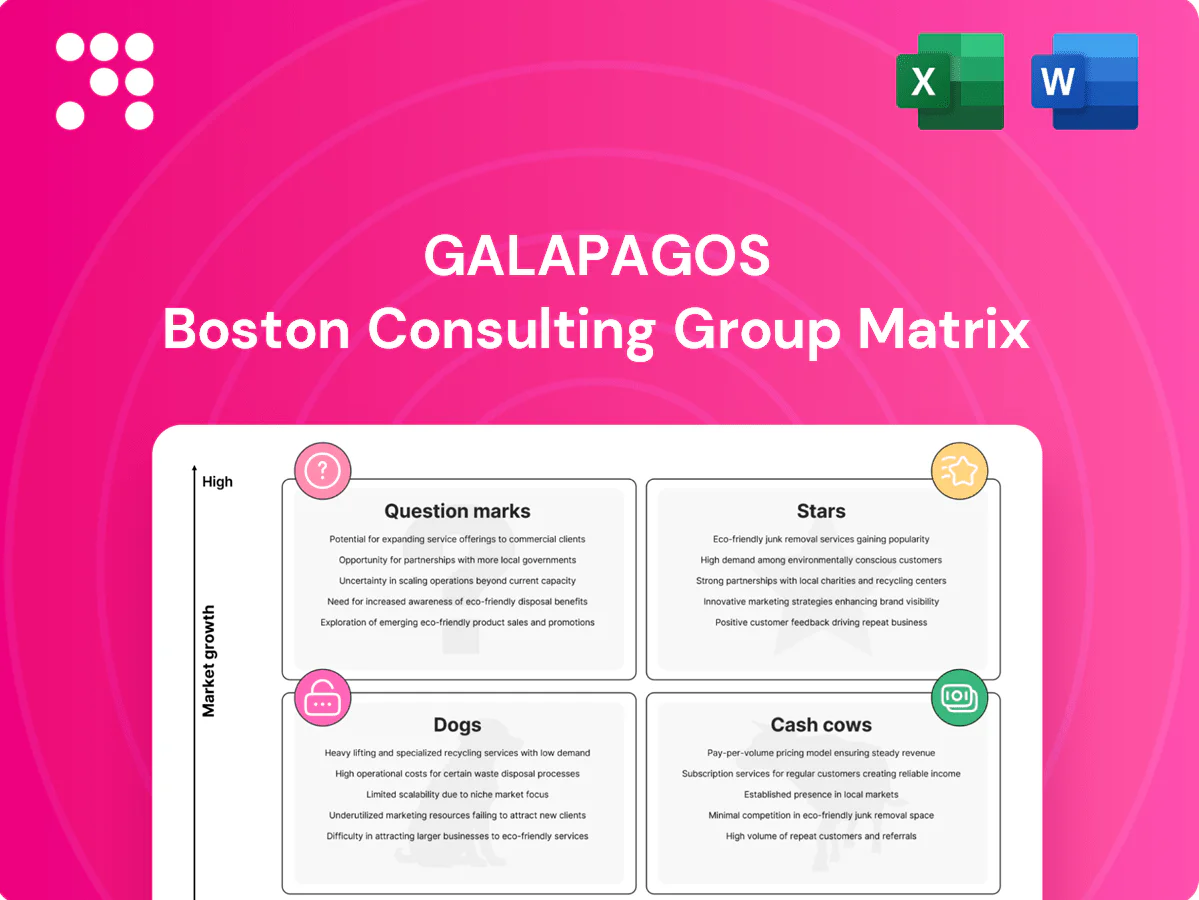
Think of this Galapagos BCG Matrix preview as a fast pulse check—where the portfolio's Stars, Cash Cows, Dogs, and Question Marks are hinted at but not fully mapped. Want the full picture? Purchase the complete BCG Matrix report for quadrant-by-quadrant placements, data-backed recommendations, and a ready-to-use Word report plus an Excel summary. It’s the shortcut to clear investment decisions and a strategic roadmap you can act on immediately.
Flagship inflammatory programs sit in a >$100B autoimmune market (2024 est.) growing ~6% CAGR, with accelerating adoption and improving payer openness; Galapagos is leveraging differentiated efficacy and a cleaner patient experience to build share.
The proprietary target discovery engine continually surfaces novel biology in high‑growth indications, feeding the pipeline with first‑in‑class shots and creating a flywheel where more data yields better targets and faster cycle times. It soaks up cash now but compounds learning and optionality; continued investment widens the moat and increases throughput, turning near-term spend into long‑term, differentiated pipeline value.
Late-stage assets in fibrosis/inflammation nearing pivotal readouts can capture outsized attention and market share; Phase III programs typically cost >$100M and positive data often drives 30–100% valuation uplifts. Clinician pull is strong when endpoints shift (fibrosis regression, event reduction). Burn is high from trials and manufacturing scale-up, consuming most near-term cash; execution can convert momentum into durable dominance.
Global filings and 2024 pricing wins in key growth indications demonstrate a repeatable path to scale, with faster launches delivering outsized early uptake and pricing power.
The regulatory and market-access capability is a multiplier of product performance; keep investing to compress time-to-revenue and protect early market share.
Strategic co-development and co-commercial alliances open doors to large markets and accelerate uptake; in 2024 global biotech licensing and co-commercial deal value reached about $180bn, underscoring partner-led scale. They provide promotion muscle and distribution without cloning the cost base; economics are shared but launch velocity rises, often shortening time-to-peak by quarters. Double down where partners measurably lift both awareness and access.
Flagship inflammatory programs target a >€100B autoimmune market (2024 est.) growing ~6% CAGR, with differentiated efficacy and cleaner patient experience driving share. Proprietary discovery fuels first‑in‑class pipeline, compounding optionality despite near‑term cash burn. Late‑stage fibrosis/inflammation assets nearing pivotal readouts can yield 30–100% valuation uplifts; 2024 revenue signal: €1.1bn.
| Metric | Value |
|---|---|
| Market (2024) | >€100B |
| Revenue (2024) | €1.1bn |
| CAGR | ~6% |
| Licensing value (2024) | $180bn |
 Detailed Word Document
Concise Galapagos BCG Matrix review: quadrant-by-quadrant strategic guidance on Stars, Cash Cows, Question Marks and Dogs.

 Customizable Excel Spreadsheet
One-page Galapagos BCG Matrix that clarifies portfolio pain points—quick insights for C-suite decisions and slide-ready export.
Mature therapies in steady indications deliver predictable cash, often with gross margins above 70% and marketing spend typically under 10% of sales, so promo is modest. Margins rise further from scale efficiencies and lifecycle tweaks, improving operating leverage by double-digit percentage points. Use cash-cow returns to fund next-wave R&D and acquisitions without starving growth bets, aiming to cover 30–50% of pipeline spend. Maintain share, avoid price erosion, milk smartly.
Royalty and milestone streams are Galapagos cash cows: 2024 filings show these legacy out‑licenses deliver steady, multi‑million euro inflows that exceed upkeep. Low opex and predictable timing give high conversion to free cash flow, ideal to bankroll trials and platform upgrades. Protect contracts, manage counterparty risk and litigation exposure to keep the drip flowing.
Galapagos manufacturing and CMC know-how anchors a cash cow: process IP and validated supply chains typically cut COGS by 10–25% and lift gross margins on mature assets, making outputs quietly powerful and reliably cash generative. Once built, upkeep costs are low versus benefit; modest incremental investment often raises yield and reliability by 5–15%.
IP portfolio with routine out-licensing delivers annuity-like income: non-core patents generate low-effort royalties (typical pharma royalty 5–15%) and occasional milestone payments (deal milestones often range from low single-digit to low triple-digit millions). Minimal upkeep spend, rare upside, stabilizes cash flow without driving breakout growth.
Optimize overhead, avoid bloat and sustain output so predictable free cash funds higher-beta R&D and BD investments; 2024 cost programs delivered double-digit percent reduction in recurring operating expenses vs prior year.
Mature therapies and royalties yield high-margin, predictable cash (gross margin >70%, marketing <10%), funding 30–50% of pipeline. 2024 royalty/milestone inflows are multi‑million euros with typical royalty rates 5–15%; low opex converts to free cash. SG&A cuts in 2024 drove double‑digit recurring cost reduction, extending cash runway to mid‑2027.
| Metric | 2024 Value |
|---|---|
| Gross margin | >70% |
| Marketing % of sales | <10% |
| Pipeline funding from cash cows | 30–50% |
| Royalties | 5–15% |
| SG&A reduction | Double‑digit % |
| Cash runway | Mid‑2027 |
The file you're previewing is the final Galapagos BCG Matrix you'll receive after purchase. No watermarks, no demo placeholders—just a fully formatted, ready-to-use strategic matrix tailored for product and portfolio clarity. This exact document will be available immediately to download and edit, perfect for presentations, board meetings, or investor materials. Designed by strategy experts, it requires no extra tweaks—what you see is what you get.
Programs chasing me-too targets in commoditized spaces burn time and capital. Industry-wide Phase I→approval success is about 9.6% (2011–2020) and early clinical programs commonly exceed $50m in spend, so share stays low and payers shrug. Turnarounds here rarely pay back, best to wind down or divest and reallocate to differentiated assets.
Markets where reimbursement stalls and uptake flatlines (often <10% penetration) trap resources: field teams drive costs while returns remain thin and post-approval sales CAGR hovers near 0%. Prolonged fixes—rebates, additional trials, local HTA engagements—cost more than incremental revenue, with reimbursement decisions commonly delayed >12 months. Trim exposure and refocus on receptive payers to redeploy capital into higher-growth geographies.
Legacy discovery tools now drag cycles and productivity, with maintenance consuming up to 70% of IT budgets while delivery speed lags modern platforms by as much as 30% in 2024 benchmarks. Maintenance costs creep year-over-year, yet actionable insights remain flat, turning retention into sentiment rather than strategy. Sunset and migrate to higher-yield tech to reclaim capacity and cut costs.
Ultra-niche indications with fragmented prescriber bases are costly to cover, often yielding peak market sizes below $100m and promotional ROI that rarely clears typical 8–12% hurdle rates; share is hard to build and growth is capped, making stand-alone commercialization unattractive. Exit or bundle with partners who already call on these prescribers to avoid sustained negative cash burn.
Programs with recurring safety or tolerability flags scare prescribers and payers, stalling uptake and growth. Confirmatory trials can add Phase 3 costs of $100–500M without fixing perception; cash gets stuck in limbo and valuation multiples compress. Cut losses and divest to protect portfolio credibility and redeploy capital.
Commoditized programs with low differentiation consume capital and rarely scale: industry Phase I→approval ~9.6% (2011–2020) and early clinical spend commonly >$50m, so market share stays small. Legacy IT drags productivity (maintenance up to 70% of IT budgets; delivery ~30% slower vs 2024 platforms). Exit, divest, or partner to redeploy into high-growth assets.
| Metric | Value |
|---|---|
| Market size | < $100m |
| Phase I→Approval | 9.6% |
| Early clinical spend | > $50m |
| IT maintenance | ≈70% |
| Delivery lag (2024) | ~30% |
First-in-class inflammation targets show high scientific promise but represent a low current share of Galapagos revenue; the global inflammation therapeutics market exceeded $100 billion in 2024 and is growing at roughly a 5%+ CAGR, making upside significant. Data remain early but intriguing, so push hard on translational proof and precision patient selection. If signals hold, these assets can flip to Star territory and materially re-rate the portfolio.
Fibrosis is a large, underserved market—fibrotic diseases affect an estimated >100 million patients globally and the antifibrotic market was valued at about $4.6 billion in 2024. Programs require decisive efficacy and clean safety to break out; development spend is front-loaded with median Phase II costs around $20–50 million and Phase III often exceeding $100 million. Go/no-go decisions must be early, then invest boldly if pivotal curves turn.
Next-gen cell/gene-modulating platforms offer multiple shots on goal but start from zero share; by 2024 there were over 2,000 CGT programs globally, underscoring opportunity and competition. Manufacturing, CMC and access are steep hills, with facility capex often exceeding $100m and per-patient therapy costs commonly >$300,000. Pilot in focused indications to learn fast and scale only after product-market fit is real.
Digital and AI-augmented target discovery accelerates hypothesis generation but commercial impact remains unproven; historical drug development success from Phase I to approval is ~10%, so higher hit quality is required to shift economics. Tooling and talent are nontrivial—median US ML engineer pay exceeded $140,000 in 2024—so tie outputs to clear stage-gates and predefined kill rates. If observed hit quality and downstream validation rates rise materially, the business unit can graduate to Star status.
New geographic launches and label expansions offer growth but typically start with market shares under 1% and high uncertainty; access, KOL momentum and real-world evidence drive the early adoption slope. Resource allocation must be tied to tight KPIs with 6–12 month readouts to decide ramp or redeploy capital; win fast or cut losses.
Question Marks: high upside but low current share—inflammation market >100B (2024) with 5%+ CAGR; fibrosis market ~4.6B (2024) with >100M patients; CGT programs >2,000 (2024) costly to scale; AI tools require higher hit rates vs ~10% Phase I→approval. Push fast translational readouts, tight stage-gates, scale only on clear pivotal signals.
| Asset | Market 2024 | Current share | Key metric |
|---|---|---|---|
| Inflammation | >100B | Low | 5%+ CAGR |
| Fibrosis | 4.6B | Low | >100M pts |
| CGT | — | 0 | 2,000+ programs |


