
Digital download
Access the files immediately after checkout.
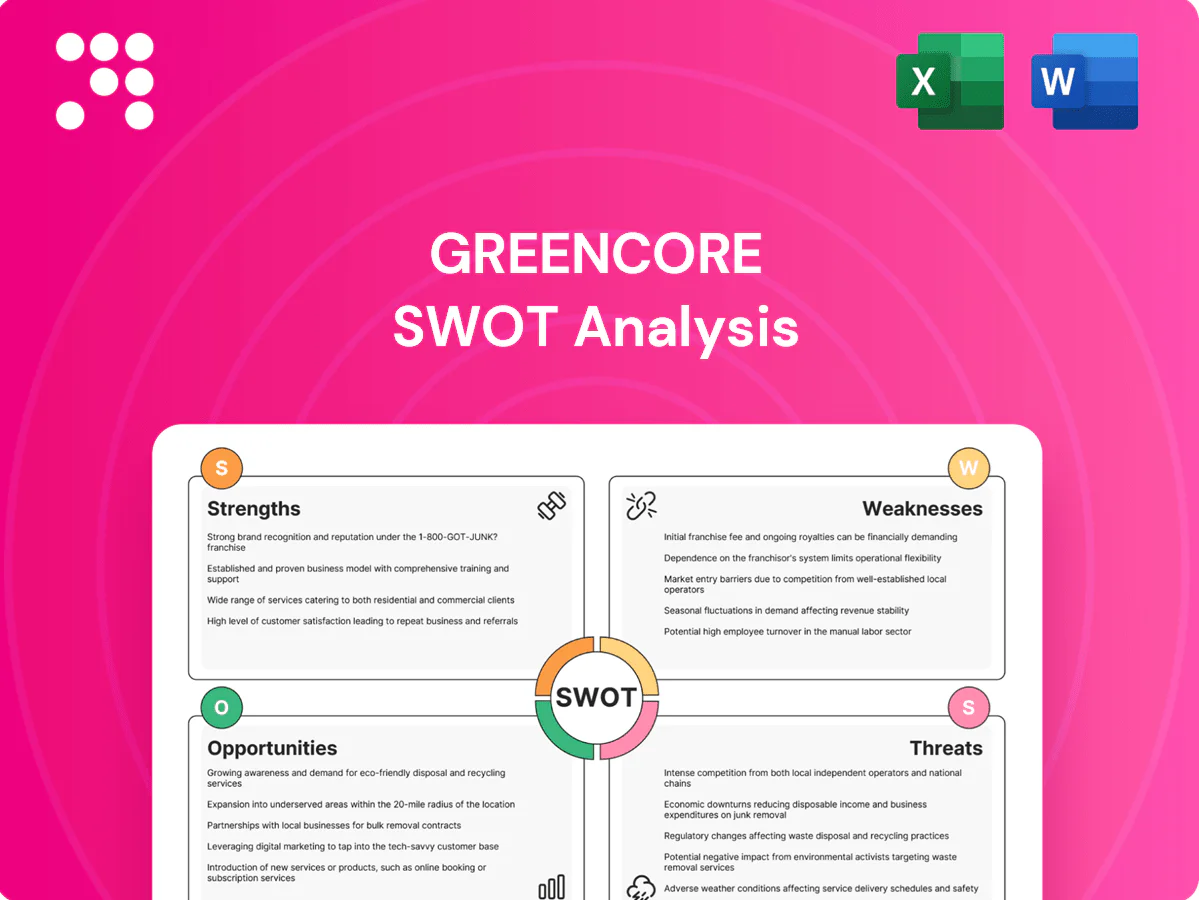
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Greencore's SWOT highlights resilient supply-chain strengths, strong UK convenience-food market share, margin pressure from commodity costs, and exposure to retail concentration and regulatory shifts. Want the full story on strengths, risks and growth levers? Purchase the complete SWOT for a research-backed, editable Word and Excel package to plan, pitch, or invest with confidence.
Greencore is a primary supplier to major UK and Irish supermarkets, embedding itself in category planning and replenishment cycles; the group generated over £1bn revenue in FY2024, giving high-volume visibility via longstanding contracts. These ties enable rapid listings for new lines and seasonal launches—often within weeks—and reliance on service levels reinforces switching costs for buyers.
High-throughput, quick-turnaround plants are optimized for short shelf-life categories (0–14 days), supporting c.£1bn revenue in FY24 and driving strong SKU velocity. Scale delivers procurement leverage and rapid changeovers across a broad SKU set, lowering unit costs and shrink. Centralized cold-chain logistics and waste-reduction processes improve on-shelf availability, a capability smaller rivals struggle to replicate.
Greencore's portfolio spans four core categories—sandwiches, salads, sushi and ready meals—balancing demand across breakfast, lunch and evening dayparts. This diversification smooths retailer orders and improves factory utilisation by spreading volume volatility across categories. Cross-category insight accelerates innovation and range resets and enables bundled supply solutions for key accounts.
Greencore excels in retailer own-brand development and rapid reformulations, delivering value, mid-tier and premium ranges under tight cost and quality controls; its private-label focus underpins stable baseline volumes and reduces exposure to branded SKU volatility. Co-development partnerships with major UK retailers strengthen buying alignment and shelf prominence.
Greencore's agile innovation cadence delivers rapid NPD cycles that align with trend-led convenience formats, using test-and-learn across meal occasions and dietary needs to keep ranges fresh and relevant; short lead times enable quick response to demand spikes and promotions while operational flexibility preserves speed without sacrificing regulatory and quality compliance.
Greencore is a primary supplier to major UK and Irish supermarkets, delivering over £1bn revenue in FY2024 and embedding into retailer planning to create switching costs. High-throughput plants optimise 0–14 day short shelf-life SKUs, enabling rapid listings and strong SKU velocity. Portfolio of sandwiches, salads, sushi and ready meals plus private-label focus and fast NPD sustain stable volumes and margin leverage.
| Metric | Value |
|---|---|
| FY2024 revenue | >£1bn |
| Core categories | Sandwiches, salads, sushi, ready meals |
| Shelf-life | 0–14 days |
 Detailed Word Document
Delivers a strategic overview of Greencore’s internal and external business factors, outlining strengths, weaknesses, opportunities and threats to inform competitive positioning and growth strategy.

 Customizable Excel Spreadsheet
Provides a concise Greencore SWOT matrix that relieves strategic uncertainty by enabling fast, visual alignment and quick edits to reflect changing market and supply‑chain priorities. Ideal for executives and teams needing a stakeholder‑ready snapshot for rapid decision‑making.
High customer concentration leaves Greencore exposed: top grocery retailers account for roughly 65% of volumes, and group revenue was about £1.26bn in FY 2024, so any delisting, tender loss or retailer strategy shift can materially cut volumes. Retailers hold negotiating leverage on price, and bespoke product specs limit switching to alternative suppliers.
Private-label manufacturing typically yields low single-digit operating margins, and Greencore—with revenues above £1bn—remains exposed to that structural pressure. Cost inflation or production inefficiencies can quickly erode profitability, since high fixed costs demand tight plant utilisation to sustain returns. Passing through ingredient and energy price rises to retailers often lags, compressing near-term margins further.
Greencore faces pronounced input cost exposure as volatile lines such as ingredients, packaging and energy feed directly into its fresh-prepared sandwich and convenience food business, which operates primarily in the UK and Ireland.
Short shelf-life products limit inventory buffering against spikes, meaning raw material or energy shocks translate quickly into margin pressure and working capital strain.
Hedging programs reduce but do not eliminate sudden price shocks, and frequent re-pricing risks retailer pushback and delays that can erode shelf-space and sales velocity.
Greencore’s focus on retailer own-label contracts undermines its consumer-facing brand equity, limiting pricing autonomy and product differentiation and leaving margins exposed to retailer negotiations. Dependence on buyer-led category strategies reduces the company’s ability to drive direct consumer demand, while marketing levers are largely mediated by retailer-promoted activity rather than Greencore-controlled campaigns. Greencore is listed on the London Stock Exchange (ticker GNC).
Chilled, high-mix production at Greencore elevates waste and downtime risk, with tight labour planning and logistics precision required to maintain service levels. Any disruption can cascade into service failures and penalties. Compliance burdens (food safety, packaging) add measurable cost and process rigidity. Greencore reported c.£1.24bn revenue in FY2024, amplifying exposure across sites.
High customer concentration (top retailers ≈65% of volumes) and dependence on private-label contracts limit pricing power and differentiation, compressing margins. Low single-digit operating margins across a £1.24bn FY2024 revenue base mean cost inflation and plant inefficiency rapidly erode profit. Short shelf-life and chilled, high-mix production raise waste, working-capital strain and disruption risk. Hedging cushions but cannot eliminate input-price shocks.
| Metric | Value |
|---|---|
| FY2024 revenue | £1.24bn |
| Top retailers share | ≈65% volumes |
| Operating margin | Low single-digit |
| Product risk | Short shelf-life; chilled/high-mix |
This is a real excerpt from the complete Greencore SWOT analysis you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report and reflects the same structure, findings, and recommendations. Buy now to unlock the full, editable document for immediate use.
Return-to-office, travel and event recovery is driving sandwich and snack demand as IGD valued the UK food-to-go market at c.£10bn in 2024 and ONS data showed workplace attendance recovered to about 70% of pre-COVID levels by 2024; retailers are expanding food-to-go fixtures, creating missions Greencore can win on freshness, availability and multi-tier value ranges; seasonal and occasion-led NPD can capture incremental trips and uplift sales.
Rising demand for high-protein, plant-forward and clean-label options lets Greencore, with group revenue of over £1bn, push premium ready meals and sushi to lift mix and margin. Reformulation to meet HFSS and 2024 nutrition targets secures shelf space and reduces promotional risk. Clear provenance and allergen transparency strengthen retailer trust and repeat purchase in a quality-driven market.
Investments in robotics, vision systems and automated packing can cut labor intensity and industry studies report labor cost reductions of 20–30% and food waste declines of 10–20%. AI-driven demand forecasting has reduced stockouts and promo overstocks in pilots by around 10–15%, improving yield and promo ROI. Digital quality and traceability tools speed audits and recall response times, and combined efficiency gains can materially offset margin pressure.
Sustainable packaging leadership—reducing plastics, boosting recyclability and light-weighting—aligns closely with major UK and international retailer ESG targets and can differentiate Greencore in tenders. Material reduction lowers input costs and Scope 3 emissions while transparent reporting supports preferred-supplier status and tender wins.
Targeted bolt-on M&A can add capacity, new cuisines and capabilities, accelerating Greencore’s growth off its c.£1.1bn FY2024 revenue base; consolidation strengthens bargaining power and network density, lowering input costs. Cross-selling into existing accounts shortens payback and synergies emerge in procurement, logistics and overhead, supporting margin expansion.
Return-to-office and a £10bn UK food-to-go market (IGD 2024) and c.70% workplace attendance (ONS 2024) boost sandwich/snack demand; Greencore (c.£1.1bn FY2024) can win on freshness and NPD. Premium, plant-forward and HFSS reformulation lift mix and secure shelf space. Automation/AI (20–30% labor cut; 10–15% fewer stockouts) and sustainable packaging drive margin and tender wins.
| Opportunity | Metric | Impact |
|---|---|---|
| Food-to-go growth | £10bn market, 70% RTO | Sales uplift |
| Automation/AI | 20–30% labor, 10–15% stockout | Margin+ |
| Bolt-on M&A | 5–8x EBITDA, 2–4yr payback | Scale/synergies |
Grocers including Tesco and Sainsbury's aggressively defend value propositions, forcing suppliers like Greencore into tendering and dual-sourcing that compress margins. Delayed cost pass-through amid rising input prices has periodically squeezed profits. Discounters Aldi and Lidl grew to about 18% UK grocery share in 2024 (Kantar), intensifying private-label price wars during consumer downtrades.
Spikes in proteins, fresh produce, grains and utilities remain abrupt and recurring, with the FAO Food Price Index ~10% below its 2022 peak but still elevated versus pre‑pandemic levels. Hedging only partially offsets mismatches in volume and timing, leaving margins exposed. Volatility complicates pricing and promotional calendars and extended spikes can trigger contract repricing disputes, straining customer relationships and working capital.
Tight labour markets are raising costs and turnover for Greencore, with UK vacancies near 1.0m in 2023–24 (ONS) driving wage pressure; sector regular pay growth ran at about 6% in 2023, squeezing margins. Skills gaps are reducing throughput and quality in food manufacturing, while immigration and policy shifts (post‑Brexit controls) constrain labour supply. Without productivity gains to offset higher wages, margin compression is likely to continue.
Stricter standards including England’s HFSS restrictions (effective October 2022) and new labeling rules raise formulation and merchandising costs for Greencore, while the UK Plastic Packaging Tax (£200/tonne since April 2022) adds packaging expense. Any food-safety incident could force costly recalls, reputational damage and potential loss of BRC/Safe Quality Food accreditations; compliance failures risk regulatory fines. Evolving sustainability mandates require continuous CAPEX and OPEX.
Weather extremes cut crop yields and quality—FAO's Food Price Index peaked at 159.7 in 2022, reflecting climate-driven shocks. Logistics bottlenecks and cold-chain failures raise spoilage risk for Greencore's perishable ready meals, amplifying waste (WRAP: UK food waste 9.5m tonnes, 2018). Geopolitical shocks since 2022 have disrupted wheat and sunflower oil export flows.
Retailer price pressure (Aldi/Lidl ~18% share 2024, Kantar) and grocer tendering compress margins; delayed cost pass-through amid input spikes (FAO FPI ~10% below 2022 peak of 159.7) increases risk. Labour tightness (UK vacancies ~1.0m 2023–24, ONS) and wage inflation (~6% sector pay growth 2023) raise costs. Regulation (HFSS, Packaging Tax £200/t) and climate/logistics shocks elevate compliance, recall and waste risks.
| Threat | Key metric |
|---|---|
| Discounters | Aldi/Lidl ~18% (2024) |
| Input volatility | FAO FPI 2022 peak 159.7 (-~10%) |
| Labour | Vacancies ~1.0m (2023–24) |
| Regulation | Packaging Tax £200/tonne |


