
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Green Cross Health navigates a complex landscape shaped by powerful buyer bargaining, intense rivalry, and the ever-present threat of new entrants. Understanding these forces is crucial for any stakeholder looking to grasp their competitive position.
The complete report reveals the real forces shaping Green Cross Health’s industry—from supplier influence to threat of new entrants. Gain actionable insights to drive smarter decision-making.
The pharmaceutical sector, particularly for patented and essential drugs, frequently sees a few major manufacturers holding sway. This concentration empowers these suppliers, giving them considerable leverage over healthcare entities such as Green Cross Health, which depend on a steady availability of diverse medications.
While Green Cross Health's substantial purchasing power can provide some counterbalance, its ability to negotiate is constrained when dealing with critical medicines where switching suppliers or finding alternatives may be difficult or costly.
The New Zealand healthcare landscape, including Green Cross Health's operational areas, is grappling with persistent shortages of essential professionals like pharmacists, doctors, and nurses. This scarcity significantly bolsters the bargaining power of these skilled individuals, who are critical labor suppliers. They can leverage this position to negotiate for improved remuneration and more favorable working conditions.
Consequently, Green Cross Health faces intensified competition for acquiring and retaining talent. This competition directly influences the company's operational expenditures and its capacity to deliver services effectively across its diverse pharmacy, medical center, and community health segments. For instance, in 2024, the nursing shortage in New Zealand was estimated to be around 5,000 full-time equivalents, a figure that underscores the pressure on healthcare providers.
Suppliers of specialized medical equipment, diagnostic tools, and essential healthcare IT systems often operate in niche markets with limited competition. This scarcity grants them significant leverage. For instance, the global medical devices market was valued at approximately USD 520 billion in 2023 and is projected to grow, indicating the substantial investment required for these specialized technologies.
These suppliers hold considerable power due to the high cost of equipment, the necessity for specialized maintenance, and the complexities involved in integrating new systems. Switching providers can be prohibitively expensive and disruptive, further solidifying the suppliers' strong position. This dependence means Green Cross Health is susceptible to supplier-driven price increases and terms.
The global nature of pharmaceutical and medical supply chains significantly impacts Green Cross Health's bargaining power with its suppliers. Disruptions from international events, geopolitical tensions, or raw material shortages can leave the company vulnerable to price hikes and limited sourcing options domestically. For instance, in 2023, the global pharmaceutical industry faced increased input costs, with some raw material prices rising by as much as 15-20% due to supply chain bottlenecks. This reliance on external factors can amplify supplier leverage.
Managing these risks is crucial for Green Cross Health. Developing robust supply chain strategies and exploring diversified sourcing options, where feasible, can help mitigate the impact of increased supplier power. A 2024 report by McKinsey indicated that companies with diversified supply chains experienced 50% less revenue loss during periods of disruption compared to those with concentrated sourcing. This highlights the strategic importance of building resilience against supplier influence.
For the non-pharmaceutical retail products, Green Cross Health faces a more fragmented supplier landscape. This includes items like cosmetics, health supplements, and various general merchandise. The company's substantial retail presence, encompassing its Unichem and Life Pharmacy stores, grants it considerable leverage. This leverage stems from the sheer volume of goods purchased and the direct access to a broad consumer market, enabling more advantageous negotiations on terms and pricing.
This strong position allows Green Cross Health to secure favorable purchasing agreements. For instance, in the 2024 financial year, the company reported a significant portion of its revenue derived from retail sales, indicating the scale of its supplier interactions. While major brands still possess some influence, Green Cross Health's purchasing power often tips the scales in its favor, leading to better cost efficiencies and product availability.
The bargaining power of suppliers is a critical factor for Green Cross Health, especially concerning essential medicines and specialized medical equipment. In these areas, a concentrated supplier base and high switching costs significantly empower suppliers, leading to potential price pressures and limited negotiation flexibility for Green Cross Health.
For non-pharmaceutical retail goods, Green Cross Health benefits from a more fragmented supplier market and its own substantial retail footprint. This allows the company to leverage its purchasing volume and direct consumer access for more favorable terms and pricing, reducing supplier influence.
The global nature of supply chains, particularly for pharmaceuticals, introduces vulnerabilities. Geopolitical events and raw material shortages in 2023, for example, led to input cost increases of up to 20% for some pharmaceutical raw materials, amplifying supplier leverage due to limited domestic sourcing options.
| Supplier Category | Market Concentration | Green Cross Health Leverage | Key Factors Influencing Power |
|---|---|---|---|
| Patented/Essential Pharmaceuticals | High (Few Major Manufacturers) | Moderate to Low | Dependence on critical drugs, high switching costs, global supply chain volatility. |
| Specialized Medical Equipment/IT | High (Niche Markets) | Low | High equipment costs, specialized maintenance, integration complexities, significant switching costs. |
| Skilled Healthcare Professionals (Labor) | High (Shortages) | High | Critical role, limited availability (e.g., ~5,000 FTE nursing shortage in NZ in 2024), negotiation for better terms. |
| Non-Pharmaceutical Retail Goods | Low (Fragmented) | High | Large purchase volumes, extensive retail network (Unichem, Life Pharmacy), direct consumer access. |
 Detailed Word Document
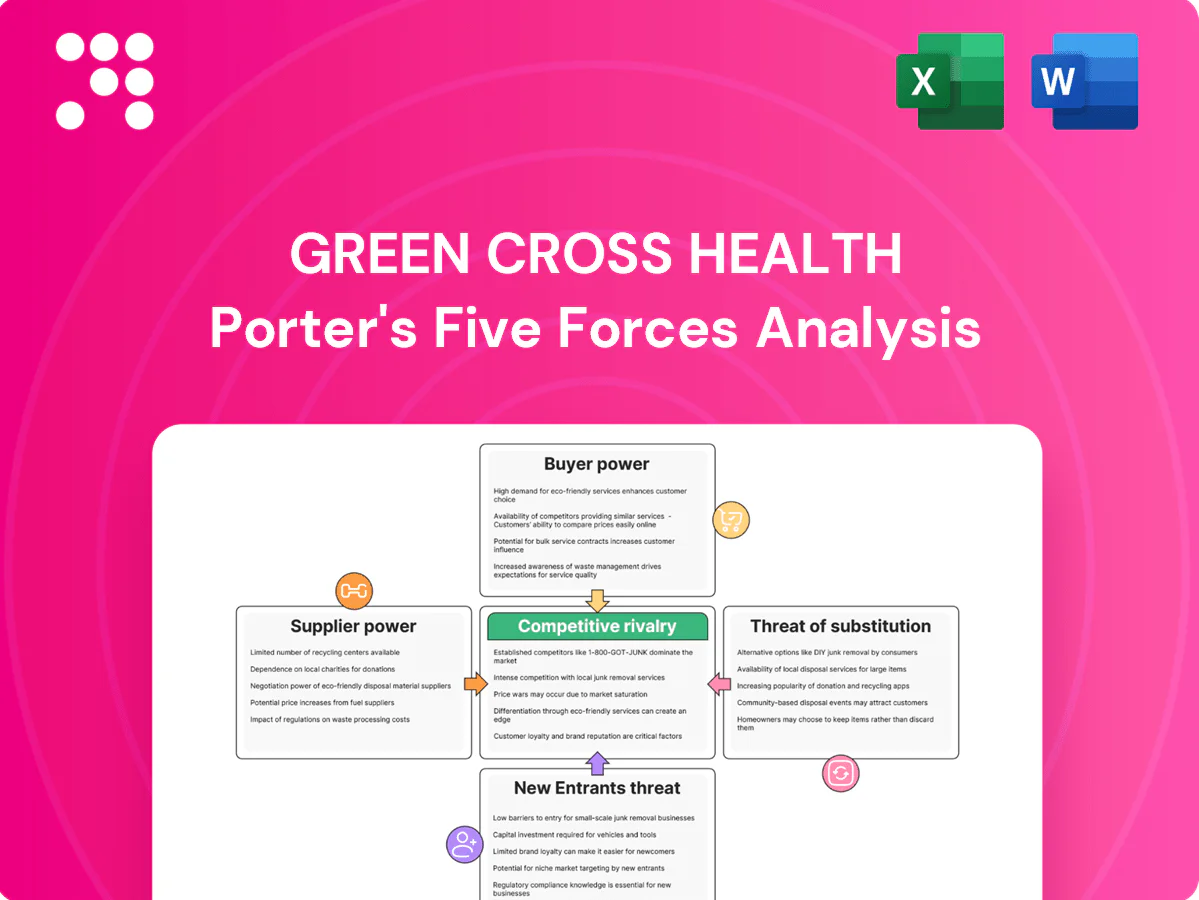
This analysis unpacks the competitive forces impacting Green Cross Health, examining supplier and buyer power, the threat of new entrants and substitutes, and the intensity of rivalry within the healthcare sector.

 Customizable Excel Spreadsheet
Instantly identify competitive threats and opportunities by visualizing the impact of each of Porter's Five Forces on Green Cross Health's market position.
Individual patients and consumers hold significant sway, especially concerning retail pharmacy items and everyday medical care. This is largely because there are so many other places to get these services. For instance, in 2024, the global retail pharmacy market was valued at over $350 billion, highlighting the sheer volume of choices available to consumers.
Customers can readily switch between different pharmacies, clinics, or even opt for online health services. Their decisions are often driven by competitive pricing, the ease of access, the quality of service, and how loyal they are to a particular brand. This ease of switching means Green Cross Health needs to work hard to stand out and build lasting connections with its customers.
To counter this, Green Cross Health actively cultivates customer loyalty through various initiatives. These include rewarding repeat business and offering tailored care that addresses individual patient needs. Such strategies are crucial in a market where customer retention is directly linked to competitive pricing and superior service delivery, a dynamic evident throughout 2024.
The New Zealand government, via Te Whatu Ora and Te Aka Whai Ora, is a substantial customer for Green Cross Health, influencing pricing and service delivery for subsidized healthcare. This concentrated purchasing power means the government can significantly impact Green Cross Health's revenue streams and operational choices.
For over-the-counter medications, health supplements, and beauty products, Green Cross Health customers are quite sensitive to price. The ability to easily compare prices online and at various physical stores means consumers actively look for the best value. This price sensitivity was evident in 2024 as consumers increasingly sought out discounts and promotions, impacting sales volumes for non-essential health and beauty items.
The proliferation of readily available health information online and the growth of telehealth services significantly bolster customer bargaining power. Patients can now research conditions, compare treatment options, and even access remote consultations, diminishing their exclusive reliance on traditional healthcare providers like Green Cross Health for initial advice or routine care.
This digital shift allows consumers to become more informed and proactive in their health management. For instance, a 2024 report indicated that over 70% of consumers research health conditions online before consulting a doctor, highlighting a marked increase in self-directed information seeking.
To counter this, Green Cross Health must strategically integrate digital health solutions. This includes enhancing their online presence, offering robust telehealth services, and developing user-friendly health apps to meet these evolving customer expectations and maintain engagement.
Green Cross Health's position is also influenced by the bargaining power of its healthcare professional customers for support services. The more unique and essential Green Cross Health's offerings are, the less power these customers wield. For instance, if alternative suppliers readily offer comparable medical products or support, these professional clients gain significant leverage. Conversely, specialized or integrated solutions provided by Green Cross Health can enhance its own negotiating strength.
In 2024, the healthcare sector saw continued consolidation, meaning larger healthcare groups might possess greater bargaining power when procuring support services. However, the demand for specialized diagnostic equipment and integrated patient management software, areas where Green Cross Health may offer unique value, could mitigate this power. The availability of substitute services is a key determinant; if many providers offer similar inventory management or telehealth platforms, customer power increases.
Individual consumers wield considerable power due to the vast array of available healthcare and retail pharmacy options. In 2024, the global retail pharmacy market exceeded $350 billion, underscoring the extensive choices consumers have. This ease of switching between providers, influenced by price, convenience, and service quality, necessitates that Green Cross Health focus on customer retention and differentiation.
The increasing availability of online health information and telehealth services further empowers consumers. By researching conditions and comparing treatments independently, patients reduce their reliance on traditional providers. For example, a 2024 report showed over 70% of consumers researched health issues online before doctor visits, highlighting a significant shift towards self-directed health management.
Green Cross Health must strategically enhance its digital presence, offering robust telehealth and user-friendly apps to meet these evolving consumer expectations and maintain engagement in a competitive landscape.
| Factor | Impact on Green Cross Health | 2024 Data/Trend |
|---|---|---|
| Consumer Choice & Switching Costs | High bargaining power due to many alternatives. | Global retail pharmacy market > $350 billion. |
| Information Availability | Empowered consumers research options, increasing price sensitivity. | >70% of consumers research health online before consultations (2024). |
| Telehealth & Digital Health | Reduces reliance on in-person visits, offering alternative care pathways. | Continued growth in telehealth adoption. |
This preview showcases the comprehensive Porter's Five Forces Analysis for Green Cross Health, detailing the competitive landscape and strategic positioning of the company. You're looking at the actual document; once your purchase is complete, you’ll get instant access to this exact, professionally formatted file, ready for your immediate use.
The New Zealand pharmacy sector exhibits a dual structure, featuring dominant corporate players like Green Cross Health, which operates the Unichem and Life Pharmacy networks, alongside a significant number of independently owned pharmacies. This dynamic fosters robust competition, especially in densely populated urban centers.
Rivalry centers on competitive pricing for over-the-counter products, the breadth of health services provided, and customer accessibility. For instance, Green Cross Health reported revenue of NZ$359.9 million for the fiscal year ending March 31, 2024, highlighting its substantial market presence.
The competitive landscape is further amplified by the presence of national chains such as Chemist Warehouse, which often engages in aggressive price-based strategies. This intense rivalry pressures all market participants to innovate and optimize their offerings to attract and retain customers.
Green Cross Health faces intense rivalry from a broad spectrum of general practitioner (GP) practices across New Zealand, encompassing independent clinics, smaller group practices, and other corporate healthcare providers. This competitive environment is characterized by a fierce battle to attract and retain qualified GPs, secure patient enrollments, and deliver a comprehensive suite of primary care services. The ongoing shortage of GPs in New Zealand significantly intensifies this competition for medical talent, directly impacting service availability and the overall quality of care provided by all players in the market.
Green Cross Health faces significant rivalry from other private providers, non-governmental organizations (NGOs), and public health services within the specialist community health sector. Competition often centers on securing government contracts through competitive tenders, where demonstrating high-quality, cost-effective service delivery is paramount.
In 2024, the Australian primary healthcare sector, which includes community health services, saw continued investment, with the government allocating over AUD 10 billion to primary health networks. This competitive landscape necessitates differentiation through specialized clinical expertise and the development of integrated service models to attract and retain both patients and funding.
The New Zealand healthcare sector, where Green Cross Health operates, is subject to significant regulation. For instance, pharmacy ownership rules dictate who can own and operate pharmacies, acting as a barrier to entry for new, potentially disruptive players. In 2024, the government continued to emphasize strict adherence to quality standards and alignment with national health strategies, shaping how existing companies like Green Cross Health compete.
These regulations directly influence competitive rivalry by defining the playing field. While they can limit direct price competition, they often shift the focus to compliance, service quality, and the ability to integrate with government-provided healthcare services. For example, changes to the Pharmaceutical Benefits Scheme funding models in 2024 could alter the profitability and competitive positioning of different pharmacy chains.
Competitive rivalry at Green Cross Health extends significantly beyond mere price competition. The company actively differentiates itself through innovation in service delivery and enhancing the overall patient experience. This strategic focus is crucial in a crowded healthcare market.
Green Cross Health’s competitive strategy involves offering superior health advice, broadening its retail product selection, and integrating advanced digital health solutions. Furthermore, the company is developing comprehensive, integrated care pathways to better serve patient needs.
Competitive rivalry within the New Zealand pharmacy sector is intense, with Green Cross Health facing pressure from both large corporate chains like Chemist Warehouse and numerous independent pharmacies. This competition is driven by pricing strategies for over-the-counter goods, the range of health services offered, and customer convenience, as evidenced by Green Cross Health's NZ$359.9 million revenue for FY24.
The rivalry is further intensified by competition for General Practitioners (GPs) and specialist community health services, where securing government contracts and differentiating through clinical expertise are key. The Australian primary healthcare sector, for example, saw over AUD 10 billion allocated to primary health networks in 2024, underscoring the competitive funding environment.
Green Cross Health differentiates itself through service innovation, enhanced patient experience, and digital health integration, aiming to gain an edge beyond simple price competition.
| Competitor Type | Key Competitive Factors | Illustrative Data/Context (2024) |
| Corporate Pharmacy Chains (e.g., Chemist Warehouse) | Aggressive pricing, broad product range | Green Cross Health FY24 Revenue: NZ$359.9 million |
| Independent Pharmacies | Personalized service, local accessibility | Significant number of independent operators in NZ |
| General Practitioner (GP) Practices | Primary care service provision, GP recruitment | Intensified competition for GPs due to shortages |
| Private/NGO/Public Health Services | Government contract acquisition, service quality | Australian PHN funding: >AUD 10 billion (2024) |
The growing prevalence of online pharmacies, both within Australia and from overseas, presents a substantial substitute threat to traditional physical pharmacies like Green Cross Health. Consumers increasingly opt for the convenience of having prescriptions and everyday medications delivered directly to their homes, often finding these services more cost-effective. For instance, by 2024, the global online pharmacy market was projected to reach hundreds of billions of dollars, highlighting a significant shift in consumer behavior.
Telehealth and digital health solutions present a significant threat of substitution for Green Cross Health. For many primary care needs and even some specialist appointments, patients can now opt for remote consultations via video calls or dedicated health apps. This offers a convenient alternative to traditional in-person visits.
The appeal of these digital alternatives lies in their accessibility and potential cost savings. Patients can receive diagnoses, prescriptions, and medical advice without leaving their homes, often at a reduced price compared to a physical clinic visit. For instance, the global telehealth market was valued at approximately $100 billion in 2023 and is projected to grow significantly, indicating a strong shift in patient preference towards digital options.
To counter this threat, Green Cross Health must actively integrate or develop its own robust telehealth and digital health offerings. Failing to adapt to these evolving patient expectations and technological advancements could lead to a loss of market share as consumers increasingly embrace the convenience and efficiency of virtual healthcare services.
The rising popularity of self-care and preventative health practices presents a significant threat of substitutes for Green Cross Health. Consumers are increasingly turning to alternative therapies like naturopathy and herbal medicine, which can directly replace some of the over-the-counter products and even professional medical advice traditionally offered by pharmacies and clinics. This shift is fueled by greater access to health information, empowering individuals to explore a wider array of wellness solutions beyond conventional healthcare channels.
Urgent care clinics and after-hours medical centers present a significant threat of substitutes for Green Cross Health's traditional GP appointments. These alternatives often provide quicker access for immediate, non-emergency medical issues, potentially drawing patients away from scheduled visits.
In 2024, the number of urgent care centers in Australia continued to grow, offering a convenient option for many Australians. For instance, some reports indicated a steady increase in the utilization of these services for common ailments, bypassing the need for a pre-booked GP appointment.
The threat of substitutes for Green Cross Health's community health services is significant, primarily from informal care networks. Family members, friends, and community volunteers often provide essential support, especially for less complex health needs, directly impacting the demand for paid professional services. For instance, in 2024, an estimated 53 million adults in the U.S. provided unpaid care, a figure that underscores the prevalence of informal support systems.
This reliance on unpaid care can limit the market size for formal providers like Green Cross Health. While professional services offer specialized medical expertise and rehabilitation, the cost-effectiveness and personal connection of informal care are powerful substitutes. This is particularly true in areas where access to professional services is challenging or expensive.
The threat of substitutes for Green Cross Health is multifaceted, encompassing digital health solutions, urgent care clinics, and informal care networks. Online pharmacies and telehealth services offer convenience and potential cost savings, with the global telehealth market valued at approximately $100 billion in 2023. Urgent care clinics provide quicker access for immediate needs, and their numbers continued to grow in Australia in 2024. Furthermore, informal care networks, with an estimated 53 million adults providing unpaid care in the U.S. in 2024, present a cost-effective alternative for less complex health issues.
| Substitute Type | Key Characteristics | Market Data/Trend (2023-2024) | Impact on Green Cross Health |
|---|---|---|---|
| Online Pharmacies & Telehealth | Convenience, cost-effectiveness, accessibility | Global telehealth market ~$100 billion (2023); significant growth in online pharmacy market | Potential loss of prescription and OTC sales; need for integrated digital offerings |
| Urgent Care Clinics | Faster access for non-emergencies, extended hours | Growing presence and utilization in Australia (2024) | Diversion of patients for acute, non-complex conditions |
| Informal Care Networks | Cost-effectiveness, personal connection, family/community support | 53 million unpaid caregivers in U.S. (2024) | Reduced demand for professional services for less complex needs |
The healthcare sector in New Zealand, where Green Cross Health operates, is a prime example of how stringent regulations can act as a formidable barrier to new entrants. Government bodies like the Ministry of Health and the Pharmacy Council of New Zealand impose extensive licensing, accreditation, and compliance requirements. For instance, establishing a new pharmacy or medical center necessitates navigating a complex web of health and safety standards, quality assurance protocols, and professional registration processes, all of which involve significant time and financial investment.
Establishing a robust healthcare network, whether pharmacies, clinics, or specialized community services, demands significant upfront capital. This includes costs for physical locations, essential medical equipment, and stocking inventory, particularly for pharmacies. For instance, setting up a single community pharmacy in Australia can easily cost upwards of AUD $500,000 to $1 million, encompassing fit-out, stock, and initial operating expenses.
These high initial expenditures act as a substantial barrier to entry for potential new competitors looking to challenge established players like Green Cross Health. Newcomers must be ready to deploy considerable financial resources, a challenge amplified when facing incumbents who already possess economies of scale and brand recognition.
A significant hurdle for new entrants into the healthcare sector, including Green Cross Health, is the persistent difficulty in attracting and retaining qualified professionals. This shortage directly impacts operational capacity and service delivery.
New pharmacies, medical centers, and community health services all face intense competition for essential staff like pharmacists, General Practitioners (GPs), and nurses. For instance, in 2023, New Zealand experienced a notable deficit in registered nurses, with projections indicating this gap would widen without significant intervention.
The cost associated with recruitment, onboarding, and offering competitive remuneration packages to secure these vital roles presents a substantial financial barrier. This makes it exceptionally challenging for emerging entities to establish and maintain adequate staffing levels, thereby limiting their ability to compete effectively with established players like Green Cross Health.
Green Cross Health benefits from strong brand loyalty with its Unichem and Life Pharmacy brands, as well as its established medical centers. This loyalty, cultivated over many years, makes it difficult for new entrants to gain market share. For instance, in 2023, Green Cross Health reported a 7.8% increase in revenue for its Pharmacy division, demonstrating the continued strength of its existing customer base.
New players face a significant hurdle in replicating Green Cross Health's established relationships and the convenience offered by its widespread network. Building trust and attracting patients away from familiar and trusted brands requires considerable investment in marketing and a lengthy period of operation. The cost and time involved in establishing a comparable presence act as a substantial barrier.
Established players like Green Cross Health benefit from deeply entrenched relationships with key pharmaceutical suppliers, ensuring consistent and often preferential access to essential medicines. This established network is not easily replicated by newcomers. For instance, in 2024, the New Zealand government continued to award significant contracts for primary healthcare services and subsidized pharmaceuticals, with existing providers like Green Cross Health often holding a strong position due to their established infrastructure and performance history.
Gaining entry into these vital government contracts presents a substantial barrier for new entrants. These contracts are often awarded through rigorous procurement processes that favor proven track records and established operational capabilities, which new businesses would lack. In 2024, the Ministry of Health's procurement activities highlighted the importance of demonstrated experience and existing service delivery models in securing these funding streams, creating a hurdle for nascent competitors.
The threat of new entrants for Green Cross Health is moderate, primarily due to high capital requirements and regulatory hurdles in New Zealand's healthcare sector. Significant upfront investment in infrastructure, technology, and staffing, coupled with stringent licensing and compliance, deters many potential competitors. For example, establishing a new pharmacy in New Zealand involves substantial costs for fit-out, inventory, and regulatory approvals, often exceeding NZD $500,000.
Furthermore, the established brand loyalty and extensive network of Green Cross Health's Unichem and Life Pharmacy brands present a considerable challenge for newcomers. Building comparable trust and market share requires significant marketing investment and time, as customers often prefer familiar and accessible healthcare providers. In 2023, Green Cross Health’s Pharmacy division saw a 7.8% revenue increase, highlighting the strength of its existing customer base.
Access to key suppliers and government contracts also acts as a barrier. Green Cross Health's long-standing relationships ensure preferential access to pharmaceuticals and a strong position in government tenders. In 2024, the Ministry of Health’s procurement continued to favor providers with proven track records, making it difficult for new entities to secure these vital revenue streams.
| Barrier Type | Description | Impact on New Entrants | Example Data/Fact |
|---|---|---|---|
| Capital Requirements | High upfront costs for facilities, equipment, and inventory. | Significant deterrent due to substantial financial outlay. | Establishing a NZ pharmacy can cost over NZD $500,000. |
| Regulatory Hurdles | Complex licensing, accreditation, and compliance with health standards. | Time-consuming and costly to navigate, requiring expert knowledge. | Ministry of Health and Pharmacy Council requirements. |
| Brand Loyalty & Network | Established trust and convenience of existing pharmacy and clinic networks. | Difficult for new entrants to attract customers away from familiar brands. | Green Cross Health's Pharmacy revenue grew 7.8% in 2023. |
| Supplier & Contract Access | Established relationships with suppliers and preferential access to government contracts. | New entrants lack the leverage and track record to secure similar deals. | 2024 Ministry of Health procurement favors established providers. |


