
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
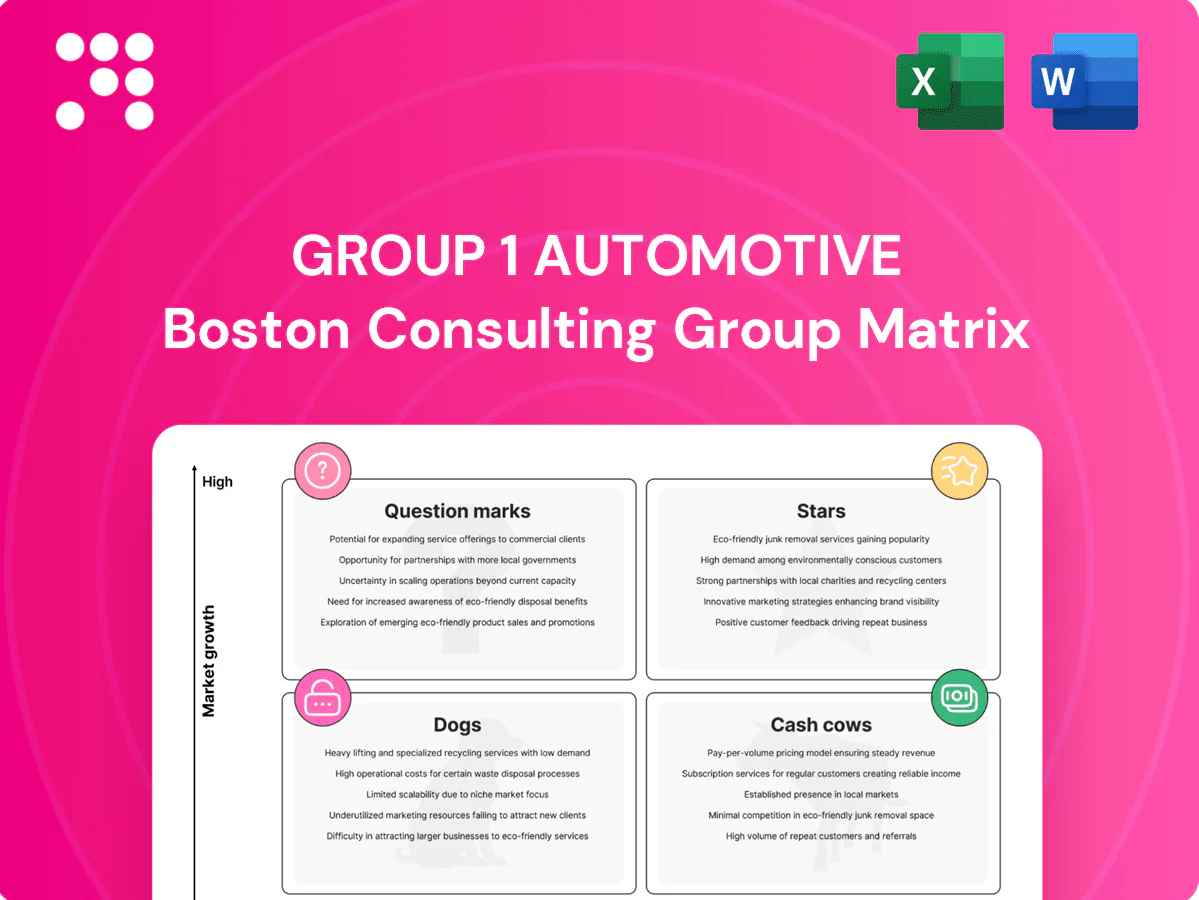
Group 1 Automotive’s BCG Matrix preview shows where key segments sit—market leaders, cash generators, and weaker performers—so you can spot quick wins and risks. Want the full picture? Purchase the complete BCG Matrix for quadrant-by-quadrant placement, data-backed recommendations, and strategic moves tailored to this company’s market reality. You’ll get a polished Word report plus an Excel summary ready to present and act on. Buy now and skip the research—get clarity fast.
Omnichannel car sales are a Star for Group 1, matching buyer shifts—Cox Automotive reports ~77% of buyers start online in 2024—while Group 1's omnichannel push supports its leading metro shares and contributed to roughly $20.1B revenue in FY2024. Heavy ongoing investment in UX, lead-gen, and last‑mile delivery is required; if share holds, scale economies can convert this into a cash cow. The flywheel: more traffic, faster inventory turns, stronger pricing power.
Reconditioned used and CPO units are moving fast in 2024 as affordability stays tight; Group 1’s scale—over 200 rooftops—and national sourcing shorten days-to-turn, but supply volatility and pricing/appraisal tech require ongoing capex. Cash turns quickly: sell-to-buy cycles keep proceeds redeployed into inventory to sustain velocity. Hold share through speed and trust; this high-margin, repeatable stream can mature into a cash cow.
In core U.S. markets, trucks and SUVs — roughly 75% of new-vehicle sales in 2024 — still drive demand growth and strong share for Group 1 Automotive.
Inventory turns, accessory upsell and local brand equity make these high-volume franchises leaders, though marketing, allocation management and CX need continued investment.
Win allocation and protect gross to convert growth into stable margins; as demand cools they can graduate to cash‑cow status.
Select UK metro dealership clusters are gaining share as UK new‑car registrations recovered roughly 10% in 2024 (SMMT); grouped rooftops drive scale in marketing, logistics and service capture, lifting unit margins and fixed‑cost leverage. Growth is back but winning needs tight OEM coordination and digital retail muscle; keep the pedal down to lock in leadership before the curve flattens.
Integrated collision center network is a referral-driven, insurer-preferred Star for Group 1 Automotive in 2024, leveraging sales and service to capture high share in urban corridors; double-digit throughput gains from DRP relationships and referral flows drive durable returns. Ongoing capital for equipment, OE parts inventory and tech training is required, but nailing cycle time and OE mix lifts margins materially.
Group 1's Stars—omnichannel ($20.1B FY2024; 77% start online), fast-turn CPO/reconditioned (200+ rooftops), truck/SUV franchises (~75% new‑vehicle mix) and collision DRP networks (double‑digit throughput) drive share and high margins but need ongoing capex and OEM coordination to convert to cash cows. Scale, speed and digital execution are the levers to lock leadership.
| Star | 2024 Metric | Impact |
|---|---|---|
| Omnichannel | $20.1B rev; 77% online starts | Scale + pricing power |
| CPO/Recond | 200+ rooftops | Fast turns, high margin |
| Trucks/SUVs | ~75% new mix | Volume driver |
| Collision | DD throughput (DRP) | High aftermarket margin |
 Detailed Word Document
BCG analysis of Group 1 Automotive: identifies Stars, Cash Cows, Question Marks, Dogs with investment, hold, or divest recommendations.

 Customizable Excel Spreadsheet
One-page BCG matrix for Group 1 Automotive that highlights underperformers and growth bets, ready for C-level decks.
Fixed ops is Group 1 Automotive’s margin engine: mature, high-share demand within the owner base with stable traffic, predictable upsell and strong absorption. Low incremental marketing is required while steady 2024 investment in service bays and technicians continues to raise yield and throughput. Milk the cash while prioritizing efficiency projects to sustain margin and fund targeted facility and tech upgrades.
Parts distribution and wholesale are cash cows: inventory turns daily in a mature aftermarket where entrenched dealer relationships secure repeat business. Scale pricing and same‑day delivery sustain share, supporting Group 1 Automotive’s core operations (company revenue was about $19.1 billion in 2023). It’s a volume game with disciplined working capital—optimize routes, tighten inventory, bank the cash.
F&I products and financing penetration are high for Group 1, with processes dialed and attach rates stable year-over-year per 2024 company disclosures. The market is mature but share is defensible through ongoing training and strict compliance programs. Low growth, high margin — a classic cash cow that funds strategic initiatives. Keep the playbook sharp and let it finance experiments.
Core mainstream brand dealerships deliver reliable suburban volume with solid market share and low churn as noted in Group 1 Automotive 2024 filings; marketing efficiency and high repeat purchase rates keep customer acquisition costs muted. Maintain retail standards, tighten SG&A, and harvest free cash flow while defending share.
Service contracts and prepaid maintenance deliver recurring revenue with predictable bay utilization and high attachment rates; NADA 2024 shows fixed-ops accounted for ~45% of dealership gross profit, underscoring the steady cash flow. Growth is modest but the installed base is large and sticky, requiring minimal promotion once processes scale. Use proceeds to smooth seasonal cycles and fund strategic upgrades.
Cash cows: fixed ops, parts/wholesale, F&I and mainstream rooftops deliver high-margin, low-growth cash for capex and buybacks; fixed-ops ~45% of dealer gross profit (NADA 2024); Group 1 revenue $19.1B (2023).
| Metric | Value |
|---|---|
| Fixed-ops share | ~45% (NADA 2024) |
| Revenue | $19.1B (2023) |
The Group 1 Automotive BCG Matrix you're previewing is the exact file you'll receive after purchase — no watermarks, no drafts, just the finished report. It’s fully formatted and ready to use in presentations, planning, or investor discussions. After purchase you’ll get the same editable document instantly, so no surprises. Built for clarity and action, it’s deliverable as shown here.
Underperforming rural rooftops show low footfall, limited inventory turns and little market-share growth, leaving cash tied up in thin gross margins and high fixed overheads. Turnarounds require significant capex and working capital yet rarely move the needle on profitability. These locations are prime candidates for consolidation or exit to redeploy capital into higher-return urban rooftops.
Legacy print and radio-heavy marketing for Group 1 Automotive faces a shrinking audience and fuzzy attribution: digital ad spend accounted for about 64% of US ad dollars in 2024 while print ad revenue fell over 10% year-over-year, leaving fixed costs and low ROI. With low growth and poor returns, significant budget remains stuck in underperforming channels—time to cut print/radio and reallocate to measurable digital channels.
Non-core fringe brand stores hold small allocations and face weak local demand; in 2024 they accounted for roughly 2% of Group 1 Automotive’s footprint and generated flat-to-declining share, with minimal OEM support and limited inventory inflows.
Share remains low and isn’t climbing, management attention outweighs payoff given margin pressure and higher-opportunity rooftops; recommend divestiture or folding operations into nearby Group 1 locations to cut costs and redeploy capital.
Aging collision sites without DRP produce inconsistent volume and long cycle times; Group 1 Automotive reported consolidated net sales of about 18.6 billion in FY2024, yet collision growth is flat and equipment is dated, causing retention issues and idle cash on balance sheets.
Overbuilt, capex-heavy showrooms sized for yesterday’s traffic now face structurally lower footfall; utilization is down, fixed costs remain sticky, and management signals limited organic growth ahead in 2024 without outsized spending.
There is little incremental share to capture without overspending; recommended moves: shrink footprint, repurpose excess space for service, used-vehicle retailing, or third-party revenue streams.
Underperforming rural rooftops, legacy marketing and non-core fringe stores generated low share and thin margins; FY2024 net sales $18.6B yet these Dogs (~2% footprint) deliver flat/declining volumes and require outsized capex to improve.
| Metric | 2024 |
|---|---|
| Net sales | $18.6B |
| Dog footprint | ~2% |
| Digital ad share | 64% |
Growing customer interest in EVs—about 8% of US new-vehicle sales in 2024—creates opportunity for Group 1, but market share is fragmented and OEM inventory uneven across its US, UK and Brazil markets. Early investment in training, chargers and specialized tooling ties up capital, with public chargers near 150,000 nationwide in 2024. If local adoption accelerates this can become a star; if not, it may slide toward dog status quickly.
Direct-to-consumer online-only deals are a high-growth, low-current-share Question Mark for Group 1 Automotive, facing strong disruptors in digital retailing; Cox Automotive reported in 2024 that roughly 26% of buyers used digital retailing tools, underscoring market potential. Logistics, titling, and remote F&I require heavy investment and process redesign. If conversion and CAC math validate unit economics, the model can scale rapidly; if not, cap losses quickly.
Customers love convenience, but economics for mobile service and pickup/drop-off at Group 1 Automotive (GPI) remain unproven at scale; 2024 pilots focused on dense markets where GPI operates over 200 dealerships across the US and UK. Routing, technician productivity and parts availability are operational bottlenecks that reduce utilization and raise costs. Invest where density supports positive unit economics and measure relentlessly; expand only when unit economics turn.
Data-driven pricing and reconditioning AI is a question mark for Group 1 Automotive: promising margin lift if appraisal accuracy and days-to-line improve, but penetration remains low and tooling, integrations, and change management require significant time and capital; pilot quickly and prune faster to avoid sunk costs.
New brand entries in select UK/US metros target marques growing double digits across luxury and EV-adjacent segments, but Group 1’s share starts low and needs OEM franchise agreements, facility capex (typical dealer builds ~2–5m USD), and 12–24 months ramp to hit breakeven; success can unlock metro clusters and scale benefits, while underperformance should trigger capital redeployment.
Question Marks: EV adoption (~8% US new-vehicle sales in 2024) and 150,000 public chargers create upside, but market share fragmented across 200+ dealerships; digital retailing adoption ~26% (Cox Automotive 2024) is high-growth yet low-share; mobile service, D2C logistics and AI reconditioning need upfront capex and proveable unit economics or fast redeploy.
| Initiative | 2024 metric | Key barrier |
|---|---|---|
| EV retail | 8% US sales; 150k chargers | OEM inventory, capex |
| Digital retail | 26% buyer usage | Logistics, CAC |


