
Digital download
Access the files immediately after checkout.
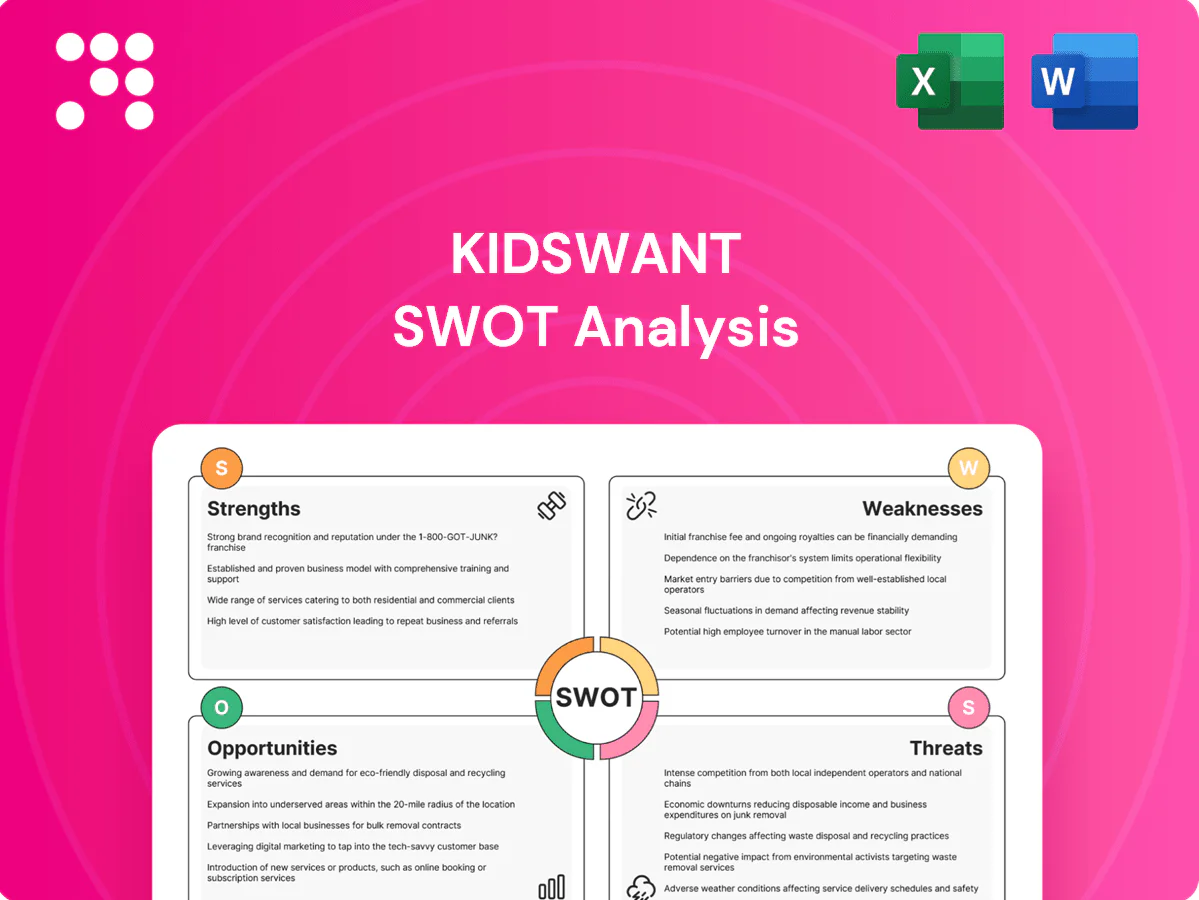
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Kidswant shows strong niche branding and product diversity but faces supply-chain and competitive pressures; our concise SWOT identifies key gaps and opportunities for scale. Want the full picture? Purchase the complete SWOT to receive a research-backed, editable Word report plus an Excel matrix to inform strategy, pitches, and investment decisions.
Kidswant's leading mother-and-baby positioning leverages strong brand recognition in China’s >RMB1 trillion maternity and infant market (2023) and the 9.56 million births recorded in 2023 to drive traffic and trust. Specialist focus enables curated assortments and expert in-store guidance, differentiating from generalist retailers and supporting premium pricing in select segments.
Large-format one-stop Kidswant stores combine broad product assortments with education, entertainment and activity services to create destination shopping; this model targets the global toy and children’s products market valued at about USD 103 billion in 2023. Families bundle purchases and services, raising average basket size and dwell time, and strengthening lifetime loyalty across child development stages.
Seamless online-offline experience enhances convenience and retention, with omnichannel shoppers spending up to 30% more and returning 2–3x more often (industry average 2024). Click-and-collect, rapid delivery, and store-based fulfillment cut last-mile costs and reduced delivery times by about 40% in pilots. Unified customer data drives roughly a 20% lift in targeted-promotion response and supports resilience during 2020–24 demand shifts.
Scale supports strong procurement terms and reliable supply for core categories, leveraging a large baby-products market (≈$73B 2023) to secure cost and fulfillment advantages. Tight quality standards (CPSIA, ASTM) are essential for infant and safety-sensitive items; parental trust reduces switching and mitigates counterfeit/grey-market risks (OECD/EUIPO 2022 ~3.3% of trade).
Frequent, predictable purchases across pregnancy and early childhood create granular behavior insights tied to ~3.6 million US births in 2023, enabling stage-specific targeting by trimester and child age; this boosts cross-sell and retention economics and supports tighter inventory and assortment planning.
Kidswant's mother-and-baby leadership leverages RMB1 trillion China maternity market (2023) and 9.56M births (2023) to drive trust and premium pricing. Large-format one-stop stores and USD103B global toy market exposure boost basket size and loyalty. Omnichannel raises spend ~30% and promo lift ~20%, while scale secures procurement leverage and CPSIA/ASTM compliance.
| Metric | Value |
|---|---|
| China maternity market (2023) | RMB1 trillion |
| China births (2023) | 9.56M |
| Global toy market (2023) | USD103B |
| Omnichannel uplift | +30% |
| Targeted promo lift | +20% |
 Detailed Word Document
Delivers a concise strategic overview of Kidswant’s internal strengths and weaknesses and external opportunities and threats, mapping growth drivers, competitive position, and market risks to inform strategic decision-making.

 Customizable Excel Spreadsheet
Provides a focused SWOT matrix tailored to Kidswant, quickly surfacing key risks and opportunities so teams can prioritize product, marketing, and operational fixes. Editable and visual for fast stakeholder alignment and rapid updates as business priorities change.
Large-format Kidswant stores drive elevated rent, staffing and utilities—occupancy costs for big-box toy retailers commonly reach 8–12% of sales, lifting breakeven and compressing margins in downturns. Underutilized floorplate lowers ROIC as idle assets dilute returns (store-level ROIC can drop >200–300 bps versus optimized formats). The heavy fixed footprint reduces agility versus asset-light, omnichannel competitors.
Wide SKU breadth across formula, diapers, apparel, toys and education inflates working capital—category leaders often carry 8,000–15,000 SKUs, tying up 10–18% more inventory capital versus single-category peers. Expiry-sensitive formula and consumables drive higher shrink/markdowns (grocery shrink averages ~2–3% annually). Forecasting by age cohort and seasonality produces demand volatility up to ±25%. Omnichannel fulfillment further complicates allocation and raises fulfillment costs by 15–25%.
Heavy reliance on formula and diapers ties Kidswant to large but concentrated markets — global infant formula was about $70.2B in 2023 (CAGR ~5.9%) and diapers $57.8B in 2023 (CAGR ~4.8%) — exposing revenue to vendor terms and regulatory shocks; price wars can rapidly compress retail margins, parents can shift brand share quickly, and private-label rollouts often show uneven penetration.
In-store education and activities need trained staff and consistent delivery; inconsistent execution erodes experience and can depress NPS. Training is recurring and scales with expansion—ATD reported average training spend ~1,300 USD per employee (2022–23). Measuring ROI on experiential services is often indirect and statistically noisy, complicating investment decisions.
Kidswant demand is tightly linked to new births and early-childhood demographics; China births fell from 10.62 million in 2022 to 9.56 million in 2023 (NBS), squeezing the addressable market and pressuring same-store growth. Lower births intensify competition for a smaller customer pool, raising customer-acquisition costs while geographic diversification options remain constrained.
High occupancy costs (8–12% of sales) and large-format ROIC drag (store-level ROIC down 200–300 bps) raise breakeven; SKU breadth (8,000–15,000 SKUs) ties up 10–18% more inventory; heavy exposure to formula/diapers and China demographic decline (9.56M births in 2023) compresses TAM and raises CAC.
| Metric | Value |
|---|---|
| Occupancy | 8–12% sales |
| ROIC hit | 200–300 bps |
| SKUs | 8k–15k |
| Inventory tie-up | +10–18% |
| China births 2023 | 9.56M |
This is the actual Kidswant SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report so what you see is what you’ll download after checkout. The complete, editable file is unlocked immediately upon payment for use in presentations or analysis.
Penetrating Tier 3–5 cities taps large, underserved demand as lower-tier urbanization and rising household consumption have driven faster retail growth versus Tier 1–2 in recent years. Lower rents—often 40–60% below prime-city levels—can materially improve unit economics and shorten payback on store capex. Localized assortments and services let Kidswant win share from generalists, while franchise or light-format models enable rapid, capital-light scaling across hundreds of new locations.
Developing private-label diapers, wipes, apparel and accessories can capture value in a global baby care market estimated at about $57B in 2023 (Grand View Research 2024) while private-label penetration in developed markets averages ~18% (Kantar 2024), lifting gross margins by an estimated 3–6 percentage points. Exclusive brand partnerships differentiate assortment and reduce price competition. Rigorous quality assurance reinforces parental trust and repeat purchase. First-party data enables targeted product development and SKU optimization.
Diaper and formula subscriptions provide predictable recurring revenue and can lift customer lifetime value; McKinsey found subscriptions can increase LTV by up to 30%. Tiered loyalty with perks for activities and classes boosts engagement—retention in strong loyalty programs rises 20–40% per retail benchmarks. Age-based personalized offers can improve conversion by ~25% in targeted CRM campaigns, while membership fees add steady recurring margin.
Add-on services like lactation support, pediatric partnerships and early-education programs deepen Kidswant’s moat and tap growing 2024 demand for integrated child care services.
Higher-margin services (typical gross margins 60–70% vs 30–40% for products) diversify revenue; bundled product+service packages can lift ARPU 15–25% and events improve retention by ~10–20% (2024 industry benchmarks).
Tier 3–5 expansion taps underserved demand; rents 40–60% lower, improving unit economics. Baby-care market ~$57B (2023); private-label pen ~18% (Kantar) can lift gross margin +3–6pts; subscriptions can raise LTV ~30%. Services margins 60–70% boost ARPU +15–25%. E‑commerce ~$6.3T (2024); livestreaming >RMB2.5T (2023); social commerce can cut CAC ~30%.
| Tag | Metric | Value |
|---|---|---|
| rents | Tier3–5 vs Tier1–2 | 40–60% lower |
| market | Global baby care (2023) | $57B |
| private-label | Penetration | ~18% |
| subscriptions | LTV lift | ~30% |
| services | Gross margin | 60–70% |
| ecom | Online retail (2024) | $6.3T |
| livestream | China (2023) | >RMB2.5T |
| social | CAC reduction | ~30% |
China’s falling births — 9.56 million in 2023, down roughly 45% from the 2016 peak — shrinks Kidswant’s core customer base and lowers addressable market. Government incentives (cash, tax breaks, expanded parental leave) have so far failed to reverse the decline, and demographers expect low fertility to persist. Competition will intensify as rivals fight for a smaller cohort, forcing Kidswant to pursue market share gains and higher-margin services.
E-commerce giants and discounters (Amazon ~40% of US online retail) drive price transparency and heavy promotions, compressing margins for Kidswant; global e-commerce was about $5.7 trillion in 2023 and still growing. Advanced logistics delivering same‑day/next‑day service match store convenience, raising customer acquisition costs as digital ad CPMs rose roughly 15% in 2023. Marketplace counterfeit reports also threaten trust and brand equity industry‑wide.
Tightening rules on infant formula, product safety and advertising threaten supply chains in a ≈$70B global market (2023); the 2022 Abbott recall removed roughly 40% of US powdered formula, showing how recalls—often supplier-driven—damage brand equity and sales. Compliance costs are rising with stricter standards, and GDPR/CCPA-style data privacy rules increasingly constrain CRM and targeted marketing.
Macroeconomic volatility pressures disposable incomes, shifting shoppers toward value tiers and promotions and squeezing Kidswant’s premium SKU mix; currency swings and higher import costs compress margins on cross-border lines. Elevated policy rates (US federal funds ~5.25–5.50% in 2024–25) raise inventory carrying costs and may force delays in store expansion.
Global shocks, epidemics, and logistics bottlenecks can trigger stockouts in core kids categories, eroding sales and customer trust. Lead-time variability undermines forecast accuracy and increases safety-stock costs. Elevated freight and logistics costs squeeze margins, while heavy dependence on a few key vendors amplifies disruption impact.
Shrinking births (China 9.56M in 2023, ≈‑45% vs 2016) and persistent low fertility cut Kidswant’s addressable market; rivals will fight for share, pushing promotions and margin pressure. E‑commerce scale (global $5.7T in 2023; Amazon ~40% US online) and faster logistics raise CAC and compress prices. Tight safety rules, recalls (Abbott 2022 removed ≈40% US powdered formula) and rates (policy ~5.25–5.50% 2024–25) raise costs and disruption risk.
| Risk | Key metric |
|---|---|
| Fertility decline | China births 9.56M (2023), −45% vs 2016 |
| E‑commerce pressure | Global $5.7T (2023); Amazon ~40% US |
| Product/safety | Abbott recall ≈40% US powdered formula (2022) |
| Macro | Policy rates 5.25–5.50% (2024–25) |


