
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
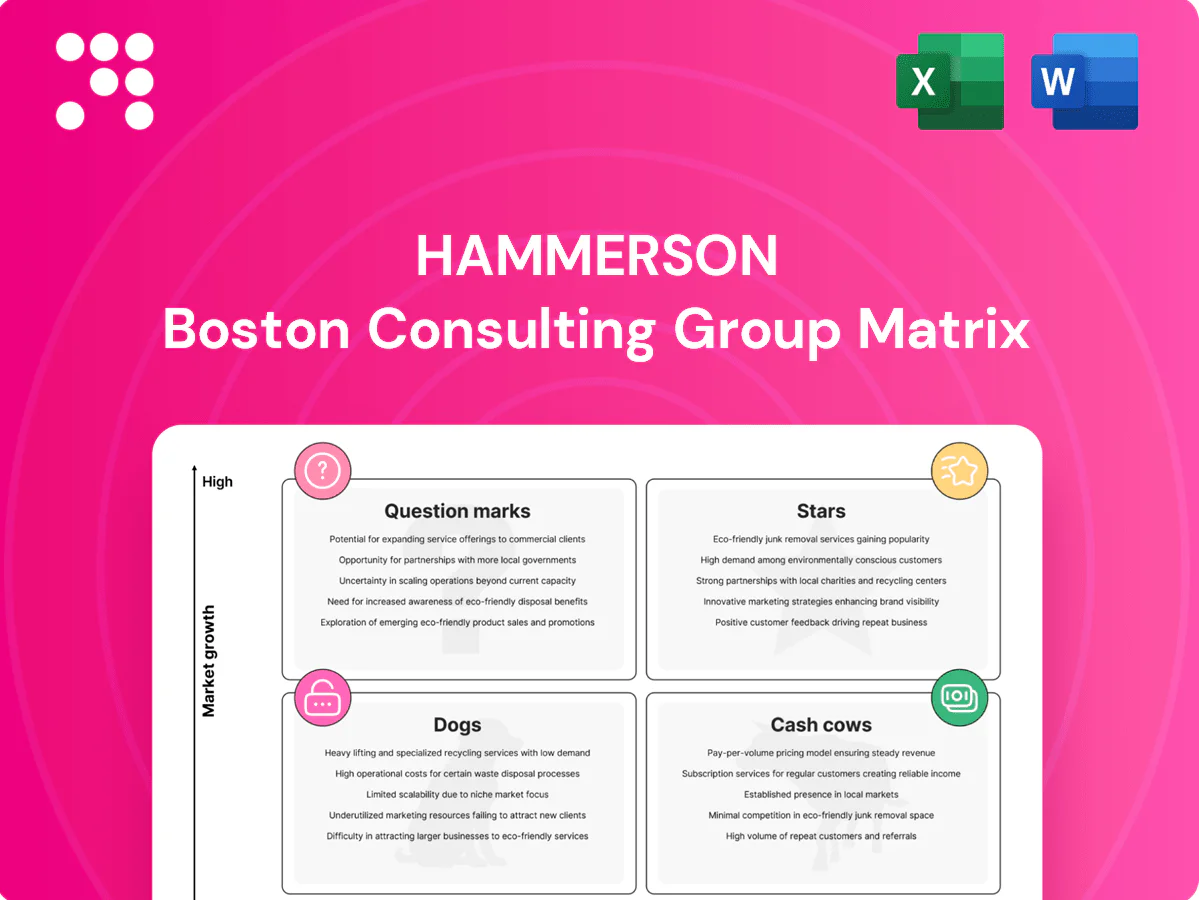
Curious where Hammerson’s assets fall — Stars, Cash Cows, Dogs, or Question Marks? This snapshot teases the truth; the full BCG Matrix gives you quadrant-by-quadrant placement, data-backed rationale, and clear moves for capital allocation and portfolio pruning. Skip the guesswork and grab the complete report for Word + Excel deliverables that you can present or act on today. Purchase now and turn insight into decisions that actually move the needle.
Prime city‑centre flagships deliver high footfall (typically c.20–30% above secondary assets), strong tenant mix and constant buzz that keeps leasing momentum hot; they anchor brand positioning and set pricing power across the Hammerson portfolio. These sites often run c.90%+ occupancy and drive top‑quartile rents, absorb capex for placemaking and tech, and warrant hold and continued investment so they can transition into cash cows as markets mature.
Entertainment, dining and events increase dwell time (industry studies show up to +30%) and can lift spend per visit by around +25%, prompting retailers to cluster around these anchors; Hammerson’s strategy allocates roughly 20% of GLA to F&B/experiential to drive the portfolio flywheel. These zones require ongoing curation and marketing, with current capex meaningfully front-loaded so cash in equals cash out short term but builds market share over 3–7 years. Back them: experiential anchors underpin footfall, tenant sales and whole-asset valuation.
Mixed‑use densification around estates — adding homes, offices and hotels — creates all‑day footfall that lifts rents and reduces vacancy; JLL 2024 found mixed‑use assets outperformed single‑use by about 10% in rental growth. Planning, financing and delivery are capital hungry, with development yields often needing 5–10 years to crystallise. The growth curve is visible and each complementary use deepens the competitive moat. Keep pushing; today’s growth becomes tomorrow’s yield.
ESG-driven repositioning transforms Hammerson Stars: 2024 energy upgrades and community programs lower opex by ~15% and boost asset relevance, with tenants increasingly pricing sustainability into rents (green rent premiums around 4–6% in 2024 market studies); upfront capex lifts valuation and demand concurrently, turning compliance into a concealed growth engine.
Prime flagships deliver 20–30% higher footfall, c.90%+ occupancy and top‑quartile rents, warranting continued investment to become cash cows. Experiential F&B (≈20% GLA) and omnichannel anchors (29% click‑and‑collect 2024) boost dwell time up to 30% and spend ~25%. ESG upgrades cut opex ~15% and support 4–6% green rent premiums, justifying upfront capex.
| Metric | Value | Note |
|---|---|---|
| Footfall uplift | 20–30% | Prime vs secondary |
| Occupancy | ≈90%+ | Prime flagships |
| Click‑and‑collect | 29% | ONS 2024 |
| Opex saving | ~15% | Energy/efficiency 2024 |
| Green rent premium | 4–6% | 2024 studies |
 Detailed Word Document
Concise BCG review of Hammerson’s assets, identifying Stars, Cash Cows, Question Marks, Dogs and recommended actions.

 Customizable Excel Spreadsheet
One-page Hammerson BCG Matrix clarifying portfolio choices—quickly printable and C-suite ready
Hammerson’s stabilized flagship rental streams show high occupancy (c.96% in 2024) with predictable footfall supporting tight operations and low downtime. Growth is modest but margins are strong—EBITDA margins around 65% and 2024 rental income ~£216m—making these assets reliable cash generators. Low incremental marketing is needed as prime malls largely sell themselves, allowing the portfolio to be milked for cash while maintaining service and standards.
Blue‑chip anchor leases typically run 10–25 years, delivering covenant strength and steady base rent that stabilises Hammerson cash flow. Once embedded, capex requirements fall sharply, preserving NOI and supporting dividend capacity. These anchors underpin refinancing and bank facilities and, as of 2024, remain central to Hammerson’s liquidity strategy. Protecting and making those relationships sticky is priority.
Parking and ancillary services deliver recurring, low‑growth income for Hammerson with strong cash margins—parking margins typically exceed 50%—and accounted for a steady share of centre revenues as footfall recovered to roughly 90% of 2019 levels by 2024. Small pricing tweaks and tech (cameras, dynamic pricing, contactless) improve throughput and yield without major capex. Simple, boring, cash‑positive — optimize utilisation, don’t overbuild.
Disciplined cost pass‑through kept Hammerson’s NOI resilient in 2024, with service‑charge recovery roughly 96% and portfolio cash yields near 6.2%, underpinning predictable income from core centres.
Mature operational playbook, low volatility and minimal hype make this a dependable yield source; incremental systems upgrades in 2024 squeezed modest additional margin.
Cash generated quietly funds higher‑risk repositioning and capital projects without diluting returns, allowing selective reinvestment into experience and leasing strategies.
Core UK/FR mature centers: market share is set and growth is moderate, with UK retail footfall recovering to around 96% of 2019 levels in 2024 (Springboard); leasing cycles are predictable and incentives contained, producing steady rental income that reliably covers corporate costs and debt service. Strategy: maintain, refresh lightly, and harvest cash.
Hammerson cash cows: high occupancy (~96% 2024) and stable rents (2024 rental income ~£216m) yield strong margins (EBITDA ~65%) supporting ~6.2% portfolio cash yield; low capex and long anchor leases (10–25y) preserve NOI and fund strategic redeployments.
| Metric | 2024 |
|---|---|
| Occupancy | ~96% |
| Rental income | ~£216m |
| EBITDA margin | ~65% |
| Cash yield | ~6.2% |
The file you're previewing is the exact Hammerson BCG Matrix report you'll receive after purchase. No watermarks, no demo text—just a fully formatted, ready-to-use strategic matrix. It’s crafted for clarity and immediate use in presentations or planning. Once bought, the same file is yours to download, edit, and share without surprises.
Dogs:
Legacy department store boxes in Hammerson centres occupy oversized footprints with structurally limited tenant demand and high holding costs. Subdivision or re-anchoring requires significant capex and lengthy leasing cycles, draining cash and management bandwidth. Meanwhile rent drag and negative market optics depress centre yields and shopper perception; without a credible repositioning plan the rational move is disposal or repurposing.
Thin footfall (c.20% below pre‑pandemic levels) and price‑only competition have eroded rents at underperforming retail parks, compressing rental values and driving incentives above historic norms. Turnarounds require significant capex and leasing timeframes, often taking several years and large tenant incentives. Returns on these assets rarely clear Hammerson’s cost of capital, so divestment or conversion to alternative uses (logistics, residential, leisure) is frequently the most value-accretive route.
Small non‑strategic JVs create complex governance with limited control and middling returns, consuming disproportionate management bandwidth while tying up cash for limited upside; recommend simplifying the structure and pursuing exits where possible.
Geographies with persistent decline show flat or falling spend and leasing; UK retail vacancy ran near 13% in 2024, compressing rental growth and making holding costs (rates, maintenance, financing) erode returns; upside is unclear so avoid chasing sunk costs and stop incremental capital unless IRR targets met; wind down exposure methodically via staged disposals, repurposing or lease expiries.
Dogs: secondary town malls, legacy department boxes and weak retail parks show c.13% UK vacancy in 2024 and footfall ~20% below pre‑pandemic, compressing rents (~‑8% y/y) and yields; capex-heavy turnarounds take 3–7 years and often miss cost of capital, so prioritize staged disposals, repurposing to logistics/residential and JV simplification.
| Asset | 2024 vacancy | Footfall vs 2019 | Rent change 2024 | Action |
|---|---|---|---|---|
| Secondary malls | 13%+ | -20% | -8% | Exit/repurpose |
Planning‑led residential/office overbuild on Hammerson estates offers strong upside if 2024 planning approvals and pre‑lets proceed, materially unlocking asset value through densification and mixed‑use income diversification. Execution risk is high: delayed consents or weak pre‑lets would impair returns and depress NAV per share. Prioritise schemes with secured planning or strong pre‑let traction, double down on winners and shelve higher‑risk sites.
Screens, sponsorships and anonymized shopper data can stack new revenue lines for Hammerson by monetizing on-site attention and first‑party insights; Insider Intelligence projected global retail media ad spend to top 100 billion USD by 2025, signaling strong upside. Demand is still early and fragmented across landlords and advertisers, so scale is the leaver that could flip this question mark into a star. Run rapid tests, productize winning formats and then roll out at portfolio scale to capture higher CPMs and incremental leasing income.
On‑site energy (rooftop solar ~900 kWh/kWp pa), EV charging (UK public chargers ~60,000 in 2024) and smart BMS show rising tenant and consumer pull but sit as Question Marks in Hammerson’s BCG matrix. Heavy initial capex (commercial solar ~£1,000/kWp) and uncertain tariff and wholesale pathways compress short‑term returns. If policy support and FiT‑style incentives persist, margins can materially improve. Pilot, partner and expand only where measured payback <7–8 years.
Question Marks: converting back-of-house and edge plots into last-mile logistics can tap surging parcel demand; industrial yields outperformed dead retail in 2024 by roughly 250 basis points in many UK markets, but Hammerson must navigate zoning and community fit hurdles.
Run targeted proofs on 1–3 assets rather than blanket redevelopments; pilot yields and rent-roll lifts can validate scale-up before portfolio-wide deployment.
DNVBs, health/beauty concepts and creator retail demand flexible short-term deals; pop-up churn is higher but 20–30% of concepts in incubators typically scale to permanent space within 12–24 months, refreshing footfall and supporting rent reversion.
Right curation can lift centre mix and yields; targeted incubation, weekly sales KPIs and NPS, then graduate winners to standard leases to capture higher lifetime rents and lower vacancy.
Prioritise 1–3 pilots (planning-led overbuild, retail media, energy/EV, last‑mile logistics) to convert Question Marks into Stars; use strict go/no‑go metrics (pre‑lets, payback <7–8y, pilot IRR). Scale winners, shelve high‑risk sites.
| Opportunity | 2024 metric | Action |
|---|---|---|
| Retail media | Global spend ~100bn USD by 2025 | Pilot → productize |
| Energy/EV | Rooftop ~900 kWh/kWp; UK chargers ~60,000 | Partner & pilot |
| Logistics | Last‑mile demand +8% y/y; yield gap ~250bps | Targeted redeploy |


