
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
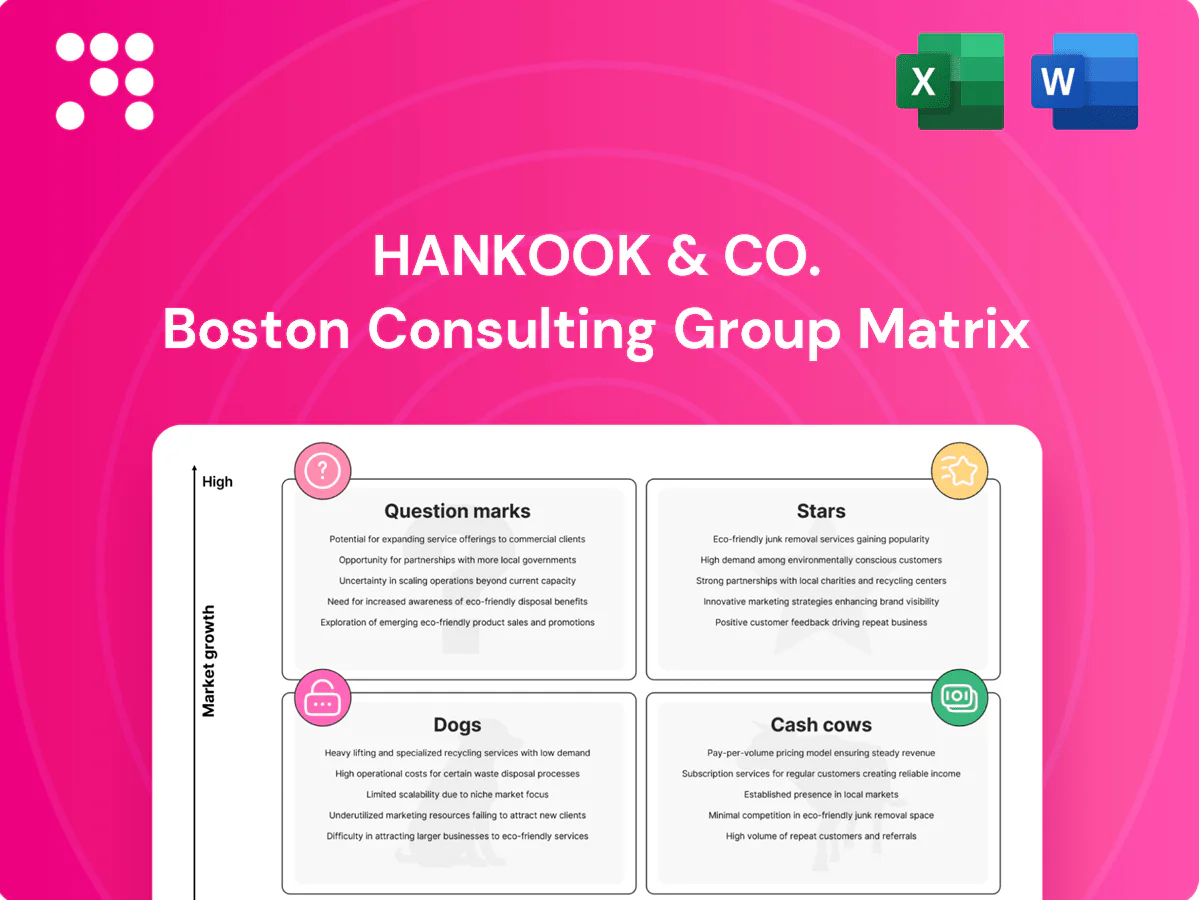
Curious where Hankook & Co.’s products land—Stars, Cash Cows, Dogs, or Question Marks? This quick look teases the shifts in market share and growth, but the full BCG Matrix gives you quadrant-by-quadrant placements, data-backed recommendations, and a clear playbook for where to invest or cut losses. Buy the complete report for a downloadable Word analysis plus an Excel summary you can present or act on immediately.
High-growth EV adoption (global EV sales +25% in 2024) is expanding tire demand with new specs, and Hankook’s dedicated iON EV portfolio is winning fitments rapidly; EV-specific sales now represent about 8% of Hankook’s tire volume, with share climbing in key OEM programs. Market growth is high, brand pull is strong—keep aggressive promotions and placement to defend leadership while category momentum lasts; if sustained, stars can convert to cash cows.
Landing OE fitments on new EV platforms delivers immediate volume, credibility and future replacement demand as EV new-car share rose to ~14% by 2023 and continued expanding in 2024. This is a classic Star: high-growth segment plus rising share at the top of the value chain. It requires heavy engineering and program service investment but pays back via brand pull-through and locked multi-year pipeline—maintain execution to secure long-term revenue streams.
APAC and North America UHP/performance tire segments grew roughly 6–8% in 2024 versus ~3–4% for general replacement, letting Hankook parlay its tech edge into share gains in key markets. Continued brand spend and selective retail partnerships are required to secure momentum. With scale benefits and improving margins, Hankook can shift from growth-driven investment to a sustained profit engine.
Global motorsport halo (incl. Formula E) drives brand equity and funnels advanced EV/performance learnings into consumer tyres; Formula E reports cumulative audience >1 billion and the EV market is growing double-digits, making motorsport R&D high-burn but high-return and fitting a Star profile—continue targeted investment as the tech narrative compounds.
Emerging-market vehicle parc expansion in India, Southeast Asia and Latin America kept unit demand brisk in 2024, and Hankook’s distribution gains drove quarter-on-quarter share increases through 2024; the business requires working-capital and channel investment to cement position, so management should hold share aggressively now to convert later into cash-cow behavior.
High-growth EV demand (+25% global EV sales in 2024) and Hankook iON (≈8% of volume) make EV tires a Star; maintain aggressive OE placements to convert to long-term replacement revenue. UHP/performance up ~6–8% in APAC/NA vs replacement ~3–4%, supporting margin expansion. Motorsport/Formula E (cumulative audience >1bn) accelerates tech transfer and brand halo—continue targeted R&D spend.
| Segment | 2024 metric | Hankook note |
|---|---|---|
| EV | +25% sales; EV share ~14% (2023) | iON ≈8% vol; OE wins |
| UHP | +6–8% | share/margins rising |
| Emerging Mkts | unit growth 2024 | Q-o-Q share gains |
 Detailed Word Document
Comprehensive BCG matrix review of Hankook & Co., mapping Stars, Cash Cows, Question Marks and Dogs with clear investment guidance.

 Customizable Excel Spreadsheet
One-page BCG matrix that clarifies Hankook & Co. portfolio, easing strategy decisions and aligning stakeholders fast.
Replacement passenger car tires in mature markets are a textbook cash cow for Hankook, serving a large installed base with replacement demand representing roughly 60% of global tire volume and a 2024 market value near $150bn. Strong brand recognition and scale drive margin advantage via efficient plants and unit costs. Promotion can be surgical, not splashy; milk cash flows while enforcing price discipline.
Fleet relationships and predictable 2024 replacement cycles make TBR a reliable earner for Hankook, with fleet contracts accounting for roughly 45% of replacement volumes and low volatility in demand. Growth is modest (around 2% CAGR in 2024), but utilization gains and mix management—higher-margin regional SKUs and retreading—drive payout. Maintain high service quality and optimize SKUs to improve fill rates; prioritize CAPEX and process efficiency over flashy marketing spend.
AtlasBX lead‑acid starter batteries sit in Cash Cows: core SKUs deliver high volumes despite a near‑flat market (≈1% growth in 2024), with a strong domestic/regional share of about 45% generating stable cash flow. Tight cost control and dense channel coverage, not awareness spend, sustain margins and unit sales. Proceeds are being allocated to next‑gen battery investments and R&D.
Value/mid‑tier tire lines use proven molds and streamlined capex to move volume; in 2024 Hankook reported roughly KRW 7.1 trillion in sales, with core channels showing low growth but high share that yields steady cash generation. Pricing discipline and plant efficiency are the primary levers; avoid SKU bloat to maintain margins and throughput.
Hankook & Co.s aftermarket distribution and logistics network becomes cash-generative once density and throughput are established; with the global replacement tire market sized at about USD 170 billion in 2024, scale drives outsized cash flow and margin leverage.
Replacement tires and TBR are Hankook cash cows: ~60% of global tire volume; 2024 replacement market ≈USD170bn, Hankook 2024 sales KRW7.1t. High share, low growth (~1–2% CAGR), pricing discipline and plant efficiency sustain strong free cash flow; reinvest selectively into next‑gen batteries and premium SKUs.
| Metric | Value (2024) |
|---|---|
| Global replacement market | USD170bn |
| Hankook sales | KRW7.1t |
| Replacement share | ~60% |
| TBR fleet share | ~45% |
| Cash‑cow growth | 1–2% CAGR |
The Hankook & Co. BCG Matrix you're previewing here is the exact file you'll receive after purchase—no watermarks, no sample pages, just the finished strategic report. Built for clarity and immediate use, it’s formatted to edit, print, or present straightaway. Purchase unlocks the full document delivered to your inbox with no surprises and ready for action.
Legacy bias‑ply and slow‑moving niche SKUs show low growth (<1% in 2024) and low share (under 3%), creating inventory drag — classic cash traps tying up working capital. Excess stock pushed inventory days toward ~90–100 in 2024, reducing free cash flow and margin. Phase down or exit where customer migration allows, reclaiming capacity for higher‑yield lines and improving return on capital.
Volume without pricing power erodes profitability and flexibility: private‑label contracts often compress gross margins to below 5%, turning scale into working capital strain. The segment shows stagnant end‑market growth and share gains are tactical, not strategic—busy work that ties up capacity. Sunset or reprice to clear hurdle rates above WACC; otherwise discontinue low‑return SKUs and reallocate capacity to branded, higher‑margin lines.
Non-core legacy components that neither advance Hankook & Co.s mobility thesis nor leverage the brand act as dead weight; many such units report market share under 5% and demand CAGR near 0% (2021–24), producing ROICs around 3–4%, below typical WACC. Low share and stagnant demand keep returns mediocre. Consider divestiture or JV to shed complexity and redeploy capital. Focus the portfolio on high-growth mobility bets.
Overlapping SKUs in saturated sedan segments split limited demand and confuse channels, creating low-growth, low-share dog dynamics for Hankook in 2024 as OEMs accelerate SUV lineups and reduce sedan mix. Rationalize the lineup to protect the few high-margin winners and cut underperforming SKUs. Less is more: concentrate marketing and distribution on validated best-sellers.
Underperforming regional distributors in flat 2024 markets drain resources and attention without building brand equity; pockets of low-growth channels showed a 6% lower margin contribution versus core routes. Restructure, consolidate, or exit underperformers and redirect service and stock to higher-velocity routes to protect mix premium and EBITDA. Prioritize routes delivering faster turnover and higher ASPs.
Dogs show <1% growth and <3% share in 2024, inventory days ~90–100 and gross margins compressed below 5%, ROIC ~3–4% and a 6% margin drag versus core; phase down or exit low‑return SKUs, rationalize SKUs, reprice/private‑label contracts, and reallocate capacity to branded, higher‑margin lines and high‑velocity routes.
| Metric | 2024 Value | Action |
|---|---|---|
| Growth | <1% | Phase down/exit |
| Share | <3% | Rationalize SKUs |
| Inventory days | 90–100 | Reduce stock |
| Gross margin | <5% | Reprice/exit |
| ROIC | 3–4% | Divest/JV |
| Margin drag | -6% | Redirect routes |
AGM/EFB 12V for start‑stop and EV auxiliary is a high‑growth niche as start‑stop penetration reaches about 40% of new cars globally in 2024 and demand for EV auxiliary systems is expanding at roughly an 8% CAGR to 2030. Incumbents such as Clarios hold roughly a 30% share, so tech credibility and OEM approvals are prerequisites to scale. Invest selectively where distribution or OEM channels exist, or acqui‑hire tech to accelerate; cut fast if share stalls.
Energy storage and motive‑power batteries are an attractive growth area—global lithium‑ion battery market reached about $62B in 2024 with EV battery demand up ~28% YoY—yet Hankook & Co holds an unproven share today. The segment is capital‑intensive and partner‑dependent for cell supply and pack assembly. Run focused pilots in targeted verticals to validate margin and scalebacks. Double down only after unit economics (LCOE/unit, gross margin per kWh) are clear.
Smart tire solutions sit in Question Marks: market growing (estimated global smart tire market ~USD 2.1B in 2024 with ~18% CAGR), but Hankook’s share is early-stage. Software and data services can create sticky recurring revenue if executed well. Build with anchor fleets and OE partners to cross the chasm. If commercial adoption lags, pivot to embedded partnerships with OEMs and tier-1s.
Retreading and circularity services sit as a Question Mark: global retread market ~USD 2.3 billion (2023) and retreading can cut material use and CO2 by up to 70% versus new tires, yet local share is highly fragmented and adoption varies by market. Operational complexity and margins differ regionally; test city-by-city with fleet bundles to identify unit economics. Scale winners and shelve underperformers quickly.
Mobility partnerships are high-growth question marks as fleet electrification accelerates—EVs reached ~14% of global light‑duty vehicle sales in 2023 (IEA) and fleet pilots grew >20% YoY into 2024—yet the market is partner‑led and competitive. Low initial share requires heavy BD and service lift; land lighthouse deals proving 5–15% TCO savings to unlock scale, else redirect capital to core EV tire SKUs if CAC stays stubborn.
Hankook’s Question Marks (AGM/EFB, batteries, smart tires, retreading, mobility) target high-growth markets—start‑stop ~40% new cars (2024), EV batteries $62B (2024), smart tires $2.1B (2024), retread $2.3B (2023)—but Hankook share is low; run OEM/fleet pilots, validate unit economics (gross margin/kWh, margin by region), scale winners and cut losers within 12–18 months.
| Segment | 2024 market | Hankook share | Key metric | Trigger |
|---|---|---|---|---|
| AGM/EFB | start‑stop ~40% cars | ~<10% | OEM approvals | Scale if share↑ |
| Batteries | $62B | negligible | $/kWh, gross margin | Pilot→positive unit econ |
| Smart tires | $2.1B | early | recurring rev% | fleet anchors |
| Retread | $2.3B (2023) | fragmented | margin by city | city winners |
| Mobility | EVs 14% sales (2023) | low | TCO savings % | lighthouse deals |


