
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
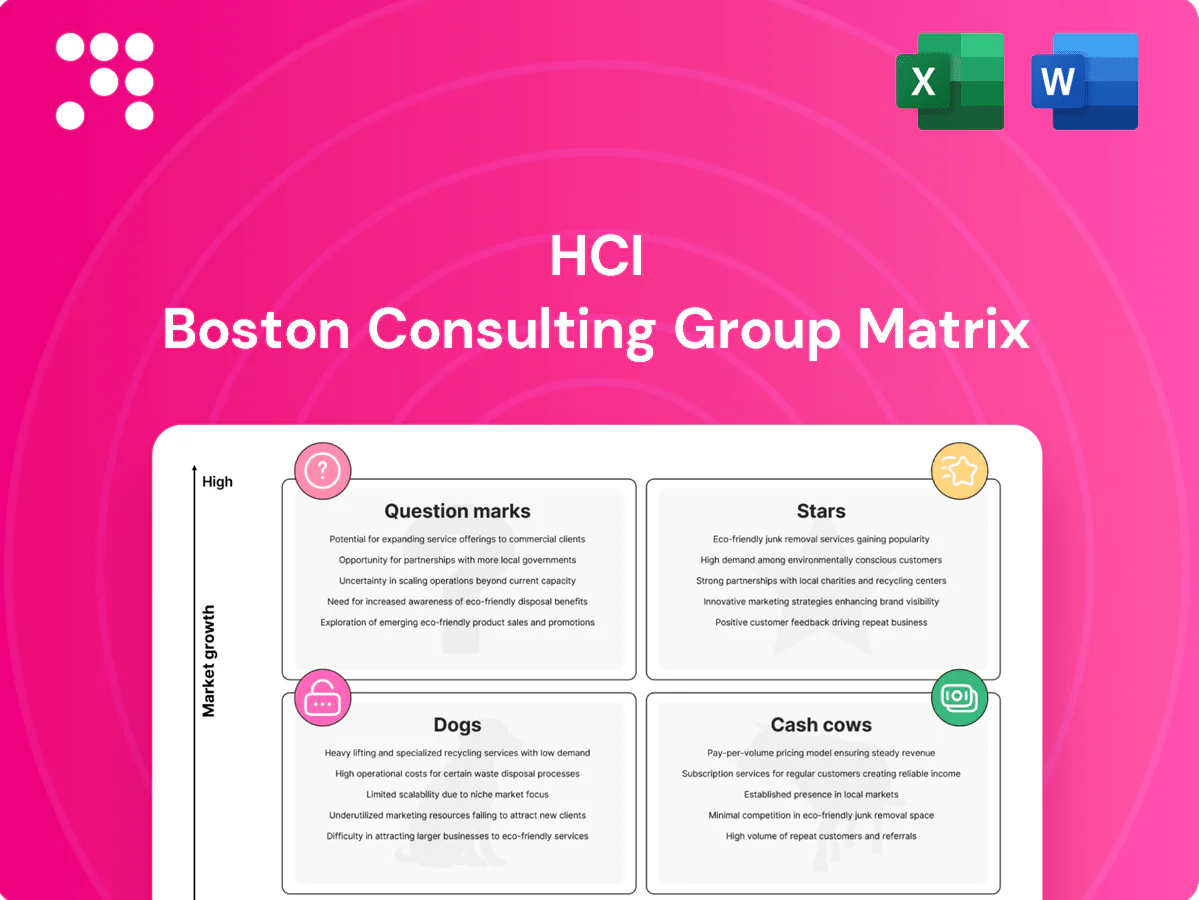
The HCI BCG Matrix snapshot shows which products are sprinting ahead and which are holding you back—Stars, Cash Cows, Dogs, and Question Marks that matter to your roadmap. This preview teases quadrant placements and quick takes; the full BCG Matrix gives you the complete quadrant-by-quadrant analysis, data-backed recommendations, and ready-to-use Word and Excel files so you can act fast. Purchase the full report to turn this clarity into strategic moves you can implement this quarter.
Florida homeowners core book sits large and visible amid strong demand: Florida population 22.24M (2023) with net domestic inflow ~+100k (2023), and statewide home values up, keeping premium base active. With 30-year mortgage rates elevated (~6.8% mid-2024) retention stays resilient when service is tight, making this the engine brand customers recognize. Keep share and keep investing — this is the path to tomorrow’s Cash Cow.
Tech-enabled underwriting and claims deliver measurable advantages: 2024 pilots showed up to 40% faster claims cycle times and 20-30% lower leakage, translating to higher Net Promoter Scores and reduced loss adjuster hours. In a hard market that efficiency compounds, improving hit rates and retention while lowering cost of risk. Allocate budget to these tools—typical payback appears within 12–18 months and drives incremental market share.
Cat analytics and risk segmentation in Florida hinge on picking the right roofs on the right streets; targeted ZIP-level risk scoring reduces tail exposure and preserves margin. Strong catastrophe models plus a disciplined appetite drive profitable growth while peers retract, a gap reflected in superior bind ratios and lower loss pick-up. That advantage supports doubling down on selective growth while profitable cohorts expand.
Hard‑market reinsurance services sit as Stars in HCI's BCG matrix: cedents need capacity and structuring help while top reinsurers are busy, driving 2024 treaty price increases roughly 10–30% in property cat renewals and higher margins; advisory plus disciplined program design secures repeat business and sticky relationships, so keep pushing — momentum matters.
Preferred distribution in growth corridors keeps agencies happy with quick quotes and clean claims; carriers positioned as carrier-of-choice in high-growth ZIPs typically see 20–30% higher submission velocity and double-digit pipeline uplift in 2024 market reports, turning visibility into selective growth while protecting the channel and keeping the flywheel spinning.
Florida core book sits large: population 22.24M (2023), net inflow +100k (2023) and 30y rate ~6.8% (mid‑2024), keeping retention strong. Tech underwriting cut claims cycle up to 40% and leakage 20–30%, payback 12–18 months. ZIP‑level cat scoring reduces tail risk and improves bind ratios. Reinsurance advisory benefits from 2024 property cat price rises ~10–30% and sticky cedent demand.
| Metric | Value | Impact |
|---|---|---|
| FL pop | 22.24M (2023) | Large addressable market |
| Net inflow | +100k (2023) | Premium growth |
| 30y rate | ~6.8% (mid‑2024) | Retention resilience |
| Claims speed | −40% | Lower costs |
| Reinsurance price | +10–30% (2024) | Higher margins |
 Detailed Word Document
Concise HCI BCG Matrix review: evaluates products as Stars, Cash Cows, Question Marks, Dogs with investment and divest guidance.

 Customizable Excel Spreadsheet
One-page HCI BCG Matrix mapping pain points to strategic actions per quadrant for quick executive decisions
Renewal book in stable territories delivers lower churn (10–15% annually) and predictable loss patterns with loss ratios around 60–65% in 2024, enabling reliable free cash flow. Reinsurance pricing has stabilized at roughly 3–5% of premium, so maintain rate discipline and minimal promotion. Milk carefully—invest just to retain service levels, don’t starve it.
Administrative and policy fees and program service income are steady, low‑growth cash cows that generated reliable operating cash flow in 2024; industry benchmarks show recurring fee lines outperformed volatile revenue streams. Little incremental investment is needed to maintain them, so incremental margins rise with scale—benchmarks in 2024 put margins at roughly 35–45%. Proceeds are routinely redeployed to fund higher‑risk growth bets.
Investment income on float benefits from rising short-term yields — the 2024 effective federal funds rate averaged roughly 5.33% and 10‑yr Treasuries ~4.2%, quietly boosting operating cash. It’s boring in a good way: predictable, low-volatility yield. Maintain tight duration and cash liquidity to match catastrophe seasonality. Let the surplus bankroll R&D and strengthen the balance sheet.
Recurring reinsurance placements renew annually with modest lift; setup costs are already amortized and maintenance is light, producing predictable ceding patterns and steady revenue streams for HCI. Hold the line on pricing and optimize expense to preserve margins while monitoring exposure concentration. Treat these as cash cows within the BCG matrix: low growth, high relative share, reliable cash generation.
Mature IT support contracts in HCI show stabilized clients with routine updates and little customization, delivering low growth but reliable margins and renewal rates typically above 85% in 2024. Cross-sell only when accretive; otherwise keep operations lean and cash-generative. Monitor churn and support cost-to-revenue closely.
Renewal book: low churn 10–15% (2024), loss ratio 60–65%, reinsurance 3–5% of premium—steady free cash flow.
Fee lines: low growth, margins ~35–45% in 2024; redeploy proceeds to growth bets.
Investment float aided by Fed funds ~5.33% and 10yr ~4.2% (2024); keep short duration.
| Item | 2024 Metric |
|---|---|
| Churn | 10–15% |
| Loss ratio | 60–65% |
| Reinsurance | 3–5% |
| Margins | 35–45% |
| Renewal IT | >85% |
The file you're previewing is the exact HCI BCG Matrix you'll receive after purchase. No watermarks, no demo content—just a fully formatted, analysis-ready report built for clarity and decision making. Once bought it’s yours to download, edit, print, or present. Delivered immediately and designed by strategy pros, so no surprises and no extra work needed.
Subscale non-core geographies comprise small books outside core states that lack distribution leverage and pricing power, so loss ratios can swing dramatically while operating costs remain fixed. Cash frequently gets trapped in administrative churn and variance reserves, reducing free cash flow available for growth. Given persistent capital drag and limited scale economics, consider exit or roll-up to restore profitability and redeploy capital.
Legacy on‑prem software modules are Dogs in the HCI BCG matrix: high support burden consuming roughly 70% of IT maintenance budgets (Gartner, 2024) while client appetite falls and modern stacks outpace them on features and speed. Revenue contribution is flat with low growth (<5% CAGR typical for legacy lines). Recommend sunset with clear migration path and cost-to-migrate metrics to shift customers to cloud-native alternatives.
Low‑retention agency niches carry high service drag and typically see churn rates of 40–60% (2024 benchmarks), collapsing lifetime value to under $5,000 and trimming gross margins to 20–30%, so churn kills unit economics fast. You often pay similar or higher acquisition and servicing costs just to stand still. Trim and redeploy reps to lanes with 3x higher LTV to restore payback periods and profitability.
High‑loss coastal micro‑segments suffer chronic cat exposure with thin rate adequacy; observed loss ratios often exceed 120% and reinsurance cessions can consume 30–50% of underwriting margin. Capital sits idle between infrequent severe events, depressing RoE. Shrink the footprint or fully reprice risks—no halfway measures.
One‑off bespoke reinsurance deals are custom work that never scales, typically representing under 3% of treaty volumes in 2024 and generating renewal probabilities of roughly 15–25%. Setup pain is high: onboarding, legal and modelling often consume 10–30% of initial premium, leaving transactions cash neutral at best after true cost. Say no more often to protect margins and focus on scalable treaties.
Dogs—low growth, low share lines drain capital and margin: legacy modules consume ~70% of IT maintenance (Gartner 2024), niche agencies churn 40–60% reducing LTV < $5k, coastal micro-segments show loss ratios >120% with 30–50% reinsurance cessions. Recommend exit/sunset or roll-up to redeploy capital.
| tag | metric (2024) |
|---|---|
| IT maintenance | ~70% |
| agency churn | 40–60% |
| LTV | <$5k |
| loss ratio | >120% |
| reinsurance | 30–50% |
Growth exists but market share is not yet secured; multi‑state homeowners can scale quickly if acquisition and loss metrics hold. State filings and distribution setup commonly take 3–12 months and require up‑front spend, while reinsurance ceded ratios typically range 10–30% of premiums, impacting capital needs. If unit economics (loss ratio, combined ratio, CAC payback) stay favorable it can flip to Star rapidly; if not, pull back fast.
Insurance SaaS for carriers sits as a Question Mark: carriers demand speed and robust data plumbing, yet you’re a small fish today with limited market share; typical sales cycles run 6–18 months and ACVs commonly range $100k–$1M+ (2024 market behavior). Focus R&D and go-to-market on 2–3 killer modules that prove ROI quickly; kill remaining modules if traction lags within 12 months.
AI-assisted claims automation is a Question Mark with massive efficiency upside—2024 pilots reported 20–40% claims handling time reductions and potential L&A expense cuts of 10–25%. It remains early innings: training, audit trails and regulatory comfort typically require 12–24 months and material investment. Pilot tightly with measurable KPIs (cycle time, accuracy, L&A savings). Scale only where loss-adjusting value is proven.
Demand for private flood and cat endorsements is rising as protection gaps widen; 2023 global insured catastrophe losses were about $127B (Swiss Re sigma), and private flood penetration in the US reached roughly 20% by 2024, but pricing and mapping remain highly technical and volatile.
Capital intensity and aggregation limits bite early—reinsurers and ILS require strict exposure management—so accurate pricing creates a durable moat; mispricing forces shelving the line.
Question Marks: MGA and embedded partnerships sit in low-share/high-growth slots—2024 pilots reported conversion lifts up to 3x and onboarding times cut ~60%, but distribution can explode overnight or fizzle if the right partner misses targets; build a repeatable onboarding and compliance playbook and place a few smart bets rather than ten scattershot pilots.
High growth but low share: scale if unit economics hold; state filings 3–12m and reinsurance cede 10–30% of premiums. Insurance SaaS sales cycles 6–18m, ACV $100k–$1M+ (2024); AI claims pilots cut handling time 20–40% (2024). Private flood US penetration ~20% (2024); 2023 insured cat losses ~$127B.
| Metric | Value |
|---|---|
| State filings | 3–12m |
| Reinsurance cede | 10–30% |
| SaaS sales cycle/ACV | 6–18m / $100k–$1M+ |
| AI pilots | 20–40% time cut |
| Private flood US | ~20% (2024) |
| Insured cat losses | $127B (2023) |


