
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
H&H Group's SWOT snapshot reveals strong brand heritage and product diversification but highlights supply-chain tightness and margin pressure; growth hinges on emerging-market expansion and new product development. Want the full strategic picture? Purchase the complete SWOT analysis—research-backed, investor-ready Word report plus editable Excel to plan, pitch, and decide with confidence.
Biostime, Swisse and Dodie are widely recognized for quality, efficacy and safety across infant nutrition, vitamins and baby-care categories, underpinning premium positioning that supports pricing power and higher gross margins. Science-backed formulations and visible R&D investments strengthen trust among caregivers and health-conscious adults, lowering customer acquisition costs. Strong brand equity enables efficient cross-selling across life stages and channels.
H&H Group's exposure across pediatric, adult and pet nutrition mitigates single-segment volatility by tapping distinct growth pools; the global infant formula market was roughly USD 80 billion in 2024, supplements ~$200 billion and pet care ~$280 billion, diversifying demand drivers. Category breadth across infant formula, vitamins, supplements and baby care smooths revenue cycles. Seasonal and regional demand differences hedge macro and regulatory shocks, enabling portfolio reallocation to high-growth pockets.
H&H’s strong presence in China and broader APAC taps wellness demand across a region of roughly 4.4 billion people, supporting volume growth. International distribution delivers scale and supplier leverage, lowering procurement and logistics unit costs. Localized product-market fit accelerates velocity in retail and APAC e-commerce, which accounts for about 60% of global online sales. Geographic spread boosts resilience and enables rapid transfer of brand learnings across markets.
H&H Group leverages established retail, pharmacy, cross-border e-commerce and DTC channels to broaden consumer access and reduce reliance on any single partner. Strong influencer, KOL and social-commerce activation drives faster trial and repeat purchase, while data-driven CRM enables personalized campaigns that boost lifetime value.
Regular line extensions and novel formulations keep H&H brands relevant, with a steady innovation cadence focused on margin-accretive premium SKUs. Regulatory-compliant development limits copycat risk and strengthens channel access. NPD emphasizes immune, gut health, beauty-from-within and pet wellness to sustain top-line and mix upgrades.
H&H brands (Biostime, Swisse, Dodie) command premium pricing via trusted, science-backed formulations, driving higher gross margins and efficient cross-selling. Portfolio spans infant formula (~USD80bn 2024), supplements (~USD200bn) and pet care (~USD280bn), diversifying revenue and reducing single-segment risk. Strong APAC reach (4.4bn population) and omnichannel/e-commerce (online ~60% of global sales) amplify scale, CRM and influencer-driven LTV.
| Metric | Value |
|---|---|
| Infant formula market (2024) | USD 80bn |
| Supplements market (2024) | USD 200bn |
| Pet care market (2024) | USD 280bn |
| APAC population | 4.4bn |
| Online sales share | ~60% |
 Detailed Word Document
Delivers a strategic overview of H&H Group’s internal and external business factors, identifying key strengths, weaknesses, opportunities, and threats to inform competitive positioning and future growth.

 Customizable Excel Spreadsheet
Provides a clear SWOT snapshot of H&H Group for fast strategic alignment and stakeholder briefs, relieving analysis bottlenecks; editable layout lets teams update priorities quickly and integrate findings into reports and presentations.
Pediatric nutrition is tightly regulated (MFDS/FDA/EU) with shifting rules on labeling, composition and marketing; the global infant formula market was about USD 78 billion in 2024, increasing scrutiny raises approval, audit and licensing costs and slows time-to-market. Non-compliance can trigger recalls or sales suspension, reducing H&H Group’s agility versus less-regulated categories.
Sales are heavily concentrated in China and select APAC corridors, with China representing over 50% of H&H Group’s regional revenue mix in 2023, heightening country risk.
High price points restrict addressable volume among price-sensitive consumers, limiting H&H Group’s reach in mass-market channels. Economic slowdowns have historically prompted downtrading to value brands, increasing the need for promotional intensity that can erode gross margins. Defending share through discounts risks margin dilution, while online price-comparison environments amplify elasticity and accelerate switching toward lower-priced alternatives.
Supply chain complexity across regulated categories raises risk for H&H: infant formula and supplements demand stringent quality control and full traceability, with regulatory approval cycles often taking 6–18 months. Multi-country sourcing and manufacturing amplify logistics and compliance costs, while input-cost spikes and disruptions can compress margins; the global infant formula market was roughly USD 70bn in 2024.
H&H faces intense competition from multinationals and aggressive local champions across infant formula, VMS and pet care, where rivals hold deeper R&D capabilities, larger media budgets and stronger shelf-bargaining power. Defending share demands sustained marketing and innovation spend that compresses near-term margins. Ongoing category commoditization further risks eroding brand differentiation.
Regulatory burden in pediatric nutrition raises approval, audit and recall risks, slowing time-to-market and raising costs. Revenue is China‑concentrated (>50% of 2023 sales), increasing country risk. High prices, supply-chain complexity (6–18 month supplier qualification) and fierce local/global competition compress margins and limit mass-market reach.
| Metric | Value |
|---|---|
| China revenue share (2023) | >50% |
| Global infant formula market (2024) | ~USD 70–78bn |
| Supplier qualification | 6–18 months |
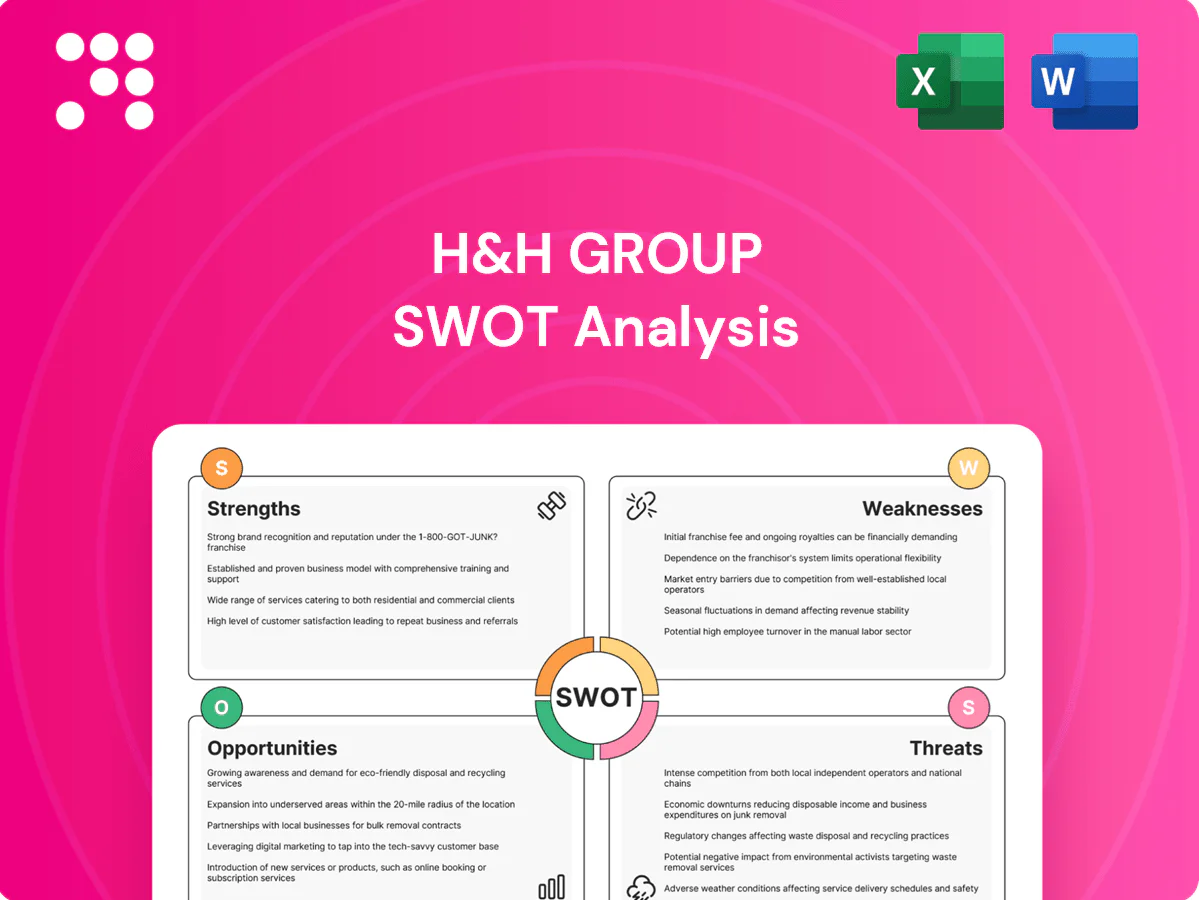
This is the actual SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full SWOT report you'll get, so what you see is what you’ll download. Purchase unlocks the full, editable version with complete detail and formatting.
Consumers increasingly demand clinically supported immunity, gut, cognition and beauty-from-within solutions; the global dietary supplements market was about $169B in 2023 and is growing at ~8% CAGR, supporting premium SKU pricing. Higher-value SKUs and curated bundles can raise ARPU and margins. Evidence-led claims and proprietary ingredients build moats; moving into medical nutrition or condition-specific lines can expand TAM and drive premium revenue.
Stabilization in China’s cross-border and domestic channels could reignite growth after 2023–24 reopening disruptions, with cross-border e-commerce volumes recovering toward pre-pandemic levels; penetration into Southeast Asia and India — markets growing mid-single-digit to high-single-digit CAGR — offers a long runway. Localization of formulations and formats (baby-safe, climate-adapted textures) can accelerate adoption, while partnerships with pharmacy chains and mother-baby stores deepen last-mile distribution and repeat purchase rates.
Rising pet humanization—70% of US households own a pet (APPA 2023) and global premiumization—supports demand for premium, functional pet products, letting H&H target higher-margin SKUs. Vet-recommended and specialty entries would raise credibility and ASPs. DTC subscriptions can lift retention and customer LTV while adjacent supplements and grooming broaden basket size.
Scaling DTC raises gross margins and builds first-party data for hyper-personalization; global e-commerce crossed the $6 trillion mark in 2023, underscoring scope for higher lifetime value. Loyalty programs and community content boost retention and advocacy, while AI demand-forecasting cuts inventory waste and supports faster NPD. Marketplaces and live commerce expand reach at materially lower CAC.
Mergers, acquisitions and partnerships can rapidly add novel technologies, new product categories and regional distribution for H&H, while contract manufacturing and joint ventures de-risk capital expenditure and expand capacity. Collaborating with clinical research organizations and key opinion leaders strengthens evidence and speeds professional adoption; targeted bolt-on deals and portfolio pruning sharpen strategic focus.
Global supplements $169B (2023), ~8% CAGR supports premium SKUs; evidence-led clinical claims and medical nutrition expand TAM. China cross-border rebound + SEA/India growth (mid–high single digits) and 70% US pet-owning households drive pet premium demand. Scaling DTC (global e‑commerce $6T 2023) and targeted M&A accelerate margins and capability build.
| Opportunity | Metric | Impact |
|---|---|---|
| Premium supplements | $169B, 8% CAGR | Higher ASPs/margins |
| China/SEA/India | mid–high SD CAGR | New TAM |
| Pet | 70% US pet ownership | Premium/skus |
| DTC/M&A | $6T e‑commerce | Margins, capabilities |
Stricter 2024 regulatory updates across major markets for infant formula, vitamin/mineral supplements and cross-border e-commerce can constrain H&H Group’s growth by limiting market access and increasing time-to-market. Rapid changes to labeling, health-claim rules and data-privacy requirements force costly reformulation, packaging and IT changes. Certification delays have already stalled launches and promotions in key channels. Compliance spending risks rising faster than revenue as rules tighten.
Rising inflation and IMF 2024 world growth of 3.1% can push consumers toward lower‑priced brands, raising downtrading risk for H&H’s premium portfolio. RMB volatility (about a 5% depreciation vs USD in 2024) increases costs for imported inputs and compresses reported HKD/HKD earnings. Retailers are likely to demand deeper promotions and longer payment terms, while a sudden elasticity spike risks inventory write-offs on premium SKUs.
Dairy, botanicals and specialty actives have seen price and availability swings—up to 30% year-on-year in 2024—driven by weather, harvest shortfalls and input inflation, pressuring margins. Logistics bottlenecks (longer lead times, port congestion) have eroded service levels and brand trust, with some suppliers reporting delayed shipments of 4–8 weeks. Quality incidents at suppliers risk recalls and regulatory scrutiny, while hedging strategies have only partially offset volatility, often covering 50–70% of short-term exposure.
Algorithm shifts or fee changes at major marketplaces can compress margins and visibility; Amazon held about 38% of US e-commerce in 2024 and referral/FBA fees can range roughly 6–45%, magnifying impact on sellers. Cross-border restrictions can abruptly cut demand for export lines, while retailer private labels—about 18% of US grocery sales in 2023—heighten price competition and margin pressure; reliance on a few high‑traffic channels raises concentration risk.
Any safety, contamination or misleading-claim incident—as seen during the 2022–23 US infant formula crisis—can trigger rapid consumer backlash and regulator scrutiny, especially in pediatric categories where media and authorities focus intensely. Negative social sentiment can cascade across core markets within hours, and recovery from trust shocks is typically slow and costly for brand equity and sales.
Regulatory tightening (2024) and cross‑border restrictions raise compliance costs and delay launches, risking faster cost growth than revenue. Macroeconomic pressure (IMF 2024 world GDP 3.1%, RMB ≈ -5% vs USD) and consumer downtrading threaten premium sales. Input volatility (commodity swings up to 30% in 2024), logistics delays (4–8 weeks) and platform fee/algorithm shifts (Amazon ~38% US share; fees up to 45%) compress margins.
| Risk | Key metric |
|---|---|
| Regulation | 2024 updates, cross‑border limits |
| Macro | IMF growth 3.1% / RMB ≈ -5% |
| Input/logistics | Price swings ≤30% / delays 4–8w |
| Channels | Amazon ~38% / fees ≤45% / private labels ~18% |


