
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
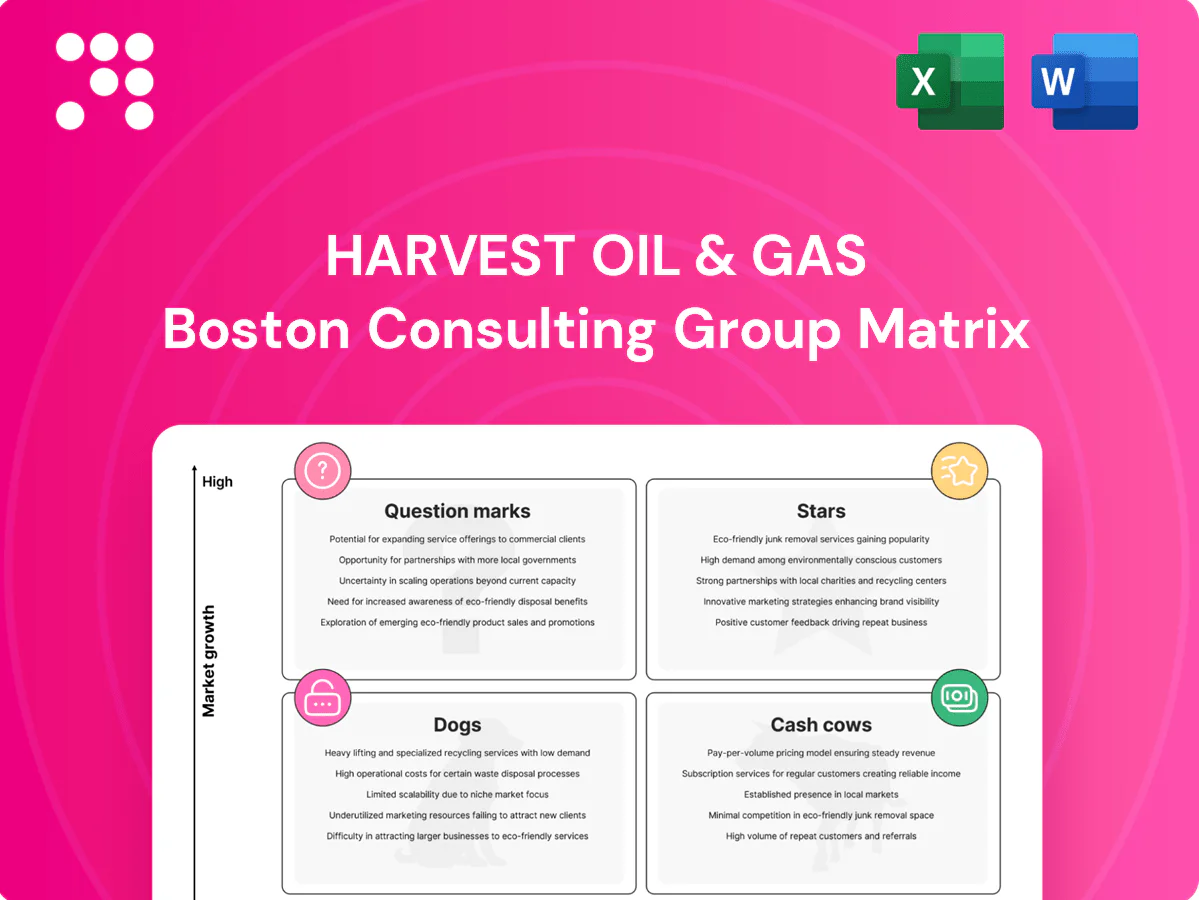
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Harvest Oil & Gas sits at a crossroads — some assets are steady cash drivers, others need bold reinvestment, and a few are draining value. This snapshot teases the quadrant placements; the full BCG Matrix gives you the exact map, data points, and practical moves to act on. Buy the complete report for a downloadable Word analysis and an Excel summary that lets you present, prioritize, and allocate capital with confidence.
Assets in proven basins where Harvest holds meaningful scale sit here, delivering double-digit production gains and local leadership on uptime, LOE, and wellwork cadence. Growth and share move together as operational outperformance fuels volume expansion. Reinvestment is heavy—cash in equals cash out today—so keep feeding these plays. With continued capex they graduate into dependable cash cows.
When systematic recompletions and artificial-lift tweaks consistently beat type curves, that’s star material: Harvest’s 2024 workover program reported IRRs exceeding 50% and average first-year production uplifts near 30%, per company disclosures. The team’s operational muscle turns tired wells into fast growers, reinvesting proceeds to scale the program. It soaks cash as the crew keeps rolling the program; maintain share and pace, and growth should normalize into steady cash flow later.
Development pads in the best rock, already held by production, can put Harvest at the front of the pack. 2024 Permian pad-drilling analyses show cycle times compress 25-40% and cost per lateral falls roughly 20-30%. Micro-market share can rise about 10-15% versus single-well programs. The catch: continuous capital is required while the window stays hot.
Midstream-light, takeaway-rich clusters let Harvest ramp volumes without bottlenecks, capturing local share and realizing premiums as US crude production averaged about 12.3 million b/d in 2024; operational connectivity drove rapid regional volume growth and higher realizations. Growth is rapid and capex-heavy, matching a classic Star profile in the BCG Matrix.
Data-driven decline arrest using surveillance, SCADA and targeted chemistry can reduce area declines from roughly 25%/yr to about 10–15% and uplift EURs 10–30% (2024 industry ranges), combining growth and competitiveness; analytics, pilots and specialist crews cost roughly $0.5–2.0M per pilot plus $50–150k per well in field labor, so stay invested until cashflow and payback (often 12–24 months) soften the curve.
Harvest Stars: high-growth, high-capex assets delivering double-digit volume gains and >50% workover IRRs; reinvestment keeps them cash-neutral until they mature into Cash Cows. Pad-drill and recomplete programs cut cycle times 25–40% and lift first-year output ~30%, paybacks ~12–24 months. Maintain pace to secure local share and premium realizations.
| Metric | 2024 value |
|---|---|
| Workover IRR | >50% |
| 1st‑yr uplift | ~30% |
| US prod | 12.3 MMb/d |
| Payback | 12–24 months |
 Detailed Word Document
Concise BCG Matrix review of Harvest Oil & Gas, mapping Stars, Cash Cows, Question Marks and Dogs with investment and divestment advice.

 Customizable Excel Spreadsheet
One-page BCG matrix showing Harvest Oil & Gas units by quadrant—clean, presentation-ready for quick C-suite decisions.
Older fields with predictable declines of roughly 3–8%/yr and high working interest (often 70–100%) quietly mint cash; modest capex (commonly under $10–30/boe) and routine ops keep unit costs low. Strong operating margins (typically 40–60% in mature basins at $60–80/bbl) fund G&A, debt service and dividends. Milk carefully; maintain reserves and spend enough on maintenance to avoid steeper declines.
Hedged base production converts volatile spot swings into predictable cashflow by locking volumes with financial and physical hedges, delivering low growth but high certainty that funds higher-return exploration and development without earnings drama; maintain strict hedge discipline and 24/7 uptime to protect margins and liquidity.
Waterfloods at steady state deliver bankable secondary recovery: 2024 industry averages show incremental recovery gains of about 10–15% once patterns are optimized, producing stable barrels rather than spikes. Injection patterns are fixed, opex is predictable—typical operating costs run roughly $8–12/boe in mature US plays (2023–2024 data). Surprises are rare, so capital intensity falls and free cash flow stacks up. Keep facilities tight and cash flows pile up predictably.
Cost-advantaged gathering ties give Harvest long-term midstream terms that lock in netbacks on essentially flat volumes; with global oil demand ~101.3 million b/d in 2024 (IEA) midstream utilization remains high, so market maturity lets economics defend market share. Minimal reinvestment is required, making these assets ideal to harvest for corporate cash needs and debt reduction.
Low-opex gas hubs: concentrated assets with shared compression and lean crews deliver margins even at modest prices; Henry Hub averaged 2.97/MMBtu in 2024. Growth isn’t the play; efficiency is — hubs produce repeatable free cash flow quarter after quarter. Use proceeds to back Stars and prune Dogs, prioritizing CAPEX on high-return liquids or core gas pockets.
Older fields (WI 70–100%) yield steady cash with declines ~3–8%/yr; opex ~$8–30/boe keeps margins ~40–60% at $60–80/bbl. Hedged base + waterfloods convert volatility to bankable cash; Henry Hub 2024 avg 2.97/MMBtu, global oil demand ~101.3 mb/d (IEA 2024).
| Metric | 2024 |
|---|---|
| Decline rate | 3–8%/yr |
| Opex | $8–30/boe |
| Margins | 40–60% |
| HH | $2.97/MMBtu |
The file you’re previewing is the exact Harvest Oil & Gas BCG Matrix you’ll get after purchase. No watermarks, no demo text—just the finished, fully formatted report ready for use. It’s built for strategic clarity and quick presentation to your team or investors. After buying, the same editable file is yours to download and deploy immediately.
Small, isolated non-core leases carry negligible scale and drag down corporate returns, often contributing imperceptibly versus US crude output of about 12.5 million b/d in 2024 (EIA). Located in low-growth pockets, they do not move the needle on production or valuation. High crew travel and parts logistics materially compress margins. Prime candidates for divestiture or shut-in to streamline portfolio.
High-LOE stripper wells (defined as ≤10 bbl/d) for Harvest Oil & Gas show lifting costs eclipsing realized price, leaving little growth and low portfolio share; constant workovers create a cash-trap dynamic. With per-well economics negative, management must consider exit or batch plug to stop the bleed and reallocate capital to accretive assets.
Regulatory friction and high compliance overhead are eroding already thin margins for Harvests regulatory-heavy edge assets, making permit delays and monitoring costs material P&L drags. Market growth in these basins is effectively flat and Harvest lacks negotiating leverage, so turnarounds are expensive and slow. Capital is better redeployed to higher-growth, lower-compliance segments.
Bottlenecked gas with poor pricing: if takeaway is constrained and basis blows out, volumes don’t translate to value. In 2024 Permian basis widened to roughly -$4 to -$7/MMBtu versus Henry Hub, compressing realized gas revenue and delivering no growth, no share, just headaches. Midstream renegotiation is unlikely near term; consider sale or suspension.
Legacy zones with old casing at Harvest show recurring failures and downtime that chewed cash in 2024, with remediation capex and lost production contributing to a >25% rise in per-well OPEX versus newer assets. Fields are flat to declining and Harvest is not the local leader; repeated turnarounds burn cash and time without ROI, so divest, salvage equipment, and redeploy capital.
Non-core, low‑rate leases and high‑LOE stripper wells are cash drains with no growth or share; 2024 US crude ~12.5M b/d and US dry gas ~100 Bcf/d, Permian basis -$4 to -$7/MMBtu compress realized revenue. Legacy casing and compliance raise OPEX >25% and downtime >25%; priority: divest, suspend, salvage capital.
| Metric | 2024 | Impact | Action |
|---|---|---|---|
| OPEX upswing | +25% | Negative cashflow | Divest |
| Permian basis | -$4 to -$7/MMBtu | Lower gas value | Suspend/sell |
Newly acquired bolt-ons: fresh positions in known basins with limited current share (typically <5%) but real upside if near-field appraisal succeeds; first 90-day integration and fixes (operations, choke/settings, recompletions) are critical. A focused capital push and management attention in that 0–90 day window can re-rate returns; decide to invest hard or sell fast—no drifting.
Undeveloped benches show promising logs but light completion history; regional unconventional play production grew about 3% CAGR in 2024 while Harvest’s current share remains tiny at roughly 0.5% of the basin. Pilot 2–3 appraisal wells (typical capex $5–7m per well) to prove EURs and cash returns. If pilots deliver IRR >20% and payback <3 years, scale to star; if not, exit and redeploy capital.
Old Harvest wells with refrac potential could unlock high-growth upside: 2024 industry pilots report median initial production uplifts around 30% while refrac capital typically ranges $0.8–1.5M per well, making inventory cash-hungry and returns still uncertain on this rock. Run a tight 6–12 well test program with strict KPIs, then scale only if NPV and IRR targets are met; go big or go home.
Facility debottleneck initiatives are Question Marks: 2024 industry analyses show typical throughput gains of 3–12%, which could lift cluster volumes and market share if execution succeeds. Execution risk is material; failed upgrades are sunk costs that erode returns. Greenlight phased upgrades with fast kill switches and go/no-go gates to cap downside.
Emerging gas-to-market options: prospective buyers or pipeline/tolling connections could lift realizations, but no contracts are signed; Harvest’s marketed volumes remain small versus regional flows. High effort with uncertain payoff — push negotiations aggressively and commit only when clear netback gains exceed development and tolling costs. IEA reports global gas demand rose ~1% in 2024; Henry Hub averaged about 2.85 USD/MMBtu in 2024.
Bolt-on targets (share <5%) need 0–90 day fixes; push or divest. Pilot 2–3 wells ($5–7m each) for benches; target IRR >20% and payback <3y. Refrac tests ($0.8–1.5m) and phased facility upgrades (3–12% throughput upside) require strict go/no-go gates; secure firm offtake before capex.
| Opportunity | 2024 benchmark | Harvest share | Capex | KPI |
|---|---|---|---|---|
| Bolt-ons | — | <0.5–5% | $1–7m | 0–90d fixes |
| Pilots | 3% basin CAGR | 0.5% | $5–7m/well | IRR>20% |


