
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Identiv faces moderate buyer power, niche supplier dynamics, and evolving substitute threats as IoT and security convergence reshape its market; competitive rivalry is tempered by specialized tech and certification barriers. This snapshot highlights key pressures but only scratches the surface—unlock the full Porter's Five Forces Analysis for detailed ratings, visuals, and actionable strategy insights.
RFID/NFC and secure element chips are sourced from a concentrated set of vendors such as NXP, Infineon and STMicro, giving suppliers heightened leverage over pricing and allocation. Lead times commonly range 12–24 weeks, and node constraints can force price pass-throughs that affect Identiv’s margins. Long-term supply agreements and second-sourcing materially reduce but do not eliminate this dependency. Supplier roadmaps directly constrain Identiv’s product feature timing and release cadence.
High-performance substrates, adhesives and antennas are niche inputs with a small pool of qualified suppliers, constraining Identiv's ability to substitute quickly and raising supplier bargaining power. Quality and yield standards in 2024 kept switching costs high, making rapid supplier changes impractical. Volume commitments and co-development secure capacity but create supplier lock-in, while 2024 material price volatility squeezed margins on large tag programs.
Proprietary SDKs, cryptographic libraries and certifications bind Identiv products to specific suppliers; licensing terms and vendor update cycles materially affect cost and time-to-market. Security compliance demands tight alignment with vendor IP; switching core stacks risks re-certification and integration delays—Common Criteria often 6–18 months and FIPS 140-2/3 6–24 months.
Identiv's reliance on EMS/ODM partners gives scale but raises supplier leverage during tight capacity cycles, with geographic concentration creating geopolitical and logistics vulnerability; dual-site qualification reduces outage risk but increases overhead and BOM management complexity, while incumbent manufacturers benefit from yield learning curves and proprietary process knowledge that raise switching costs.
Reliance on cloud, connectivity modules, and PKI services creates ongoing supplier touchpoints for Identiv; with 92% of enterprises using cloud (Flexera 2024), API changes and pricing shifts can quickly ripple into total cost of ownership and device lifecycle costs. SLAs and redundancy reduce outage risk but raise recurring spend. Vendor ecosystems subtly shape product roadmaps and integration timelines.
Identiv faces high supplier leverage from concentrated chip vendors (NXP, Infineon, STMicro) and EMS/ODM partners, with lead times of 12–24 weeks pressuring margins. Niche substrates, adhesives and antennas limit substitution; switching risks re-certification (Common Criteria 6–18 months; FIPS 140-2/3 6–24 months). Cloud/API dependency (92% enterprise cloud adoption, Flexera 2024) raises TCO and ongoing vendor risk.
| Risk | Metric/2024 |
|---|---|
| Chip lead time | 12–24 weeks |
| Cloud adoption | 92% (Flexera 2024) |
| Re-certification | Common Criteria 6–18m; FIPS 6–24m |
 Detailed Word Document
Uncovers key drivers of competition, customer influence, supplier power, and market entry risks tailored exclusively to Identiv, identifying disruptive threats, substitutes, and strategic levers to protect market share and profitability.

 Customizable Excel Spreadsheet
One-sheet Porter's Five Forces for Identiv that visualizes competitive pressure with a radar chart, lets you customize intensity by scenario, and exports cleanly into decks—no macros or finance expertise required.
Enterprise and government RFPs push strong price pressure through competitive tenders, and in 2024 multi-year, multi-site contracts gave buyers outsized negotiation leverage over suppliers like Identiv. Customers increasingly require compliance proof and successful pilots before award; framework agreements commonly exchange lower unit prices for predictable volumes and renewal options.
Installed access control hardware, badges and back-end integrations create inertia for Identiv customers, with the company reporting fiscal 2024 revenue of about $111 million, underscoring a large installed base that raises switching costs. Credential migration complexity and downtime risks deter change, softening buyer power as enterprises avoid disruptive transitions. Standards-based systems (OSDP, mobile credentials) allow gradual vendor diversification, but stringent service-level expectations and support needs still force concessions to incumbent suppliers.
RFID/NFC tags bought in the millions are highly price elastic; in 2024 per-unit prices commonly range from $0.03 to $0.12 depending on volume and form factor. Buyers aggressively benchmark per-unit costs across suppliers while total program value is driven more by yield, read rates and logistics than headline tag price. Differentiation in form factor and reliability can justify modest premiums of roughly 5–15%.
Buyers demand certifications, audits and data protection assurances because non-compliance risks costly breaches; IBM's 2024 Cost of a Data Breach Report cites an average breach cost of about $4.45 million, so meeting SOC 2/ISO 27001 narrows substitutes and reduces buyer leverage. Failure to comply can exclude vendors entirely, while ongoing patching and support commitments remain key negotiation levers.
Customers in 2024 expect seamless interoperability across IT, identity, and building systems; enterprise surveys show over 70% now view open APIs as essential for procurement. Open APIs and partner ecosystems reduce vendor lock-in and expand buyer options, while deep integrations create soft lock-in as substitution costs rise. Bundling professional services can shift negotiating power back toward Identiv by increasing switching costs and recurring revenue.
Enterprise/government RFPs and multi‑site 2024 contracts give buyers strong price leverage; Identiv reported FY2024 revenue ~$111M and a large installed base raising switching costs. RFID tags (2024) cost $0.03–$0.12 each and are heavily benchmarked; >70% of enterprises require open APIs. Compliance (SOC2/ISO27001) and SLAs favor incumbents.
| Metric | 2024 Value |
|---|---|
| Identiv FY2024 Revenue | $111M |
| RFID per‑unit price | $0.03–$0.12 |
| Enterprises requiring open APIs | >70% |
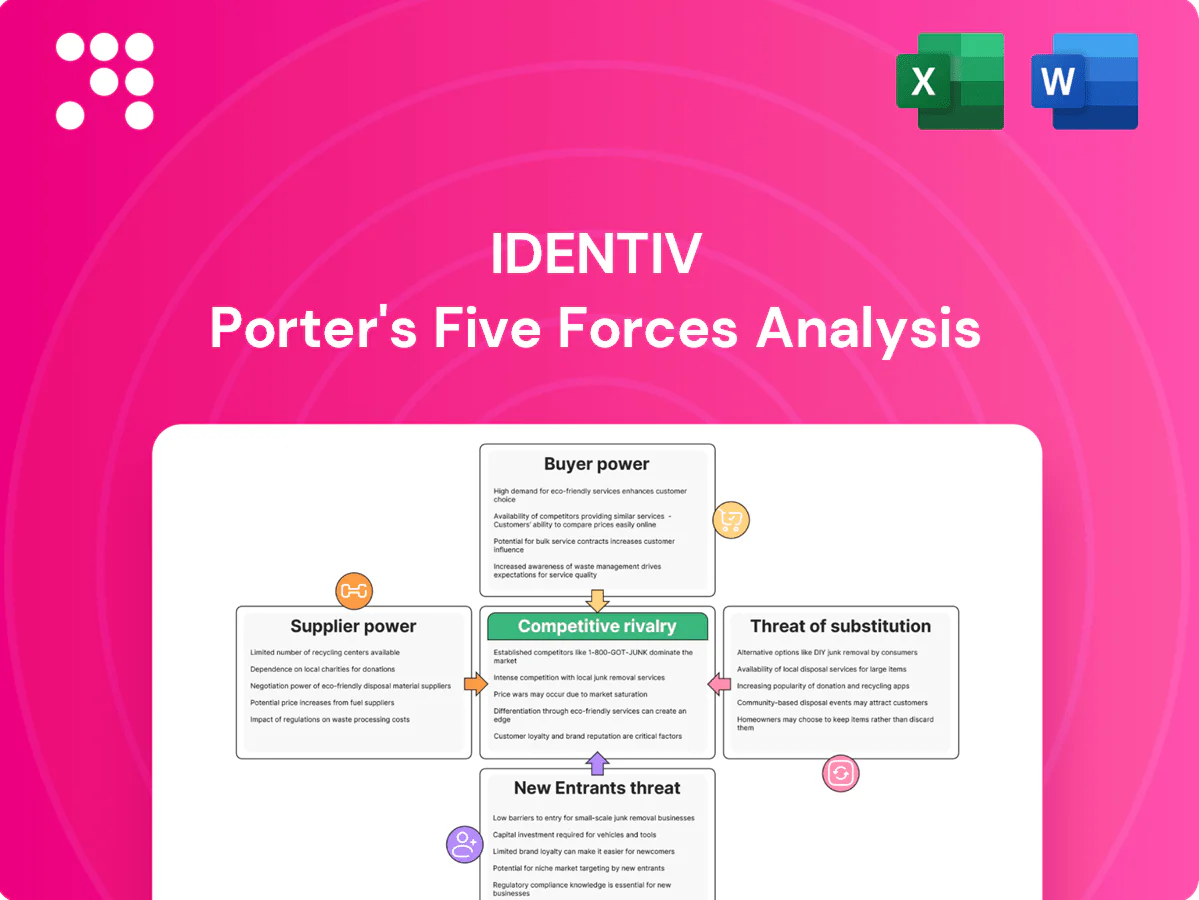
This preview shows the exact Identiv Porter's Five Forces Analysis you'll receive—no placeholders or mockups. It is the full, professionally written file covering threats of new entrants, supplier and buyer power, substitute threats, and competitive rivalry. After purchase you'll get immediate access to this same ready-to-use document. Use it for decision-making, valuation, or strategy without further setup.
Global brands in physical access, RFID, and identity intensify competition in a combined market with an estimated 2024 TAM of about USD 25 billion, forcing incumbents to defend share. Rivals span hardware, software, and services, compressing hardware margins and shifting revenue toward higher-margin services. Brand trust and certifications such as FIPS/ISO often determine procurement, while extensive channel reach wins in fragmented geographies.
Compliance with ISO/IEC 14443, ISO/IEC 27001 and NFC Forum specifications by 2024 has narrowed feature gaps across access and smart-card offerings, leading buyers to view solutions as comparable and intensifying price-based rivalry. Vendors now compete on reliability, systems integration and total cost of ownership, while rapid feature catch-up compresses innovation windows and shortens product differentiation cycles.
Competitors bundle access control, credentials, analytics and cloud management into integrated platforms, a trend tied to a global physical access control market estimated at about $8.2 billion in 2024 and growing into cloud services.
Platforms create customer lock-in and higher switching costs; cloud/subscription offerings accounted for roughly 30% of vendor revenue mix in 2024, pressuring pure hardware margins.
Identiv must pair devices with software and managed services to protect gross margins and drive recurring revenue, matching industry moves toward bundled platform ARR growth.
Advances in edge computing, mobile credentials and AI raised buyer expectations in 2024, with edge deployments up ~30% year-over-year; monthly to quarterly release cycles favor well-capitalized rivals while certification lead times of 3–9 months slow smaller players; strategic partnerships and OEM deals can cut time-to-market by roughly 25–35%, intensifying competitive pressure on Identiv.
Aftermarket and service competition is shaped by system integrators who steer vendor selection and capture lifecycle revenue, making Identiv's channel relationships critical; service quality, SLAs, and clear upgrade paths are primary retention levers. Third-party maintenance options increasingly threaten captive service margins, while training and enablement strengthen defense of the installed base.
Global competition in access/ID (2024 TAM ~$25B; PACS ~$8.2B) compresses hardware margins and forces platform+service bundling; cloud/subscription was ~30% of vendor revenue in 2024. Edge adoption grew ~30% YoY, certification lags 3–9 months, partnerships cut time-to-market ~25–35%, raising pressure on Identiv to drive ARR and integrate services.
| Metric | 2024 |
|---|---|
| TAM | $25B |
| PACS | $8.2B |
| Cloud rev mix | 30% |
| Edge growth | ~30% |
Smartphone-based access and NFC wallets pose a clear substitute to physical badges as global smartphone users reached about 6.8 billion in 2024 and over 80% of devices ship with NFC, expanding addressable users. Convenience and remote provisioning drive enterprise uptake, especially for hybrid workforces. Hardware readers have largely added mobile support, but overall badge volumes are likely to decline as mobile adoption rises. Adoption speed hinges on demonstrable security parity with badges.
Biometrics and computer vision threaten card-based access as fingerprint, face, and vision-based tags enable bypassing cards and fobs; global biometric deployments expanded sharply in 2024 with enterprise pilots and edge-camera rollouts. Touchless experiences and immutable audit trails increase adoption, while privacy, bias, and spoofing concerns—cited in 2024 regulatory guidance—temper full substitution. Hybrid deployments remain common, slowing immediate displacement as organizations phase in biometrics alongside cards.
BLE beacons and UWB present clear substitutes, offering battery-powered, low-infrastructure location and access alternatives; BLE gives meter-level accuracy while UWB delivers centimeter-class (≈10–30 cm) precision. Battery form factors cut deployment costs versus wired readers. Ecosystem fragmentation and proprietary stacks slow cross-vendor standardization. In dense, multipath environments BLE accuracy degrades markedly while UWB generally maintains viability.
Low-cost barcodes and QR codes substitute for many RFID cases by trading automation speed for simplicity and price; printed QR/barcode labels cost under 0.01 USD each versus passive RFID averages of 0.05–0.20 USD in 2024. Line-of-sight constraints limit throughput and reliability, while RFID can read hundreds of tags per second and supports non-line-of-sight bulk scanning, so for high-volume logistics RFID retains clear advantages.
Physical guards, keys and sign-in logs can substitute digital access at small scale, but U.S. security guard mean wage (~$36,000/yr, BLS 2024) and human error (Verizon 2024: 82% of breaches involve a human element) make manual approaches costly and risky; compliance (GDPR, HIPAA) pushes digitalization, while budget cycles can delay tech adoption.
Smartphone/NFC (6.8B users, ~80% NFC devices in 2024) and mobile provisioning accelerate badge substitution; biometrics expand in enterprises but privacy/regulatory guidance limits full swap; BLE/UWB and QR/barcode undercut RFID on cost and form factor (QR <0.01 USD vs RFID 0.05–0.20 USD in 2024); manual guards remain costly (~36k/yr) and error-prone (82% breaches involve humans, 2024).
| Substitute | 2024 metric | Impact |
|---|---|---|
| Mobile/NFC | 6.8B users; ~80% NFC | High adoption, badge decline |
| Biometrics | Enterprise pilots↑ | Partial replacement, regulatory friction |
| UWB/BLE | UWB 10–30cm; BLE meter-level | Location alternatives |
| QR/barcode | Cost <0.01 USD | Low-cost, low-throughput |
| Manual | ~36k/yr; 82% human breaches | Small-scale, high risk |
Security certifications and government approvals commonly take 6–24 months and cost $100k–$500k, creating steep upfront investment; buyers routinely demand multiple third-party audits and proven references; new entrants face 12–24 month sales cycles without those references; in critical infrastructure, established trust acts as a durable moat, locking customers into vendors for 3–5 years.
Hardware R&D, tooling and inventory in secure ID and access devices require upfront capital often in the low- to mid-millions of dollars for product development and manufacturing setup.
Building global service and support networks adds substantial recurring costs—logistics, certified technicians and warranty infrastructure—that elevate break-even thresholds for new entrants.
Incumbents achieve economies of scale that can reduce component costs by roughly 20–30% on high-volume contracts, making it difficult for entrants to match pricing on large-volume deals.
Complex standards and legacy integrations raise technical hurdles for newcomers, with many projects requiring multi-protocol support (OSDP, Wiegand, ONVIF) and legacy system adapters. Failing interoperability tests routinely blocks deployments and increases return-to-vendor cycles. Open standards lower some barriers but force head-to-head comparisons, while certification lead times of roughly 3–12 months slow market entry.
Cloud-native platforms and mobile-first access have cut software-layer entry barriers, supporting faster rollouts; industry reports show roughly 70% enterprise cloud adoption by 2024, increasing addressable market for software entrants.
ODM hardware and white-label readers accelerate time-to-market, while end-to-end security assurance remains difficult and costly, limiting full displacement of incumbents.
Hybrid on-prem/cloud models let software entrants nibble share—channeling upgrades rather than outright replacements—and sustainable revenue mixes for incumbents.
High certification and approval costs (6–24 months; $100k–$500k) plus 12–24 month sales cycles and requirement for references create steep entry hurdles. Hardware R&D and tooling demand low- to mid‑million capital; incumbents' scale cuts component costs ~20–30%. Channel control and global service networks amplify break-even thresholds despite 70% enterprise cloud adoption in 2024.
| Barrier | Impact | Metric (2024) |
|---|---|---|
| Certifications | Long lead, high cost | 6–24 months; $100k–$500k |
| Hardware capex | High upfront | Low–mid millions |
| Channel | Entrenched wins | Market $11.5B |
| Cloud | Lower SW barriers | 70% adoption |


