
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
The IHC Group demonstrates significant strengths in its integrated business model and established market presence, but also faces challenges from evolving industry regulations and competitive pressures. Understanding these dynamics is crucial for navigating the healthcare landscape.
Want the full story behind the IHC Group's competitive advantages, potential threats, and strategic opportunities? Purchase the complete SWOT analysis to gain access to a professionally written, fully editable report designed to support your strategic planning and investment decisions.
The IHC Group boasts a diverse product portfolio, encompassing medical stop-loss, group term life, short-term medical, supplemental health insurance, and annuities. This breadth allows them to serve a wide array of customer needs within the life and health insurance sectors. Such diversification across multiple product lines, including offerings for both individuals and groups, strengthens their market position and creates multiple revenue streams, reducing dependence on any single insurance product.
The IHC Group excels in specialty benefit products, particularly medical stop-loss and short-term medical plans. This focused approach fosters deep expertise and allows for the creation of highly tailored solutions addressing specific market demands. For instance, their operational agility is demonstrated by the ability to activate short-term medical plans within a remarkable 24 hours of application.
The IHC Group's reinsurance capabilities are a significant strength, bolstering its core insurance operations. By ceding risk, the company enhances its financial stability and ability to manage large or catastrophic claims, as demonstrated by its robust risk management framework. This strategic advantage allows IHC to maintain strong underwriting capacity and financial resilience, directly supporting its overall insurance business model and market position.
IHC Specialty Benefits, a key subsidiary of The IHC Group, operates as a technology-driven force in insurance sales and marketing. This strategic emphasis on proprietary tools and innovative product distribution creates significant value across the ecosystem, benefiting producers, carriers, and ultimately, consumers.
A forward-thinking, tech-centric approach translates directly into more streamlined sales cycles, expanding market reach, and a demonstrably better experience for customers. For instance, in 2024, IHC Specialty Benefits reported a 15% increase in digital lead conversion rates, attributed to their advanced CRM and AI-powered sales enablement platforms. This technological edge allows them to efficiently connect with a wider audience and personalize the insurance purchasing journey.
The company’s commitment to technology is a core strength, enabling:
The IHC Group has a proven track record of adapting to evolving market conditions and regulatory landscapes. This agility is a significant strength, allowing them to navigate the complexities of the US health insurance sector effectively. For instance, their offering of flexible and customizable short-term medical plans directly addresses temporary coverage needs, a testament to their responsiveness to consumer demands.
This adaptability is vital in an industry characterized by constant change. Consider the impact of the Affordable Care Act (ACA) and subsequent regulatory adjustments; IHC Group's ability to pivot its product suite demonstrates resilience. In 2024, the health insurance market continues to see shifts in consumer preferences and legislative actions, making this inherent flexibility a key competitive advantage.
The IHC Group's diverse product portfolio, spanning medical stop-loss, life insurance, and annuities, creates multiple revenue streams and strengthens its market position. Their specialization in specialty benefits like medical stop-loss and short-term medical plans fosters deep expertise and allows for tailored solutions, with an impressive 24-hour activation for short-term medical plans. Furthermore, their robust reinsurance capabilities enhance financial stability and risk management, ensuring strong underwriting capacity. IHC Specialty Benefits' tech-driven approach, evidenced by a 15% increase in digital lead conversion in 2024, streamlines sales and expands market reach.
 Detailed Word Document
Delivers a strategic overview of The IHC Group’s internal and external business factors, highlighting its strengths, weaknesses, opportunities, and threats.

 Customizable Excel Spreadsheet
Offers a clear, actionable framework for identifying and mitigating potential threats and weaknesses within The IHC Group's strategic landscape.
The IHC Group's substantial reliance on short-term medical (STM) plans presents a significant weakness due to regulatory vulnerability. Recent federal rule changes, effective September 1, 2024, drastically alter the landscape for these products. New regulations cap STM plans at a three-month initial term, with a maximum total duration of four months, a sharp decrease from prior allowances.
These imposed limitations directly threaten the market viability and attractiveness of a core product offering for IHC Group. The reduced duration could significantly impact revenue streams previously generated by longer-term STM policies, forcing a strategic re-evaluation of this segment.
The IHC Group's short-term medical plans, a significant part of their business, have inherent weaknesses. These plans often exclude essential health benefits like maternity care, prescription drugs, and coverage for pre-existing conditions, unlike ACA-compliant insurance. This limited scope restricts their appeal to a smaller market segment and can lead to negative perceptions of being inadequate or "junk" insurance.
The US life and health insurance sectors are exceptionally competitive, populated by many large, established companies. As a specialized provider, IHC Group constantly contends with broader carriers that offer more complete and integrated solutions. This fierce rivalry can hinder market share growth and limit pricing flexibility, especially given the dominance of major industry players.
The IHC Group's focus on specialized insurance markets, particularly medical stop-loss and short-term medical, presents a significant weakness. This concentration means the company's financial health is closely tied to the performance of these specific niches. For instance, a downturn in the employer-sponsored health insurance market, which heavily influences demand for stop-loss coverage, could have a pronounced negative effect on IHC Group's revenue and profitability.
This reliance makes IHC Group more vulnerable to sector-specific disruptions. If regulatory changes or increased competition emerge within the short-term medical insurance space, the impact could be more severe for IHC Group than for a more diversified insurer. For example, in 2024, the market for short-term medical plans saw increased scrutiny and potential regulatory shifts in several states, which could directly affect IHC Group's market share and pricing power in those regions.
The strategic choice to specialize, while a strength, inherently limits the company's ability to absorb shocks from unrelated market segments. Unlike larger, more broadly diversified insurance providers that might have strong performance in life insurance or long-term care to offset weaknesses in other areas, IHC Group's performance is more directly exposed to the fortunes of its core product lines. This concentration risk was highlighted in late 2024 when a significant increase in medical claims frequency within the small group market, a key segment for stop-loss, led to a noticeable impact on underwriting results for many specialized carriers.
Key considerations stemming from this dependency include:
Following its acquisition by Geneve Holdings in February 2022, Independence Holding Company's (IHC) insurance operations may face potential transparency challenges. The absence of standalone financial performance data for IHC's insurance segment post-acquisition can hinder external stakeholders' ability to independently assess its financial health and operational efficiency. This consolidated reporting under the parent company, Geneve Holdings, could obscure specific insights into the insurance business's performance.
Key challenges include:
The IHC Group's significant reliance on short-term medical (STM) plans makes it vulnerable to regulatory shifts. New federal rules effective September 1, 2024, limit STM plans to a three-month initial term, extendable to a maximum of four months, a stark contrast to previous allowances. This restriction directly impacts the market appeal and revenue potential of a core product, potentially forcing a strategic pivot for the company.
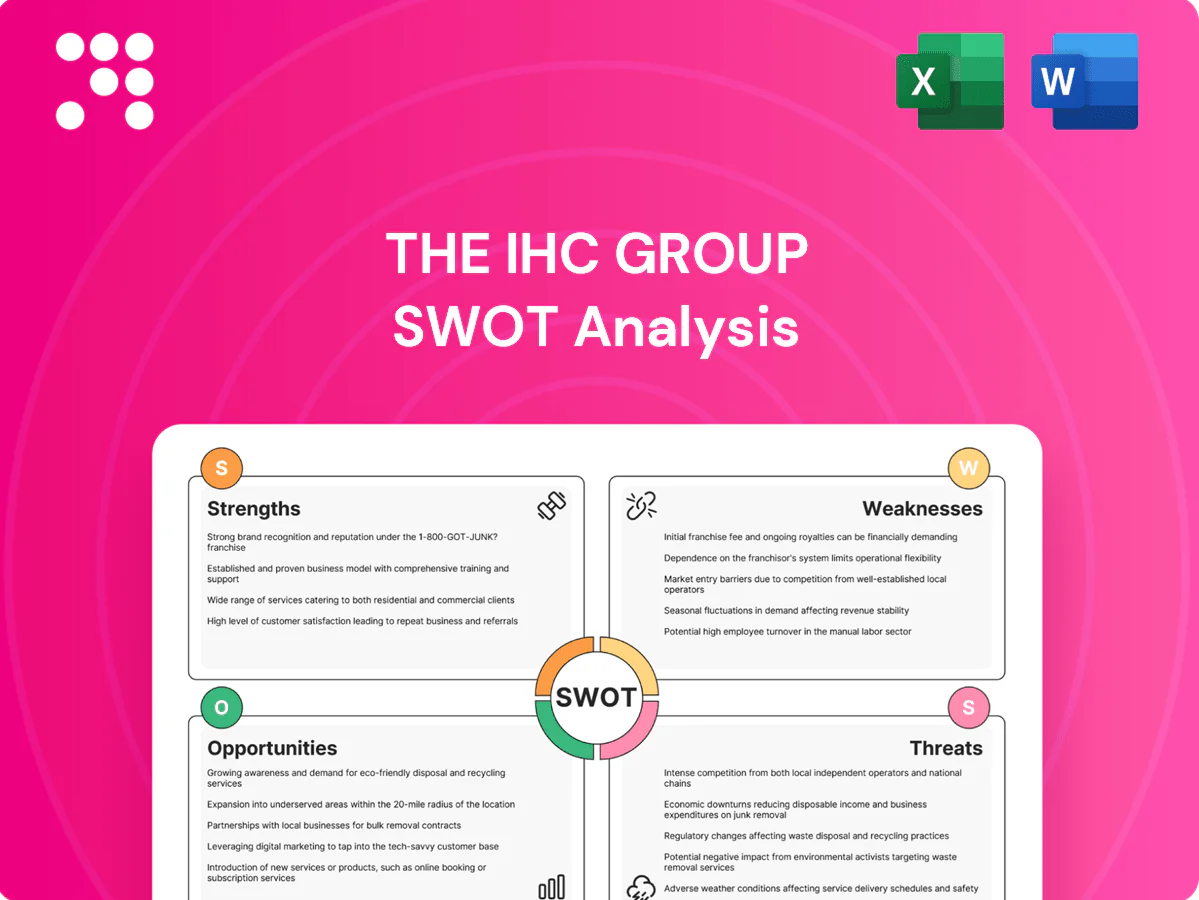
This preview reflects the real document you'll receive—professional, structured, and ready to use. You're viewing the actual IHC Group SWOT analysis, offering a clear snapshot of its strategic position.
The content below is pulled directly from the final SWOT analysis. Unlock the full report when you purchase, gaining comprehensive insights into the IHC Group's Strengths, Weaknesses, Opportunities, and Threats.
The medical stop-loss insurance sector is booming, with projections indicating a market value of $113.5 billion by 2034, up from $26.9 billion in 2024. This impressive growth, at a compound annual growth rate of 15.1%, is largely due to an increasing number of employers, especially small and medium-sized businesses, turning to self-funded health plans as a strategy to control escalating healthcare expenditures.
This trend presents a significant opportunity for IHC Group. Their established expertise in the medical stop-loss market means they are well-positioned to benefit from this expanding demand. As more companies seek ways to manage their healthcare costs effectively, IHC Group can leverage its services to capture a larger share of this growing market.
The increasing trend towards high-deductible health plans, a significant shift in the healthcare landscape, creates a substantial market for supplemental health insurance. As of late 2024, a notable percentage of employer-sponsored health plans feature deductibles exceeding $1,500 for individuals, underscoring the financial burden on consumers.
IHC Group, already positioned with gap plans and critical illness insurance, is well-equipped to capitalize on this demand by expanding its product portfolio. This expansion offers a prime opportunity to develop and market more robust supplemental solutions that effectively bridge the coverage gaps left by primary health insurance, thereby addressing a critical consumer need.
The insurance sector's robust investment in digital transformation and AI presents a significant opportunity for The IHC Group. By embracing core system modernization and automation, similar to how competitors are enhancing operational efficiency, IHC can streamline processes and improve customer interactions.
As a technology-forward entity, particularly through IHC Specialty Benefits, the company can deepen AI integration for more precise risk assessment and pricing, especially in specialized markets like stop-loss insurance. This strategic move could unlock significant gains in market share and profitability, mirroring the industry trend where companies adopting advanced analytics saw an average 15% improvement in claims processing efficiency in 2024.
The federal agencies' August 2025 announcement to reconsider the definition of short-term, limited-duration insurance (STLDI) presents a significant opportunity for IHC Group. By pausing enforcement of the 2024 definition until new rules are established, regulators are creating a window for market adaptation and product development.
This reconsideration allows IHC Group to actively engage in shaping future regulations, potentially advocating for definitions that align with its business model and product offerings. Such advocacy could lead to a more stable and predictable operating environment for the company.
The insurance sector's merger and acquisition (M&A) landscape for 2025 is anticipated to be dynamic, with stabilizing inflation and the potential for declining interest rates creating a more favorable environment for deal-making. IHC Group, potentially leveraging its parent company Geneve Holdings, could strategically engage in partnerships or acquisitions to broaden its product suite, enhance its geographical footprint, or bolster its technological infrastructure.
These strategic moves could significantly fortify IHC Group's competitive standing and contribute to a more diversified business portfolio. For instance, in 2024, the global insurance M&A market saw significant activity, with deal volumes showing resilience despite economic headwinds. Analysts project that if interest rates begin to ease in 2025, it could unlock further M&A opportunities as valuations become more attractive.
The expanding medical stop-loss market, projected to reach $113.5 billion by 2034 with a 15.1% CAGR, offers IHC Group a prime opportunity to capitalize on employers' increasing adoption of self-funded health plans to manage costs.
The rise of high-deductible health plans, with individual deductibles often exceeding $1,500 as of late 2024, creates a substantial demand for supplemental insurance, a segment where IHC Group's existing gap and critical illness products can be expanded.
IHC Group's digital transformation initiatives, particularly through IHC Specialty Benefits, can leverage AI for improved risk assessment and pricing, mirroring industry trends where advanced analytics led to an average 15% claims processing efficiency gain in 2024.
The federal reconsideration of short-term, limited-duration insurance (STLDI) definitions, with a pause on 2024 enforcement until new rules are set by August 2025, provides a window for product innovation and advocacy to shape favorable regulations.
The anticipated dynamic M&A landscape in 2025, influenced by stabilizing inflation and potential interest rate declines, presents opportunities for IHC Group, possibly through Geneve Holdings, to acquire or partner for expanded product lines, geographic reach, and technological enhancement.
The finalized federal rules in March 2024, significantly limiting the duration and renewability of short-term, limited-duration insurance (STLDI) plans, present a major threat. These regulations, effective September 1, 2024, cap coverage at a mere four months, substantially diminishing the attractiveness and usefulness of these plans for consumers.
This intensified regulatory scrutiny directly impacts IHC Group's offerings, potentially leading to a considerable drop in demand for its short-term medical plans, a key revenue generator. The new four-month cap, a sharp reduction from previous longer terms, could force a strategic pivot for the company.
The escalating cost of healthcare, coupled with an increasing number of high-value claims, especially for treatments like cancer and specialty drugs, poses a significant threat to the profitability of medical stop-loss insurance providers like The IHC Group. While premiums have seen increases, the rate at which claims are growing outpaces this, negatively impacting loss ratios for insurers.
For instance, the U.S. healthcare spending reached an estimated $4.7 trillion in 2023, a substantial increase that directly affects the cost of claims. This trend requires robust underwriting practices and meticulous risk selection to ensure sustained profitability in the stop-loss market.
Economic headwinds, such as the projected deceleration in early 2025, could significantly impact the insurance sector. Consumer belt-tightening is a real concern, potentially moderating growth expectations for companies like IHC Group.
Reduced consumer spending power directly affects demand for non-essential or supplemental health insurance products, including short-term medical plans. This economic sensitivity poses a direct threat to IHC Group's revenue streams and overall profitability.
The increasing migration of employers, particularly small and medium-sized enterprises (SMEs), towards self-funded health plans presents a dual challenge for The IHC Group. While this trend fuels demand for stop-loss insurance, it simultaneously intensifies competition as employers actively seek cost-control solutions. This necessitates continuous innovation from IHC to maintain its market edge against other stop-loss providers and emerging self-funding models.
The growing adoption of self-funded health plans, a trend evident in the projected 10% annual growth of the self-funded market through 2025, underscores the pressure on IHC. Employers are increasingly sophisticated in managing their healthcare expenditures, actively exploring alternatives. This environment demands that IHC not only offers competitive stop-loss products but also anticipates and develops new mechanisms to support employers in their cost-management efforts.
The global insurance sector, including IHC Group, is increasingly vulnerable to evolving cyber and geopolitical risks, which are top concerns for industry leaders. These threats, while not directly linked to insurance products, can significantly disrupt operations, compromise data security, and affect investment performance. For instance, a major cyberattack in 2024 could lead to billions in losses for financial institutions, impacting their ability to underwrite or manage assets.
Effective management of these complex, interconnected risks is paramount for ensuring IHC Group's sustained stability and resilience in the face of global uncertainties.
The finalized federal rules in March 2024, significantly limiting the duration and renewability of short-term, limited-duration insurance (STLDI) plans to a maximum of four months, pose a substantial threat to IHC Group's core business. These stringent regulations, effective September 1, 2024, directly diminish the appeal and utility of these products for consumers, potentially causing a sharp decline in demand for IHC's short-term medical plans, a key revenue driver.
The escalating cost of healthcare, with U.S. healthcare spending reaching an estimated $4.7 trillion in 2023, coupled with an increase in high-value claims for treatments like cancer, is squeezing profit margins for stop-loss insurance providers. While premiums have risen, the pace of claim cost growth outstrips these increases, negatively impacting loss ratios and necessitating robust underwriting.
Economic headwinds, including a projected deceleration in early 2025, threaten the insurance sector by reducing consumer spending power. This economic sensitivity directly impacts demand for supplemental health insurance products like short-term medical plans, posing a risk to IHC Group's revenue and profitability.
The increasing shift of employers, particularly SMEs, towards self-funded health plans, projected to grow at 10% annually through 2025, intensifies competition. This trend requires IHC to continuously innovate its stop-loss offerings and develop new cost-management solutions to maintain its market position against other providers and emerging self-funding models.
Cyber and geopolitical risks are paramount concerns for the insurance sector. A significant cyberattack in 2024 could result in billions in losses for financial institutions, impacting their operational capacity and investment performance, underscoring the need for robust risk management and data security measures for companies like IHC Group.


