
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
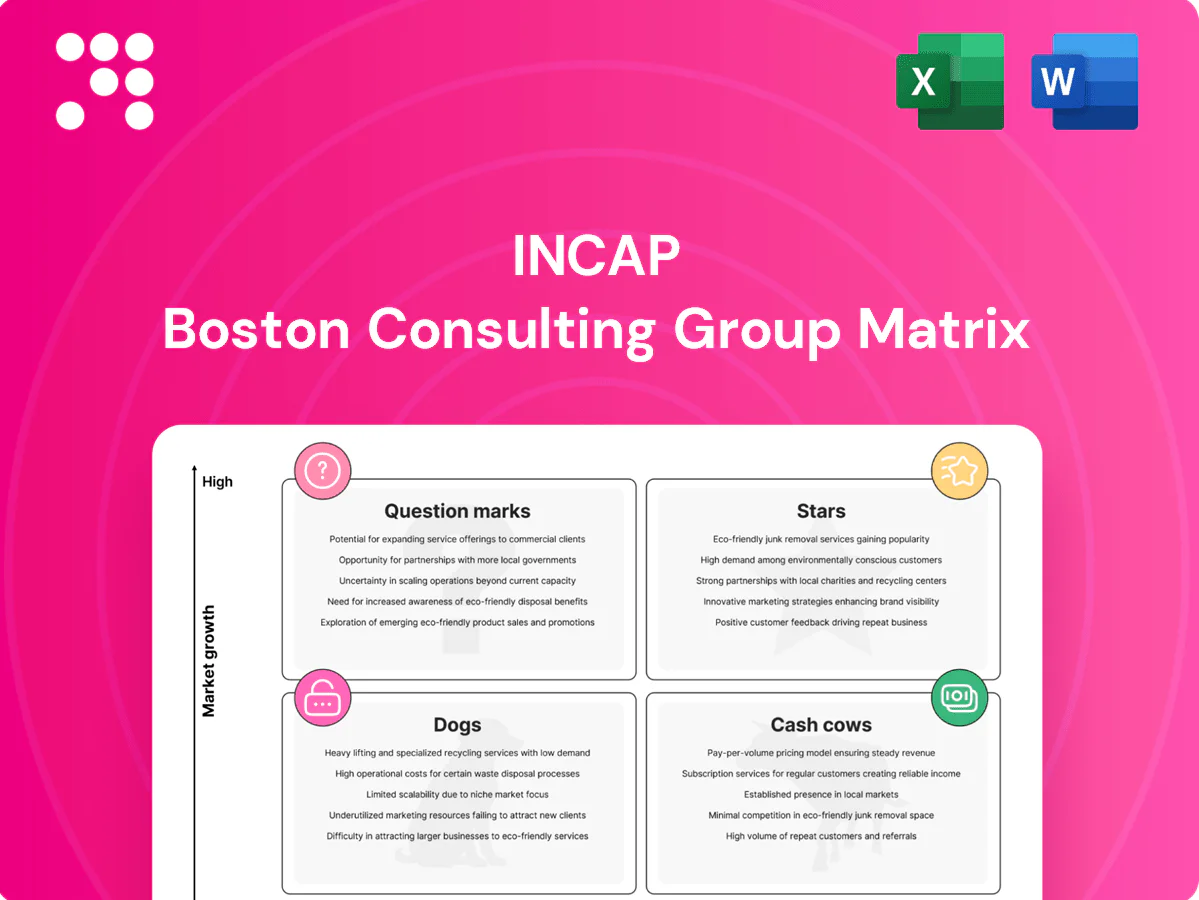
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
The Incap BCG Matrix snapshot shows where each product sits—Stars, Cash Cows, Dogs, or Question Marks—and teases the strategic moves beneath the surface. Want the full picture? Buy the complete BCG Matrix for quadrant-by-quadrant clarity, data-backed recommendations, and an actionable roadmap to reallocate capital and boost returns. You’ll get a polished Word report plus an Excel summary ready to present and use. Purchase now and ditch the guesswork—get strategic clarity fast.
High-growth OEMs building inverters, chargers and storage gear need fast, reliable EMS as EVs reached about 15% of global car sales in 2024. Incap’s superior quality and speed are winning share amid booming demand. Heavy promotion and rapid line ramping still soak cash, but the operational flywheel is spinning. Hold share now and this segment should convert to a strong cash engine as growth normalizes.
Connected sensors and gateways scale rapidly—about 15.9 billion connected IoT devices in 2024—driving demand for Incap’s smart-edge assemblies. Short product cycles (typical NPI-to-volume 6–12 months) suit Incap’s agile playbook. Keeping pace requires capex and engineering hours (industrial electronics capex often 3–6% of revenue), so cash in equals cash out; sustained leadership turns wins into steady, profitable runs.
MedTech compliant manufacturing occupies premium BCG Star positions as regulated builds with traceability and ISO 13485/QSR systems command higher slot pricing and long product lifecycles. Global medical device market growth is steady (roughly 5–6% CAGR in recent forecasts), and once qualified switching costs — validation, requalification and supplier audits — create strong retention. Audits and validations typically run into tens to low hundreds of thousands of euros per program, so continued investment to defend share converts these Stars into thick-margin staples.
Box-build for fast-scaling industrial OEMs positions Incap as a Star: full-system assembly shortens OEM time-to-market while deeper integration expands wallet share and customer lock-in; Incap reported 2024 group revenue 148.4 million EUR supporting this strategic ramping. Ramping demands working capital, extra testing capacity and skilled headcount, but protecting these accounts secures leadership in expanding niches.
Design-for-manufacture and NPI hubs give early engineering touchpoints that steer BOMs and improve yields; being first into hot specs often captures the factory and ~60% of downstream volume in many EMS wins, though hubs are resource-heavy and can break even only after series production.
High-growth OEM EV power, IoT edge, MedTech and box-build are Stars for Incap in 2024: 148.4m EUR revenue, EVs ~15% of global car sales 2024, 15.9bn IoT devices 2024. Fast ramping needs capex ~3–6% revenue and working capital but converts to cash engine as share holds.
| Segment | 2024 signal | Key metric |
|---|---|---|
| EV/ESS | High growth | 15% car sales |
| IoT edge | Scale | 15.9bn devices |
| MedTech | Premium | 5–6% CAGR |
 Detailed Word Document
Concise Incap BCG Matrix review: quadrant-by-quadrant insights on Stars, Cash Cows, Question Marks, Dogs and clear investment guidance.

 Customizable Excel Spreadsheet
One-page Incap BCG Matrix that clears portfolio clutter, highlights priorities, and exports cleanly to PowerPoint.
Legacy industrial control boards sit in the Cash Cows quadrant with mature demand, stable revisions and predictable forecasts; production lines are tuned, scrap is low and margins remain healthy. Minimal promotion is required—focus on flawless execution and continuous optimization. Milk the steady run-rate and invest in automation to convert operational efficiency into higher free cash flow.
Aftermarket and spare-part programs are low-growth (≈2–3% yearly) but produce long tails and a reliable reorder cadence, often representing ~15% of group revenue in 2024 for mid-size EMS players. Customers prioritize continuity over price fights, so maintaining 95%+ SLA compliance preserves annuity margins. Tight small-lot inventory discipline (6–8 turns) keeps costs low and protects gross margin.
Procurement and global sourcing services deliver volume leverage with vetted suppliers in a steady market, driving repeatable processes and strong purchase price variance capture that yields consistent savings. These operations show limited growth potential but are highly cash generative, supporting free cash flow. Maintain tight supplier scorecards and harvest margins through disciplined contract management.
Test development fixtures are fully amortized and now incur mainly maintenance; high reuse across product families materially raises gross margin per build. 2024 saw flat demand year-on-year but sustained positive margins, so preserve the test-library, standardize processes, and capture incremental cash flows.
Logistics and fulfilment for stable SKUs in Incap focus on kitting, configure-to-order and regional ship-outs with tight SLAs to minimize variability and surprises. Barcode-everything operations keep error rates low and throughput high, turning predictable volumes into steady cash flow. Efficient repeatable processes keep costs boring and margins stable.
Legacy control boards and spare-part programs are Cash Cows: stable demand (~0%–3% growth), ~15% of group revenue in 2024, 95%+ SLA retention and high margins. Operations (procurement, fixtures, logistics) deliver predictable cash flow via 6–8 inventory turns, low ongoing capex and repeatable process gains. Milk efficiencies and channel annuities to maximize free cash flow.
| Metric | 2024 |
|---|---|
| Revenue share | ~15% |
| Growth | 2–3% (aftermarket) |
| SLA | 95%+ |
| Inventory turns | 6–8 |
| Capex | <1% rev |
The file you're previewing is the exact Incap BCG Matrix you'll receive after purchase. No watermarks, no demo elements—just a fully formatted, analysis-ready report tailored for strategic decisions. It’s the same editable, print-ready document that lands in your inbox immediately after payment. Use it in board decks, investor meetings, or internal planning without tweaks. Buy once, download instantly—no surprises.
Incap’s 2024 disclosures flag tiny custom runs as dogs: micro-batches consume disproportionate setup and engineering hours while delivering marginal or negative incremental margin. These projects divert resources from higher-volume books and reduce overall plant OEE, prompting recommendations to sunset, reprice aggressively, or step away. Prioritize scale customers and redeploy engineering to scalable SKUs.
Legacy through-hole rework lines are labor-heavy, slow, and hard to automate, with 2024 industry surveys (IPC/EMS) confirming manual repair dominates repair costs and cycle time. Customers generally refuse to pay true cost, so capacity becomes trapped in low-yield, low-margin work and depresses overall factory efficiency. Recommend divest, outsource, or consolidate to a single cell at most to free capacity for higher-yield production.
Commodity broker-style sourcing sits in Dogs: race-to-the-bottom SKUs with no differentiation, compressing gross spreads to roughly 2–4% in 2024 and driving high churn. High risk and thin spreads create operational headaches and credit exposures while cash sits in inventory for 120–180 days, earning pennies on capital. Exit recommended: redeploy capex into value-added supply chains with higher margins and faster turns.
Sites without scale or anchor customers drain Incap’s P&L as fixed overheads overwhelm thin revenue; many small plants operate below breakeven and turnaround plans historically fail to restore margins.
Consolidate capacity into performing facilities, close or divest loss-making sites, and redeploy volumes to achieve higher utilization and lower unit fixed costs.
Incap dogs: micro-batches consume high setup/engineering for marginal/negative margins, legacy through-hole rework is labor-heavy and manual (IPC/EMS 2024: majority repair effort manual), commodity broker SKUs compress spreads to ~2–4% (2024) and inventory sits 120–180 days, and obsolete one-offs bleed margin — recommend exit, consolidate, or priced-to-risk LTB.
| Metric (2024) | Value |
|---|---|
| Gross spread (broker SKUs) | 2–4% |
| Inventory days | 120–180 |
| Micro-batch margin | ≤0% (marginal/negative) |
AI edge-compute hardware is a Question Mark: the market surged to an estimated $3.9B in 2024 with ~27% CAGR forecast through 2030, but commercial wins remain early and fragmented. Success hinges on solving complex thermals and power-delivery challenges—capability gaps matter if solutions can be landed. Builds require significant capex, specialized talent and rapid learning curves. Bet selectively on anchor customers to flip offerings into Stars.
Regulatory tailwinds (EU MDR enforcement, expanded US RPM reimbursement) supported a global wearable medical devices market estimated at about $30 billion in 2024 (Grand View Research), but aggressive commoditization is driving price pressure and margin compression. Low share today; multiple OEM pilots are in motion, so Incap should invest in quality systems and rapid NPI to capture scale quickly. If adoption stalls, redeploy capacity fast to higher-margin industrial or medical niches.
Demand for nearshoring from EU/US customers is rising with early commitments forming but market share remains low; typical EMS facility capex is €10–15M and initial staffing costs push break-even beyond 12–18 months. Win lighthouse programs to validate unit economics and justify upfront spend; benchmark pilots can lift conversion rates by 20–30%. If load fails to ramp, trim capacity and refocus on higher-margin niches quickly.
Circularity sits as a Question Mark for Incap: ESG-driven demand is rising but margins remain uncertain and processes aren’t fully standardized; improving throughput could convert returns, repair and refurb into stickier revenue for core accounts, otherwise recommend partnering out while preserving design-to-repair guidelines.
Turnkey IoT reference modules are pre-certified, fast-to-market kits that could unlock volume if scaled; global IoT endpoints surpassed an estimated 15 billion in 2024, indicating strong total addressable market demand. Incap’s current traction is light and scattered, requiring a marketing push and 3–5 showcase customers to validate use cases and drive OEM adoption; decide to double down or shelve—don’t linger in the middle.
Question Marks: AI edge hardware $3.9B (2024); wearables ~$30B (2024); IoT endpoints ~15B (2024); nearshoring capex €10–15M—high-growth but low share; requires capex, pilots, anchor customers and fast NPI to flip into Stars.
| Segment | 2024 | Key action |
|---|---|---|
| AI edge | $3.9B | anchor customers |
| Wearables | $30B | scale NPI |
| IoT modules | 15B endpoints | 3–5 showcases |
| Nearshoring | €10–15M capex | lighthouse wins |


