
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
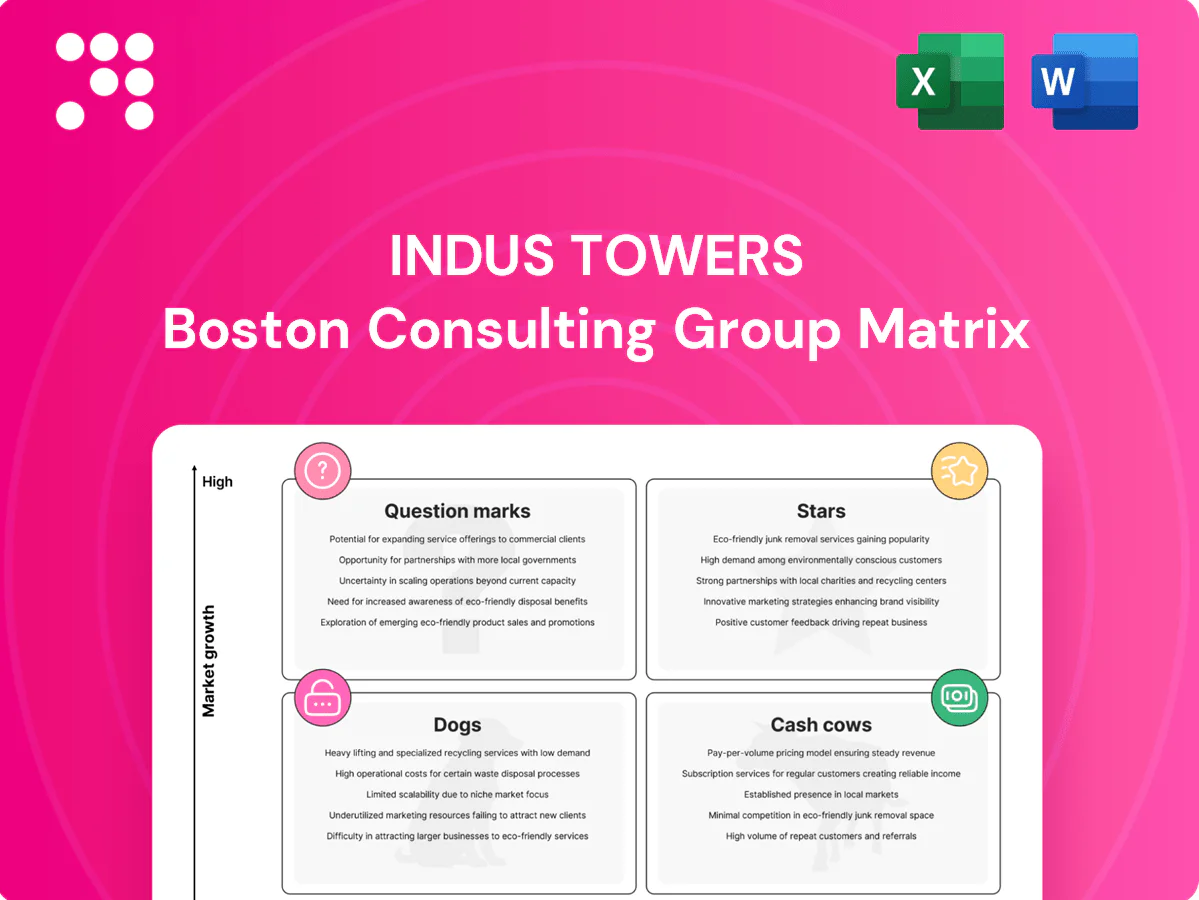
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Indus Towers' offerings land—Stars, Cash Cows, Dogs, or Question Marks? This preview sketches the landscape; the full BCG Matrix maps each asset to its quadrant with data-backed rationale and clear strategic moves you can use today. Purchase the complete report for downloadable Word and Excel files, quadrant visuals, and concise recommendations to guide investment and resource decisions—fast, practical, and ready to present.
Urban 4G/5G macro sites show ~25% YoY mobile data growth in India (2024) and tenancy ~1.82x at Indus, where the company already dominates this segment. These sites lead the grid but require steady capex—Indus ran ~INR 1,200–1,500 crore capex in FY2024—for upgrades and power reliability. Maintain share and loading and cash generation will rise even as growth cools. This is the strategic invest-to-stay-on-top cluster.
Exploding indoor data demand—GSMA estimates over 60% of mobile data usage shifted indoors by 2024—pushes Indus Towers to prioritise Metro in-building DAS in premium locations with fast upgrades. Neutral-host DAS in malls, airports and offices wins scale advantages early, capturing multi-tenant revenue streams. It soaks cash now but locks prime venues; hold the lead while the market is still racing.
5G colocation build-to-suit is a Stars play as operators added layers rapidly in 2024 and Indus can stack tenants quickly on new sites, converting capex into multi-tenant revenue streams. Speed-to-site and permitting muscle form a durable moat, enabling faster tenancy ramp-ups than peers. Cash usage is heavy now but tenancy ramps pay back as growth normalizes, so keep the throttle open.
Fiberized tower backhaul shifts towers into Stars: where fiber attach is high, throughput, reliability and customer stickiness rise, supporting premium rents for Indus as 5G data demand surged in 2024.
Partnerships to accelerate fiber-to-tower can capture higher ARPU per site; upfront capex is heavy today but secures leadership for 5G-era loads.
Energy-as-a-service smart power systems have cut outages 30–50% and lowered site opex ~20–30% in telecom deployments, improving SLAs for carriers; high uptake in growth markets makes this a flagship differentiator for Indus Towers. Upfront kit raises capital intensity, but payback often arrives in 2–4 years via higher tenancy (5–10%) and better uptime; keep scaling the platform.
Urban 4G/5G macros show ~25% YoY data growth (2024) with Indus tenancy ~1.82x; FY2024 capex ~INR 1,200–1,500 crore to upgrade sites. Fiber attach and Metro DAS lift ARPU and stickiness; 5G build-to-suit accelerates tenancy ramps. Energy-as-a-service cut outages 30–50% and yields payback in 2–4 years, justifying continued aggressive investment.
| Metric | 2024 | Impact |
|---|---|---|
| Data growth | ~25% YoY | Drives demand |
| Tenancy | ~1.82x | Higher revenue/site |
| Capex | INR 1,200–1,500cr | Short-term cash use |
| Outage reduction | 30–50% | Better SLAs |
 Detailed Word Document
BCG analysis of Indus Towers' portfolio: Stars, Cash Cows, Question Marks, Dogs, with clear invest/hold/divest guidance.

 Customizable Excel Spreadsheet
Clean, distraction-free Indus Towers BCG Matrix for C-level decisions, highlighting portfolio priorities at a glance.
Indus Towers sits in Cash Cows: high market share (~37%) and low market growth, operating roughly 192,000 sites in India with stable rent rolls and recurring tenancy revenues. Minimal promotion is needed; operations focus on uptime and cost control to sustain an EBITDA margin near 60%. These sites generate steady cash to fund next-wave capex and spectrum-related needs. Milk gently: invest in efficiency, not flash.
Long-term MNO contracts with locked-in escalations of roughly 3–5% and collections from over 190,000 towers provide predictable cashflows that support dividends and debt service. Tight opex control sustains EBITDA margins around 55–60%, enabling selective capex and strategic bets. Prioritize protecting contract terms and avoid price erosion to preserve yield and leverage capacity.
Multi-tenant ground-based sites carry three-plus tenants with low churn and steady power profiles, yielding high utilization; incremental margins rise sharply as load increases while little incremental capex is needed to add tenants. Focus on optimizing maintenance cycles and keeping sites fully loaded to preserve EBITDA per site and maximize long-term cash generation.
Shared passive infra services — power, shelter, maintenance — are standardized and efficient, driving steady cash flow. Mature processes cut surprises; Indus Towers' ≈200,000 sites and FY2024 EBITDA margin near 48% support resilient earnings. Upsell only when clearly margin-accretive; otherwise keep the footprint lean.
Rooftop sites in saturated urban zones act like annuities for Indus Towers: limited expansion but high tenancy and low churn, requiring minimal capital intensity and predictable maintenance, so cash generation routinely exceeds reinvestment needs; portfolio yield stability supports a hold-and-harvest posture.
Indus Towers = Cash Cow: ~195,000 sites (2024), high market share (~37%), low market growth; stable tenancy (~1.8x) and long‑term MNO contracts with 3–5% escalations drive predictable cashflow and FY2024 EBITDA ~48–60% across portfolios. Focus on uptime, opex control, selective margin‑accretive upsell and funding debt/dividends.
| Metric | 2024 |
|---|---|
| Sites | ~195,000 |
| Tenancy | ~1.8x |
| EBITDA margin | 48–60% |
| Escalations | 3–5% |
The file you're previewing is the exact Indus Towers BCG Matrix you'll receive after purchase. No watermarks or placeholder content—just a fully formatted, analysis-ready report tailored for portfolio strategy and market positioning. The final document is editable and printable, ready to drop into presentations or board packs, and will be delivered instantly after payment. Buy once, download immediately—no surprises, no extra edits required.
Underutilized rural 2G-only sites are low-growth, single-tenant or idle assets that trap cash and deliver shrinking returns; turnarounds in 2024 proved costly and often nonpersistent. Prioritize consolidation or exit where demand is weak and avoid reinvesting in refurbs with limited ROI. Don’t throw good money after weak demand—redeploy capital to higher-growth towers or fiber upgrades.
Legacy diesel-heavy power setups drive high fuel and maintenance burn and show poor reliability, raising OPEX and service-risk for Indus Towers. Savings from retrofits or hybrid upgrades often do not justify capital spend on marginal or low-traffic sites, making ROI weak. Recommend phasing out diesel assets where feasible and bundling remaining exposure into targeted divestments to keep network exposure minimal.
Non-core standalone small pockets are scattered, low-density sites (~3–5% of Indus Towers portfolio) that resist clustering economics and show tenancy often below 1.5x. Service and site OPEX run c.20–30% above network average, keeping per-site costs stubbornly high. If loading cannot be raised within a 12–18 month plan, consider targeted sale to local towerco or MNOs. Disposals free up ops bandwidth for high-tenancy clusters.
Old tech enclosures and shelters are oversized, heat-inefficient cabins built for past gear and increasing O&M spend; Indus Towers operates about 192,000 towers (2024) so legacy shelters scale this cost. Retrofitting cabins is often costly with limited upside; prioritize retirements via site exits or selective replacements where tenancy and incremental revenue justify capex. Stop the slow leak by accelerating decommissioning of non-core shelters.
Single-tenant, low-ARPU corridors show weak utilization with little prospect of a second tenant; many such pockets within Indus Towers portfolio (≈183,000 sites reported Mar 2024) generate revenue that barely covers upkeep. Recommend decisive consolidation or site renegotiation to cut losses and reallocate capital to high-share locations.
Dogs: scattered low-growth, single-tenant rural 2G/diesel-heavy sites (Idus Towers c.192,000 sites in 2024) trap cash, show tenancy <1.5x and OPEX +20–30%, yielding weak ROI; prioritize consolidation, targeted divestment or phased decommissioning rather than refurb capex. Redeploy savings to high-tenancy towers and fiber upgrades.
| Metric | Value |
|---|---|
| Sites | ≈5,760–9,600 (3–5%) |
| Tenancy | <1.5x |
| OPEX vs avg | +20–30% |
| Action | Consolidate/exit |
Street furniture small cells sit in high-growth data zones—tier-1 metros recorded >30% mobile data traffic growth in 2024, creating premium densification demand. Fragmented municipal permissions and varied commercial models slow rollouts; scaling needs capital and municipal speed. Focus on 3–5 flagship cities, deploy deep clusters to convert into a premium densification network.
Neutral-host private networks sit as a Question Mark: enterprise demand for reliable on-prem coverage is rising but still early—GSMA reported over 1,200 enterprise private network deployments by 2023. If Indus standardizes deployment and productizes offerings, operating margins could expand through scale; if sales cycles stall, capital intensity and slow ARPU recovery could depress returns. Rapid test-and-learn pilots will show whether to double down or exit.
Edge data hubs at tower sites are Question Marks: latency-sensitive workloads are rising—edge computing market is growing at roughly 30% CAGR (2024–30)—but demand is uneven across locations. Co-locating micro-edge near existing power and fiber at Indus sites could pay off; requires ecosystem partners and careful site picks. Place selective bets.
IoT gateway infrastructure sits in Question Marks: device counts are massive (global IoT connections ~15B in 2024) while ARPU is tiny (often under $2/month), so scale matters; when bundled onto Indus Towers' site footprint, incremental unit economics can work, but standalone rollouts without scale become a cash drain; pilot only where anchor tenants commit.
Indoor 5G neutral-host beyond metros into Tier-2/3 shows real but uneven demand: non-metro urban broadband growth rose ~12% YoY in 2024, yet venue-level adoption remains patchy. Capex per venue is meaningful—typically ₹50–200 lakh in India per multi-operator deployment—so payback depends on confirmed multi-tenant commitments. Land anchor buildings, replicate a repeatable playbook and invest only with line-of-sight to multi-tenant load and commercial contracts.
Question Marks (Indus): street furniture shows >30% mobile data growth in 2024—needs capital and municipal speed to scale. Neutral-host private networks: 1,200+ enterprise deployments by 2023; standardize to expand margins. Edge data hubs: ~30% CAGR (2024–30) but uneven location demand. IoT gateways/indoor 5G need scale, anchor tenants and capex visibility.
| Segment | 2024 metric | Key constraint |
|---|---|---|
| Street furniture | >30% data growth | Permits, capex |
| Private networks | 1,200+ deployments | Sales cycles |
| Edge hubs | ~30% CAGR | Location demand |
| IoT gateways | ~15B connections | Low ARPU |
| Indoor 5G T2/3 | ↑ ~12% YoY | ₹50–200L/venue |


