
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Inpex faces a complex mix of supplier leverage, capital intensity, and evolving energy demand that shapes its competitive landscape; this snapshot highlights key pressures and strategic levers. Ready for deeper, force-by-force ratings, visuals, and actionable implications? Unlock the full Porter’s Five Forces Analysis to inform smarter investment and strategy decisions.
INPEX depends on scarce high-spec drilling rigs, subsea systems and FPSO capacity, where industry lead times typically run 18–36 months and rig/utilization rates exceeded 90% in 2024, strengthening supplier leverage. Leading OFS vendors and Korean/Chinese shipyards command premium pricing and delivery priority, driving long lead-time dependence and high switching costs. Tight supply cycles amplify schedule and cost risk, raising capex volatility for projects.
Host governments and NOCs control access to acreage and production terms, holding over 80% of proven oil and gas reserves (IEA, 2024), which lets them set fiscal terms, local‑content rules and gas‑pricing frameworks that materially shape project economics. Renegotiations or policy shifts can reallocate significant value to the resource owner, and political risk raises supplier power in frontier and LNG‑linked markets.
Proprietary technologies and experienced EPCs are required for LNG trains, CO2 capture units and hydrogen facilities, with individual LNG train modules typically costing $3–5 billion each. Limited qualified contractors create strong bidding power and change‑order leverage; the 2024 global LNG/CCS/H2 project pipeline was roughly $200 billion and remains concentrated among a few firms. Performance guarantees and integration know‑how are negotiation choke points, and vendor lock‑in can persist across 20+ year project life cycles.
Global cyclicality in steel, compressors, cryogenic skids and marine logistics tightened supplier leverage for Inpex in 2024: steel price swings ~20% y/y, compressor lead times 12–24 months and cryogenic equipment 18–30 months, driving procurement delays and cost inflation. Remote offshore and desert projects amplify logistics dependence and inventory risk, while freight and FX volatility (freight swings ~25–30% in 2023–24) further shift bargaining power to suppliers. Supply shocks have translated into multi-100 million-dollar capex timing risk on large LNG/offshore projects.
INPEX faces strong supplier power: rig/utilization >90% in 2024 and long 18–36 month lead times. LNG/EPC vendors and shipyards command premium pricing; LNG train capex $3–5bn. Host governments/NOCs hold >80% reserves (IEA 2024), shaping fiscal/local rules. Steel volatility ~20% y/y and freight/FX swings ~25–30% (2023–24) raise capex and schedule risk.
| Item | 2024 Metric |
|---|---|
| Rig utilization | >90% |
| LNG train cost | $3–5bn |
| Reserves control | >80% (IEA) |
| Steel volatility | ~20% y/y |
| Freight/FX | ~25–30% |
 Detailed Word Document
Uncovers key drivers of competition, customer influence, and market entry risks tailored to Inpex, with detailed evaluation of suppliers, buyers, substitutes, new entrants and industry rivalry to reveal pricing power and strategic vulnerabilities.

 Customizable Excel Spreadsheet
A concise one-sheet Porter's Five Forces for INPEX that visualizes supplier, buyer, competitor, entrant and substitution pressures and lets you toggle scenarios for regulatory, price or project changes—perfect for rapid strategic decisions and clean slide-ready summaries.
Large utilities and aggregators negotiate long-term SPAs (typically 15–20 years) with oil- or gas-indexed pricing, while portfolio buyers leverage scale, destination flexibility and spot alternatives; global LNG trade reached about 380 mtpa in 2024, boosting buyers’ bargaining leverage. Creditworthy offtakers demand favorable credit and carbon-intensity disclosures, and their multi-year procurement cycles materially influence INPEX project FIDs.
Oil and condensate buyers, largely refiners and petrochemical players, are numerous and price-driven with transparent benchmarks such as Brent and Platts governing deals in 2024. Quality specs and narrow logistics windows limit sellers’ differentiation levers, keeping negotiation focused on price and delivery. Regional switching of cargos is common with modest transshipment or freight cost impact. Margin-sensitive customers increasingly demand flexible lifting and payment terms.
Growing JKM/TTF-linked pricing and rising spot volumes — spot and short-term LNG trade accounted for about 35-40% of global volumes in 2024 — increase buyer optionality, while shorter contract tenors erode seller lock-in. Market volatility lets buyers time purchases, reducing achievable premiums on long-term contracts and compressing seller bargaining power.
Government-backed purchasers can force procurement to reflect policy goals—security of supply and price caps—affecting contract pricing and volumes; in 2024 JKM averaged about $12/MMBtu, tightening buyer leverage in LNG deals. Political influence can reset commercial terms rapidly, and sanctions/trade rules since 2022 continue to reshape counterparties and routing. INPEX must weigh commercial returns against diplomatic risk when negotiating state-linked contracts.
Large utilities and aggregators use 15–20 year SPAs with oil/gas indexing while portfolio buyers exploit scale, destination flexibility and spot options; global LNG trade reached ≈380 mtpa in 2024, boosting buyer leverage. Spot/short-term volumes were ~35–40% in 2024 and average JKM ≈$12/MMBtu, increasing optionality and compressing seller premiums. Buyers demand GHG/methane controls (methane ≈30% of warming), creating pass/fail CI thresholds.
| Metric | 2024 |
|---|---|
| Global LNG trade | ≈380 mtpa |
| Spot/short-term share | 35–40% |
| Avg JKM | ≈$12/MMBtu |
| SPA tenor | 15–20 yrs |
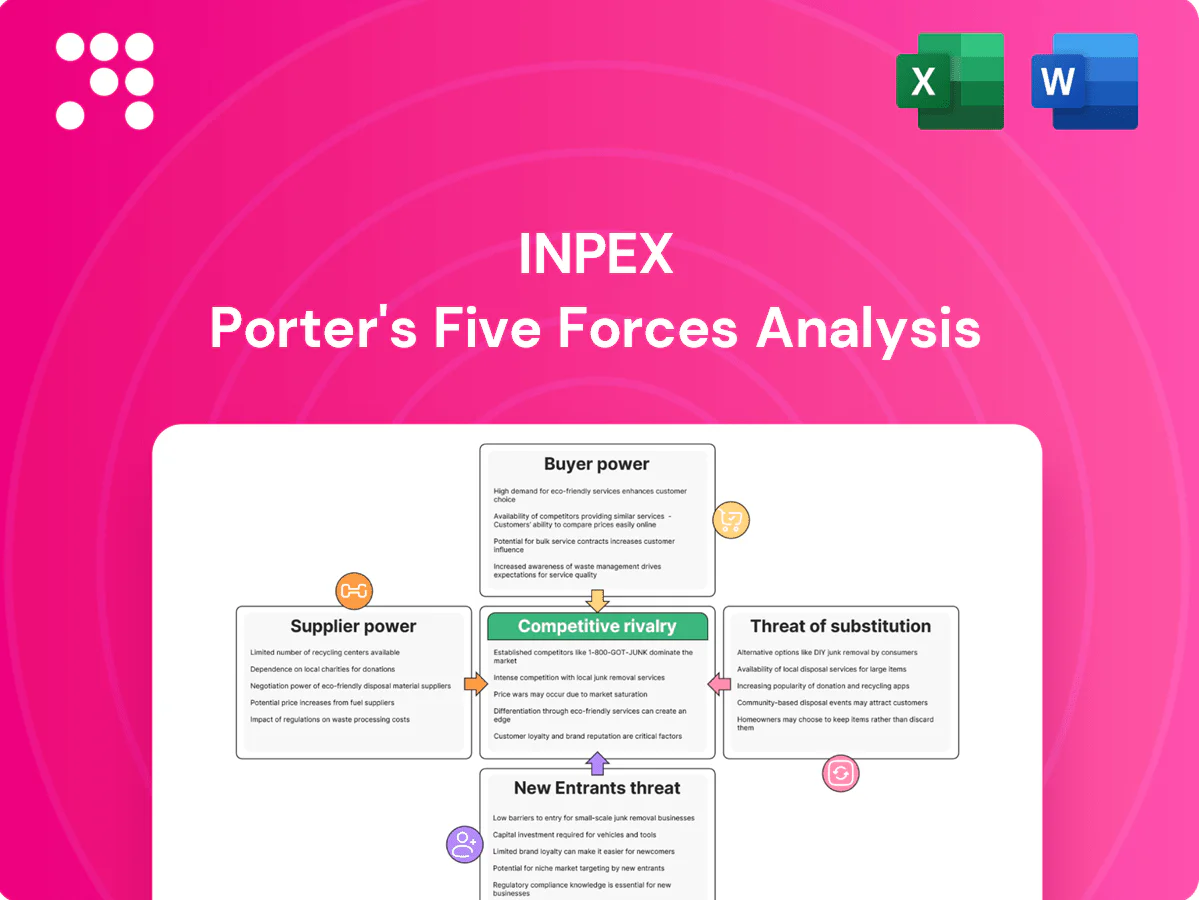
This Inpex Porter's Five Forces Analysis preview shows the exact, fully formatted document you’ll receive immediately after purchase—no placeholders or sample pages. The content is complete and ready for download and use the moment you buy. You’re viewing the final deliverable, unchanged and ready for practical application.
INPEX faces intense rivalry from majors and NOCs such as Shell, QatarEnergy, ExxonMobil and TotalEnergies that combine scale, destination-rights and flexible portfolios; QatarEnergy is expanding North Field capacity toward 126 mtpa by 2027. Ichthys LNG (INPEX) is 8.9 mtpa, highlighting scale gaps. Large traders from these groups intensify price competition and marketing clout can overshadow standalone projects.
Regional rivals Woodside, Santos, Petronas and CNOOC aggressively compete for acreage, CO2 storage and offtake as Asia-Pacific — which took roughly 70% of global LNG imports in 2024 — concentrates demand; brownfield tie-backs and debottlenecking can cut marginal unit costs by up to 20–30%, compressing delivered-price differentials across the region and intensifying competition on project timelines and contract terms.
Competitive bid rounds and farm-ins create zero-sum acreage contests where Inpex, Japan's largest oil and gas explorer, must outbid peers to secure growth. Geoscience edge and lower cost of capital determine winners, driving premium valuations in 2024 licensing rounds. Work program commitments force execution races and higher near-term capex; failure to secure prime blocks shrinks Inpex's production and reserve growth runway. The Ichthys LNG project cost about 34 billion dollars as a benchmark of scale.
H2, NH3 and CCUS hubs attract utilities, chemical majors and tech entrants competing for corridors and storage; electrolyzer costs have fallen roughly 60% since 2019, accelerating entry. First-mover capture of pipeline corridors and saline/ depleted storage sites is strategic; certification standards and offtake MOUs are primary battlegrounds, with hundreds of MOUs announced by 2024. Scale-up speed—not price alone—dictates market leadership.
INPEX faces intense rivalry from majors and NOCs (QatarEnergy expanding to 126 mtpa by 2027) while Ichthys LNG is 8.9 mtpa and cost ~34 billion USD, exposing scale gaps. Asia‑Pacific took ~70% of global LNG imports in 2024, compressing margins via brownfield tie‑backs (unit costs cut 20–30%). H2/NH3/CCUS entrants and >100 MOUs by 2024 push first‑mover corridor and storage competition; top‑quartile IRRs >12% amid capex inflation.
| Metric | 2024/2027 |
|---|---|
| Asia LNG share | ~70% (2024) |
| QatarEnergy capacity | 126 mtpa (2027) |
| Ichthys | 8.9 mtpa; ~USD34bn |
| Electrolyzer cost decline | ~60% since 2019 |
Utility-scale solar, wind and storage are progressively displacing gas-fired power as 2024 utility PV LCOE sits near $20–35/MWh and BNEF reports battery pack prices around $120/kWh, making renewables cheaper than marginal gas in many markets. Policy incentives and auctions in 2024 accelerated uptake, while grid build-out and emerging flexibility markets improve integration and capacity value. IEA 2024 shows OECD gas demand flattening through 2030, reducing long-term growth prospects for Inpex.
New nuclear and SMRs deliver low-emission baseload — nuclear supplied about 10% of global electricity in 2024 — and, when paired with long-duration energy storage, can supplant gas peakers and seasonal balancing. Policy-backed drivers such as the US IRA and EU support accelerate deployments and can pivot national mixes, denting LNG’s value proposition in grids where flex and peak roles shrink.
Building retrofits and the surge in heat pumps—Europe sold roughly 4 million units in 2024—directly substitute gas for space heating, with typical COPs of 3–4 cutting site gas use by 50–70% in heated buildings. Efficiency mandates and renovation targets (EU Renovation Wave) shrink industrial and commercial fuel needs. Demand-side management and smart controls trim peak loads, collectively eroding downstream gas volumes and revenue.
Biofuels and synthetic fuels—notably sustainable aviation fuel, renewable diesel and e-methane—increasingly displace oil-derived transport and heating products; EU ReFuelEU targets 2% SAF in 2025, rising thereafter, driving scale-up. Blending mandates for diesel and jet fuel accelerate investment and offtake. Petrochemical naphtha faces substitution from advanced recycling and bio-naphtha, pressuring liquids demand over time.
Green hydrogen and ammonia can substitute natural gas in industry and power co-firing, with 2024 project pipelines aiming for hundreds of GW of electrolyzers globally.
Electrolyzer costs have fallen ~60% since 2015 (BNEF 2024) and renewable LCOEs are down, improving green competitiveness versus gas.
Certification pilots (EU 2024) and ammonia shipping hubs are scaling; this pressures blue molecules unless CCS achieves >90% capture to match lifecycle emissions.
Rapidly falling renewables and storage (utility PV LCOE $20–35/MWh; battery ~$120/kWh in 2024) undercut gas peaking economics; nuclear (~10% global power 2024) and SMRs offer baseload alternatives. Heat pumps (~4M units Europe 2024) and efficiency reduce gas heating demand. Electrolyzer costs down ~60% since 2015; SAF mandates (ReFuelEU 2% 2025) and bio/synthetic fuels erode liquids demand.
| Substitute | 2024 stat |
|---|---|
| Utility PV LCOE | $20–35/MWh |
| Battery pack | $120/kWh |
| Nuclear share | ~10% global |
| Heat pumps EU | ~4M units |
| Electrolyzer cost decline | ~60% since 2015 |
Upstream and LNG projects require multi-billion-dollar capex and long lead times; Ichthys LNG is an example with reported project costs around US$34 billion. Financing and FID demand proven reserves, offtake/marketing and sophisticated risk management to secure project finance. Cost of capital favors incumbents with investment-grade access and track records, so newcomers often fail to attain FID.
Resource access is state-controlled: in 2024 national oil companies hold more than two-thirds of global oil and gas reserves, and acreage allocations are granted by governments, limiting open entry. Local-content and partnership rules—seen in large projects like Ichthys LNG (~$34 billion)—force joint ventures and significant local spend. Political risk management is mandatory, and entrenched incumbent-NOC relationships raise barriers that deter new entrants.
Deepwater, sour gas and cryogenics demand specialist engineering and operations; INPEX’s Ichthys LNG is an exemplar, with reported capex around US$34 billion demonstrating scale and technical depth. HSE, ESG and tighter methane controls since 2021 have raised baseline competencies and compliance costs for entrants. Complex supply chain orchestration and steep learning curves create multi-year time and cost penalties before parity with incumbents.
Carbon pricing (EU ETS ~€85/t in 2024), tighter methane rules finalized by EPA in 2023–24, and broader disclosure regimes (ISSB/IFRS S2 adoption in 2024) raise compliance costs and reporting burdens. Permitting and community consent often add 3–5 year delays, while global operational CO2 storage remains limited (~40 MtCO2/yr scale), deterring all but well‑capitalized entrants.
High capex and long lead times (Ichthys LNG ~US$34bn) plus need for proven reserves and offtake keep newcomers out. State-controlled acreage, local-content rules and NOC ties constrain entry; permits add 3–5 year delays. Trading, shipping and credit strength (buyers: 2024 spot ~40% / long-term ~60%) raise barriers. ESG, carbon pricing (EU ETS ~€85/t 2024) and limited CO2 storage (~40 MtCO2/yr) increase costs.
| Metric | 2024 value |
|---|---|
| Ichthys capex | ~US$34bn |
| Spot vs LT LNG | ~40% / ~60% |
| EU ETS | ~€85/t |
| CO2 storage | ~40 MtCO2/yr |
| Permitting delay | 3–5 yrs |


