
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Intrepid Potash SWOT Analysis highlights its stable potash assets, operational strengths, cost pressures, market cyclicality, and regulatory risks. Unlock the full report for actionable insights, valuation context, and strategic recommendations. Purchase the complete SWOT (Word + Excel) to plan, pitch, or invest with confidence.
Intrepid Potash (NYSE: IPI) operates its potash mining and processing solely within the United States, enhancing supply security for domestic agricultural and industrial customers. Domestic production reduces geopolitical exposure relative to foreign-sourced potash and helps shorten lead times to U.S. end-markets, stabilizing delivery. Proximity to buyers can also bolster relationships with government and strategic purchasers.
Intrepid Potash sells salt, magnesium chloride and brine alongside potash across its Carlsbad, Moab and Wendover operations, broadening end-market exposure. This product mix cushions revenue when potash prices soften and enables cross-selling that boosts customer stickiness. Diversification also allows seasonal optimization of asset utilization, improving throughput and margin stability.
Potassium chloride is a core nutrient for crop yield and quality, with agriculture accounting for roughly 95% of global potash use. Structural agricultural demand underpins baseline volumes, supporting roughly 65–70 million tonnes of global potash demand in 2023–24. Long-term food demand growth (population and dietary shifts) supports sustained potash consumption. This creates a resilient demand floor across cycles for producers like Intrepid Potash.
Intrepid Potashs exposure to industrial and animal feed markets broadens revenue beyond crop cycles, with magnesium chloride and salt serving de-icing and multiple industrial uses that reduce seasonality risk. This product mix can smooth cash flow across quarters and partially hedge agricultural price swings.
Integrated brine operations at Intrepid Potash (IPI) across Utah and New Mexico enable byproduct recovery and internal cost sharing, while shared infrastructure across product lines drives higher throughput and lower unit costs. Deep process know-how improves product quality and delivery reliability, supporting stable offtake relationships. These synergies help translate into competitive delivered costs regionally.
Intrepid Potash operates three US production sites (Carlsbad, Moab, Wendover), supplying domestic agriculture and industrial customers, reducing geopolitical exposure. Product mix—potash, salt, magnesium chloride and brine—diversifies revenue and smooths seasonality. Brine-driven processing and shared infrastructure lower unit costs and support stable offtakes. Structural demand remains: global potash use ~65–70 Mt (2023–24), agriculture ~95%.
| Metric | Value |
|---|---|
| US production sites | 3 |
| Primary products | potash, salt, MgCl2, brine |
| Global potash demand (2023–24) | 65–70 million tonnes |
| Agriculture share | ~95% |
 Detailed Word Document
Provides a concise SWOT analysis of Intrepid Potash, detailing its operational strengths and resource advantages, financial and regulatory weaknesses, market and product opportunities, and external threats such as commodity price volatility and environmental/regulatory risks.

 Customizable Excel Spreadsheet
Provides a concise Intrepid Potash SWOT matrix that clarifies mine‑level risks, commodity exposure, regulatory pressures and market opportunities for quick stakeholder alignment and fast decision-making.
Intrepid Potash operates in a market where potash and related fertilizers are price-taker commodities, with global potash production around 65 million tonnes annually driving market prices.
Margins can swing sharply with global potash price cycles, constraining EBITDA when spot prices fall and limiting Intrepid’s ability to pass costs to customers.
Limited pricing power and thin hedging options in physical fertilizer markets increase earnings volatility and downside risk during prolonged down cycles.
Global competitors such as Uralkali, Belaruskali and Nutrien operate at 10+ million tonne per year potash scales, whereas Intrepid operates at a materially smaller, single‑digit million/annual scale; this gap drives higher unit costs and weaker procurement leverage. Narrower marketing reach versus those global players reduces access to large-volume contracts, pressuring Intrepid in price-sensitive bids and limiting share gains.
Intrepid Potash maintains 100% of its mining and processing operations within the United States, concentrating operational and regulatory risk domestically. Regional weather, rail or road disruptions can therefore cause outsized production and shipment interruptions. Customer demand concentrated in U.S. agricultural regions may amplify revenue volatility given limited international diversification.
Intrepid Potash's mining and evaporation model is capital- and resource-intensive, with high maintenance and energy expenses that can materially raise unit costs; water availability and evaporation rates drive output sensitivity, causing production variability and cost creep.
Cyclical agricultural demand ties Intrepid Potash sales closely to farm incomes and planting decisions, so fertilizer usage falls rapidly when revenues or planting acreage decline. Weather, crop-price swings and subsidy shifts can cut application rates and shorten buying windows, while retail-channel inventory swings amplify quarterly volatility. This cyclicality complicates production planning and capacity utilization.
Intrepid is a price‑taker in a 65 Mt global potash market, driving margin sensitivity to spot price swings. Its ~0.7 Mt annual production (≈1% global) leaves it exposed to higher unit costs and weaker commercial leverage versus 10+ Mt peers. Operations are 100% U.S.‑based, concentrating regulatory, weather and logistics risk. Capital‑ and water‑intensive evaporation mining raises energy and maintenance cost exposure.
| Metric | 2024 value |
|---|---|
| Global potash production | ≈65 Mt |
| Intrepid annual production | ≈0.7 Mt (~1% global) |
| Operations | 100% U.S. |
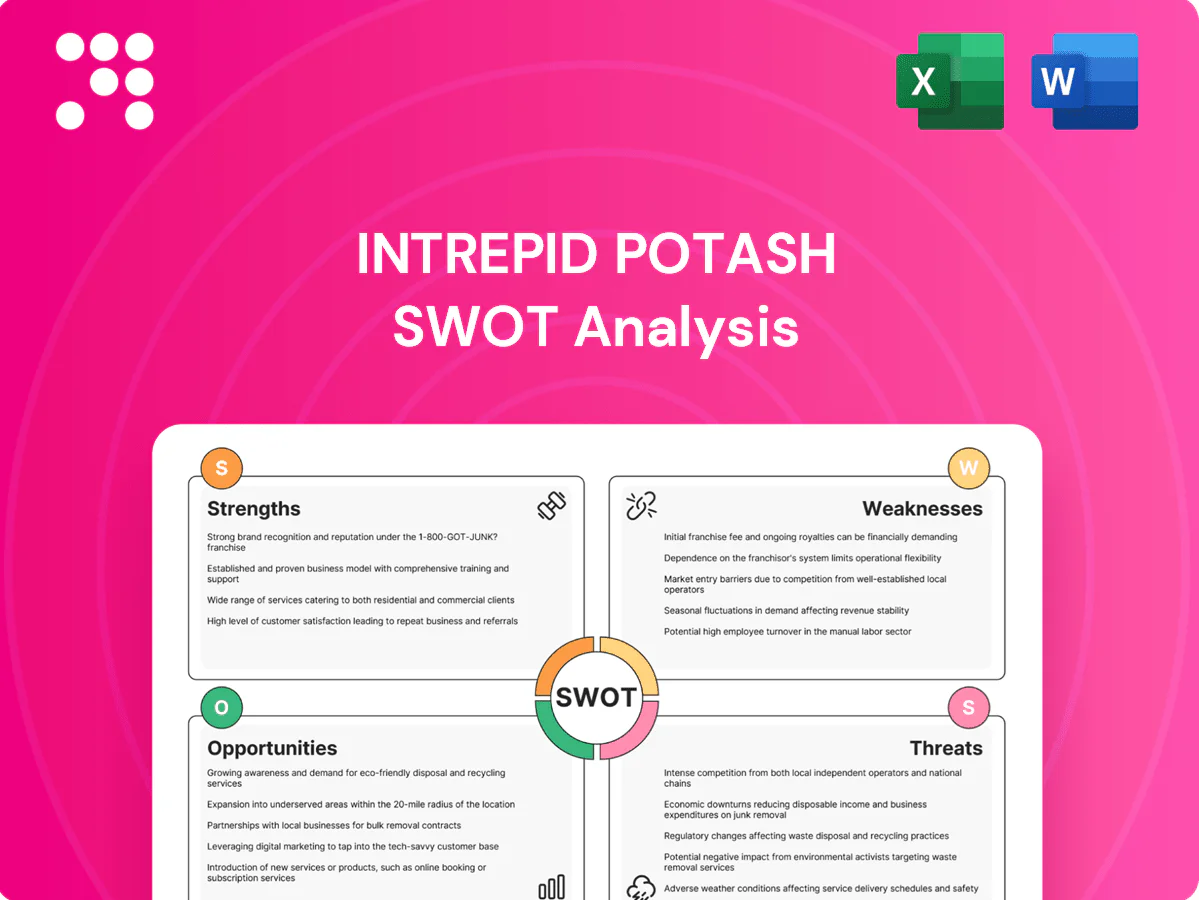
This is the actual SWOT analysis of Intrepid Potash you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report and reflects the same structured, editable document available after checkout. Purchase unlocks the complete, detailed version for immediate download.
Developing specialty blends, granular forms and premium grades can lift margins for Intrepid, tapping a specialty fertilizer market that surpassed $40 billion in 2024. Tailored nutrient solutions for high-value crops create differentiation and justify premiums. Positioning co-products like magnesium chloride for soil health can boost relevance and expand wallet share with existing customers.
Magnesium chloride and salt see steady demand for de-icing and dust control, with US road salt consumption about 18 million tonnes per year (USGS). The Infrastructure Investment and Jobs Act directs roughly 110 billion dollars for roads and bridges, supporting municipal procurement volumes. Industrial brine applications rely on recurring contracts, and shifting into multi-year agreements can stabilize and predict cash flows.
Buy American and federal procurement rules (Buy American Act, strengthened under recent infrastructure and domestic sourcing priorities) increase preference for U.S. producers, benefiting Intrepid Potash (ticker IPI), a U.S.-based miner and supplier.
Customers increasingly value local supply for reliability and ESG transparency, and Intrepid can point to domestic production and U.S. operations to meet those demands.
Reduced import exposure lowers logistics and geopolitical risk, supporting modest price premiums and better contract stability for domestic sales.
Public-sector procurement and infrastructure programs expanding since 2021 open new channels for industrial and agricultural offtake for U.S. potash suppliers.
Investments in advanced process controls, higher recovery rates and energy-efficiency measures can cut unit costs for Intrepid Potash (IPI), improving margins versus imported potash in a global market of roughly 60 million tonnes annual production. Digital forecasting can better match production to seasonal demand spikes; water reuse and sustainability projects reduce operational constraints and regulatory risk.
Strategic partnerships and M&A can let Intrepid Potash (ticker IPI) deepen U.S. market penetration through alliances with ag retailers and co-marketing with seed and crop-protection firms, tapping a global potash demand base of roughly 65–70 million tonnes annually (IFA range, 2023–24).
Targeted acquisitions of niche salts or brines can scale production and diversify feedstock with lower greenfield risk, accelerating revenue growth while preserving capital compared with greenfield builds.
Develop specialty premium potash and MgCl2 blends to capture part of the >$40B specialty fertilizer market (2024) and lift margins. Leverage US road salt demand ~18Mt/yr and $110B+ infrastructure funding to expand industrial offtake. Emphasize Buy American advantages and domestic ESG transparency to secure higher-margin public contracts. Pursue process-efficiency and M&A to cut costs vs imports and scale fast.
| Opportunity | 2024–25 data |
|---|---|
| Specialty market | >$40B (2024) |
| US road salt | ~18 Mt/yr (USGS) |
| Infrastructure funding | $110B+ (IIJA) |
| Global potash supply | 60–70 Mt/yr (IFA 2023–24) |
Canada supplies about one-third of global potash, while Russia and Belarus remain major exporters influencing pricing; currency and freight advantages allow their producers to undercut U.S. delivered prices. Renewed export flows in 2024 have periodically eased tightness and pressured benchmark MOP quotes. Sudden return of low-cost volumes can trigger sharp price declines, compressing margins for U.S.-only operators like Intrepid Potash.
Tighter rules on water use, brine management, and land impact can materially raise operating and capital costs for Intrepid Potash, potentially increasing opex and capital intensity over multiple years. Permitting delays, already cited in regional permitting processes in 2024, may constrain timely capacity changes and project ramp-ups. Significant and recurring compliance investments are likely, and non-compliance risks fines and operational interruptions that can hit production schedules.
Planting delays, droughts, or floods can sharply cut fertilizer application rates on the US corn crop—USDA reported 89.5 million planted corn acres in 2024—reducing potash demand and revenue. Warmer winters lower de-icing salt needs against US salt production of roughly 43 million tons (USGS 2024), shrinking seasonal sales. Extreme weather also disrupts transportation and mine operations, heightening revenue and inventory risk.
Rail, trucking, and diesel cost spikes in 2024 eroded delivered margins for Intrepid Potash, with U.S. diesel averaging near 4.00 per gallon driving higher freight spend; carrier constraints further risk shipment delays during spring planting and fall harvest peaks. Chemical and energy input inflation in 2024–2025 lifted production costs, while price pass-through in commoditized potash markets often lagged, compressing gross margins.
Trends toward lower input intensity, regenerative farming, and alternative nutrients threaten potash demand; IFA reported global potash consumption around 68 million tonnes K2O in 2023, while precision and variable-rate application can cut fertilizer use by 10–20%, reducing absolute tonnage even if yields hold.
Canada ~34% of global potash supply; Russia/Belarus export resumption in 2024 pressures prices and margins for U.S. players. Stricter water/brine/land rules and permitting delays in 2024 raise capex/opex risk. Weather extremes and planting shifts cut demand (USDA 89.5M corn acres 2024); diesel ~4.00/gal and input inflation squeeze delivered margins. Precision/regenerative adoption can reduce potash use 10–20% (IFA 68Mt K2O 2023).
| Threat | 2023–24 data | Impact |
|---|---|---|
| Low‑cost exports | Canada ~34% global | Price pressure |
| Regulation | Permitting delays 2024 | Higher capex/opex |
| Demand shock | US corn 89.5M acres | Lower tonnage |
| Input costs | Diesel ~$4/gal | Margin squeeze |


