
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
IRESS faces moderate buyer power, specialized supplier relationships, and intensifying competition from fintech entrants and established platform providers. Regulatory change and rapid tech adoption elevate substitute threats and lower barriers for niche newcomers. Scale, client entrenchment, and integrated offerings are key defenses shaping long-term margins. This brief snapshot only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore IRESS’s competitive dynamics, market pressures, and strategic advantages in detail.
IRESS depends on licensed exchange and aggregator feeds (eg Bloomberg, Refinitiv, ASX) with few alternatives, giving suppliers strong leverage over availability and pricing in 2024.
Contracts commonly include strict usage terms and annual price escalators (often 2–5%), and renegotiation or outages can directly hit product performance and margins.
Multi-sourcing mitigates risk but switching core feeds is costly and operationally risky, often requiring months of integration and potentially millions in transition costs.
Hosting and compute spend concentrates with hyperscalers (AWS ~32%, Azure ~24%, GCP ~11% in 2024), giving suppliers ~67% market control; colocation leaders further aggregate demand. Volume discounts exist, but egress fees (commonly $0.05–0.12/GB in 2024) and migration frictions sustain supplier leverage. Provider outages or security incidents propagate to service levels across clients. Architectural portability reduces but does not remove dependence.
Third‑party libraries, analytics engines and KYC/AML APIs are deeply embedded in IRESS workflows, and the 2024 RegTech market—estimated at $10.7 billion—reflects willingness to pay for certified, compliant solutions; niche providers can command premium pricing. Contract lock‑ins and version dependencies raise switching costs and vendor due diligence (often multi‑month) adds negotiation complexity and procurement friction.
Senior developers, quant engineers and regulatory experts remain scarce and mobile; US senior software engineer median base pay reached about $160,000 in 2024, increasing suppliers’ leverage. Wage inflation and competition from big tech (pay premiums ~20–30%) elevate hiring costs for IRESS, while knowledge concentration in legacy modules raises retention and single-point failure risk. Remote hiring expands talent pools but adds onboarding and coordination costs and latency.
Large IRESS deployments typically rely on system integrators for customization and change management; SI influence over timelines and scope directly affects project economics and can increase total cost of ownership. Limited pools of domain-capable teams push effective day rates materially higher; outcome-based contracting can realign incentives but is complex to implement.
In 2024 IRESS faces high supplier power: licensed market data providers and RegTech vendors command limited alternatives and premium pricing, while core feed swaps cost millions and months. Hyperscalers concentrate ~67% market share (AWS 32%, Azure 24%, GCP 11%), sustaining leverage via egress fees. Talent scarcity (US senior pay ~160,000) and specialist SIs further raise switching and operating costs.
| Supplier | Metric (2024) |
|---|---|
| Market data/RegTech | High lock‑in; RegTech market $10.7B |
| Hyperscalers | AWS 32% / Azure 24% / GCP 11% (67% total) |
| Talent | US senior pay ~$160,000; 20–30% pay premium |
 Detailed Word Document
Uncovers key competitive drivers for IRESS—customer and supplier power, threats from new entrants and substitutes, and disruptive forces—providing strategic insights on pricing, market positioning and defenses to protect market share for investor materials and internal strategy.

 Customizable Excel Spreadsheet
A concise, one-sheet Porter's Five Forces for IRESS that visualizes competitive pressures with a spider chart, lets you customize inputs for evolving market trends, and produces a clean, copy-ready layout—no macros required and easy to integrate into decks or Excel dashboards.
Banks, wealth managers and super funds leverage scale in RFPs to extract price concessions and bespoke SLAs; Australia’s Big Four banks hold roughly 80% of domestic banking assets, concentrating procurement clout. Major superannuation pools — collectively managing around A$3.5 trillion — provide high reference value that forces periodic repricing. Multi‑year renewals deliver revenue stability for IRESS but invite scheduled repricing pressure every renewal cycle.
Deep integrations, data migration and retraining keep switching costs high—IRRSS-style platforms reported 76% recurring revenue in FY24, moderating buyer power by locking in clients. Yet APIs, open data standards and cloud delivery are lowering exit barriers; enterprise API usage grew ~30% year-on-year in 2024. Proofs of concept and phased migrations cut perceived risk and time-to-value, while buyers leverage credible alternatives to negotiate discounts.
Clients demand stringent uptime, cyber and regulatory reporting commitments—IBM's 2023 report pegs average data breach cost at $4.45M and downtime is often cited around $300k/hr—so SLA penalties and audit rights shift material risk to IRESS. Meeting these requirements raises cost-to-serve, narrows pricing flexibility, and while premium assurance can command higher fees, it also lifts baseline client expectations.
Buyers of IRESS (ASX:IRE) increasingly focus on total cost of ownership in 2024, assessing license fees plus implementation, upgrade and ops overhead; bespoke feature requests often cause scope creep unless disciplined pricing and change-control are enforced. Modular pricing and standardized configurations reduce discount pressure, while ROI and productivity metrics strengthen seller leverage.
Banks, wealth managers and super funds (Big Four ~80% of banking assets; super pools ~A$3.5T) exert strong price leverage in RFPs. High switching costs (IRSS platforms 76% recurring revenue in FY24) offset customer power, but API adoption (+30% y/y in 2024) and modular offers reduce exit barriers. Clients press SLAs, uptime and TCO, driving disciplined change-control and ROI proofs.
| Metric | 2024 |
|---|---|
| Big Four market share | ~80% |
| Super funds AUM | A$3.5T |
| Recurring rev (IRSS) | 76% FY24 |
| Enterprise API growth | ~30% y/y |
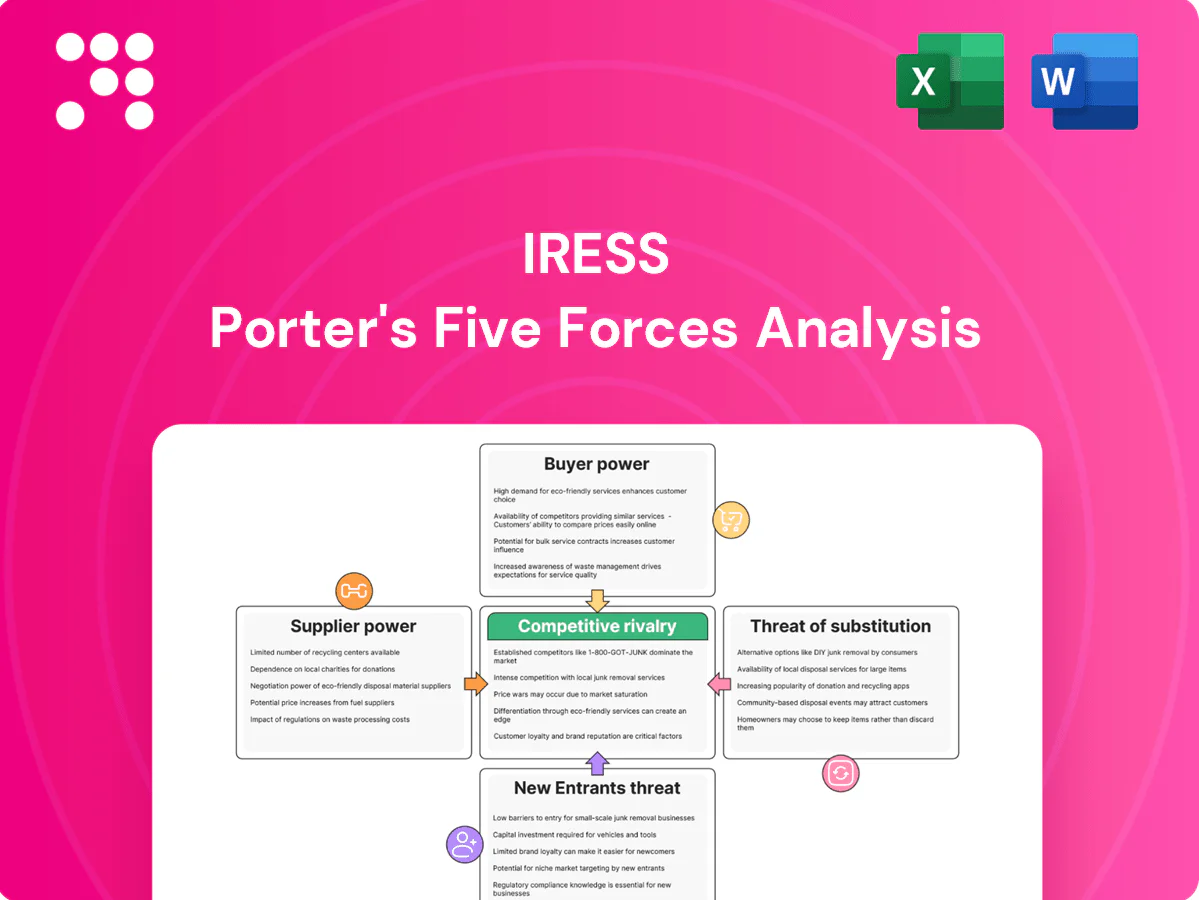
This preview shows the exact IRESS Porter's Five Forces analysis you'll receive—no placeholders or samples. The document is fully formatted, professionally written, and includes buyer-focused insights on competitive rivalry, supplier and buyer power, threats of entry and substitutes. Upon purchase you get instant access to this identical file, ready for download and use.
Diverse, well-capitalized competitors — from Bloomberg (about 325,000 Bloomberg Terminal users) to LSEG/Refinitiv, SS&C and FIS — contest both global and regional segments, driving product investment and aggressive pricing. Capital depth lets incumbents sustain R&D and M&A, while many clients keep multiple systems, intensifying feature competition. Differentiation rests on seamless workflows, breadth of coverage and premium service.
Adjacent categories converge in 2024, driving more head-to-head encounters across wealth, trading and data as vendors expand suites into neighboring segments. Rivals increasingly cross-sell into incumbent accounts, raising retention pressure and often shifting revenue mix toward bundled offerings. Bundled suites frequently undercut standalone modules on price-value, forcing modular vendors to defend with niche product excellence and deeper specialization.
Subscription tiers, per-user pricing and usage-based data fees make vendor offerings directly comparable, driving price-led competition; in practice competitive bids and renewal cycles commonly see discounts in the low double digits. Rivals deploy bundling to obscure effective rates, often shifting value into services or data add-ons. Clear articulation of outcome-based value and outcomes-based pricing protects margins and improves net retention.
Frequent 2024 regulatory updates force IRESS to deliver continuous product refreshes, making faster release cycles a clear competitive weapon; lagging on new rules or digital channels increases client attrition risk. Investment in compliance roadmaps and delivery pipelines has become a primary rivalry battleground, with industry surveys in 2024 showing most firms prioritise regulatory tech and faster releases.
Service quality and implementation speed are decisive in vendor selection: rapid time-to-value and responsive support shorten sales cycles and block competitors when migrations complete on schedule, while delays in customization or migration create immediate win-back opportunities.
Diverse, well-capitalized rivals (Bloomberg ~325,000 Terminal users) and suites from LSEG/Refinitiv, SS&C and FIS drive intense feature and price competition, with renewal discounts commonly in the low double digits (10–15%). 2024 convergence across wealth, trading and data increases cross-sell and bundled offers, pressuring modular vendors. Faster regulatory-driven release cadence and implementation speed are decisive in retention and win-backs.
| Metric | 2024 |
|---|---|
| Bloomberg Terminal users | ~325,000 |
| Typical renewal discount | 10–15% |
| Primary rivalry lever | Release cadence, bundling, service |
Entrants face complex, evolving financial regulations and certifications across jurisdictions, raising compliance costs and time-to-market. Obtaining exchange connectivity and proprietary data licenses is nontrivial and often requires long procurement cycles. Deep integration with client cores, custodians and OMS/EMS systems increases technical and operational entry costs. Building trusted domain credibility typically takes several years of track record and client references.
Financial clients demand rigorous security posture, audits, and uptime histories, often requiring vendor uptime targets in the 99.9–99.999% range and certified controls such as SOC 2 or ISO 27001; IBM's 2024 Cost of a Data Breach Report puts the global average breach cost at about $4.45M and higher for financial firms. New entrants must invest heavily in cybersecurity and BCP to pass due diligence, since one incident can halt onboarding and sales cycles, making established track records a strong moat.
Cloud platforms cut upfront infrastructure, enabling MVPs in weeks and lowering initial CAPEX, yet enterprise-grade scale, support and regulatory compliance still demand multi-million-dollar investments; large vendors report ongoing ops spend in the low millions annually. Long sales cycles of 9–18 months and CAC payback horizons >12 months strain startup cash flows. Access to patient capital and strategic partnerships therefore becomes decisive for entrants.
Key datasets often carry high fees and exclusive terms—Bloomberg terminals cost ≈$27,000/year (2024) and exchange direct-feed contracts can run into millions annually—so newcomers without comprehensive data struggle to match incumbent product breadth. Building proprietary datasets takes years and significant capex, while open standards (eg FIX, OpenAPI) help but rarely fully substitute for exclusive real‑time feeds.
Entrants face strong incumbent retaliation at IRESS through price responses, product bundling, and accelerated roadmaps; IRESS reported FY2024 revenue ~AUD 700m, enabling sustained R&D and competitive pricing pressure. High client switching costs and deep integrations across wealth, trading and market data slow adoption of alternatives. Partner ecosystems and marketplaces reinforce lock-in, leaving niche wedges with clear differentiation as the typical entry path.
Entrants face high compliance, data and integration costs (Bloomberg ≈$27,000/yr; exchange feeds: multi‑million), plus cybersecurity investments (avg breach cost $4.45M, 2024). Cloud lowers CAPEX but enterprise scale requires multi‑million ops; sales cycles 9–18 months. IRESS scale (FY2024 revenue ≈AUD700m) enables aggressive retaliation and strong client lock‑in.
| Metric | 2024 |
|---|---|
| Bloomberg terminal | ≈$27,000/yr |
| Avg breach cost | $4.45M |
| IRESS revenue | ≈AUD700M |


