
Digital download
Access the files immediately after checkout.
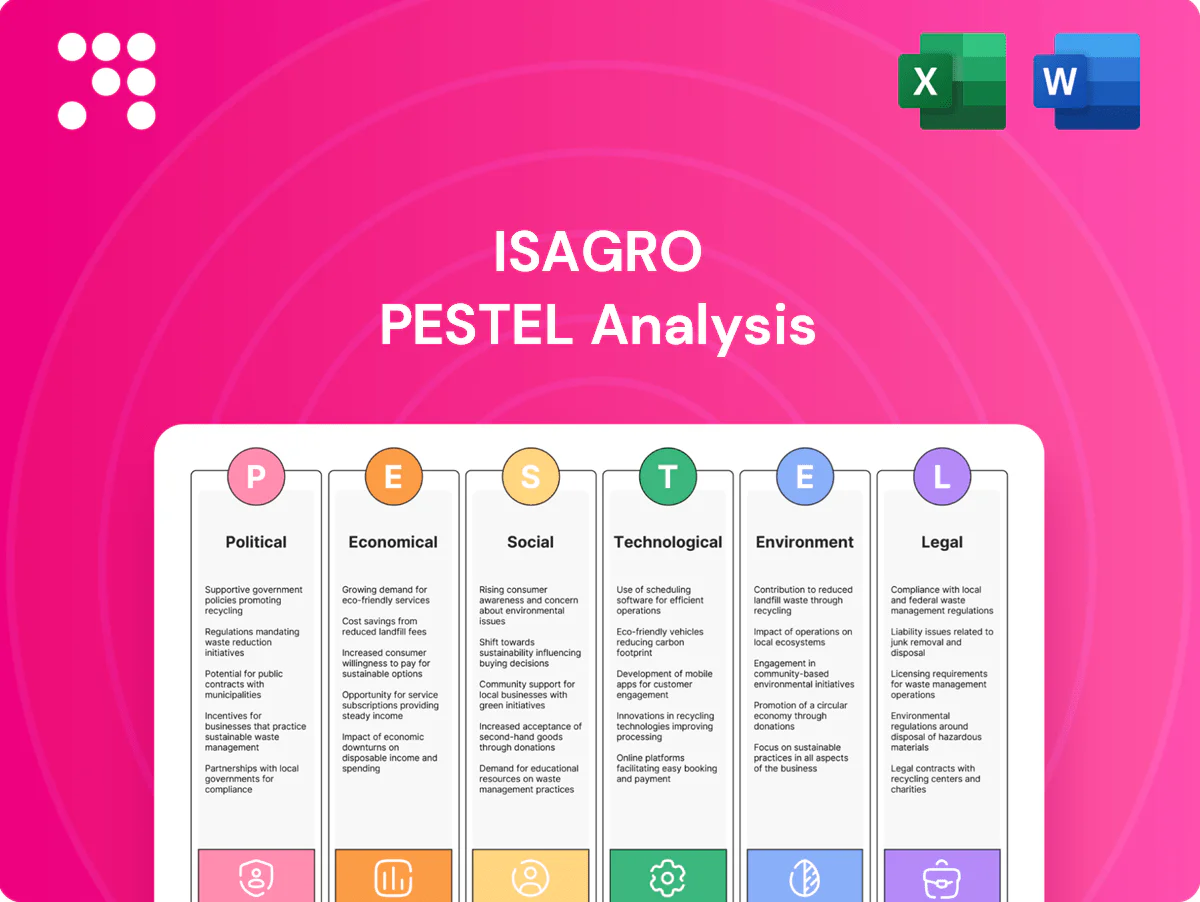
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
Unlock strategic clarity with our concise PESTLE Analysis of Isagro—highlighting regulatory, economic, and environmental forces shaping its growth and risks. Ideal for investors and strategists, this report turns complex trends into actionable steps. Purchase the full analysis to access detailed insights and ready-to-use recommendations.
The EU Green Deal and Farm to Fork target a 50% reduction in chemical pesticide use and risk by 2030, forcing portfolio shifts; Isagro must accelerate lower-toxicity and biological solutions to retain approvals. Policy incentives via Horizon Europe (€95.5bn) and the CAP (≈€386.6bn 2021–27) can fund sustainable R&D, but compliance costs will rise. Strategic engagement with EU bodies is critical to anticipate regulatory timelines and safeguard market access.
CAP 2023–27 allocates about €387 billion, directly shaping farmers’ input budgets and crop mix; CAP eco‑schemes and the Sustainable Use Directive push integrated pest management, shifting demand toward biostimulants and selective chemistries. Isagro can market subsidy‑aligned products; 7‑year CAP cycles require adaptable go‑to‑market planning.
Tariffs, non-tariff barriers and sanitary-phytosanitary rules materially affect export of active ingredients and formulations in the global crop protection market (≈USD 66 billion in 2024), raising costs and delaying shipments. Divergent MRLs — governed in the EU by Regulation (EC) No 396/2005 and differing from US EPA and China tolerances — can block cross-border sales. Isagro needs diversified registration footprints across key markets and strategic local partnerships to mitigate geopolitical shocks and speed approvals.
Public grants and tax credits can materially offset Isagro R&D costs; aligning to Horizon Europe (budget €95.5bn for 2021–27) and NextGenerationEU (€723.8bn) green-transition calls increases co‑funding chances and reduces net burn. National and EU programs now prioritize biologicals and precision ag, so targeting eligible calls speeds validation and market entry, accelerating new molecule and bio‑solution pipelines.
Stable governance in Isagro core markets like the EU and Brazil improves regulatory predictability, supporting consistent registration and market access timelines.
Heightened enforcement against counterfeit agrochemicals—driven by EU and national customs actions—shapes competitive dynamics and raises compliance costs for illicit players.
Isagro benefits from strong IP protections and border controls that limit illicit competition, though expansion into emerging markets requires additional compliance oversight and localized enforcement monitoring.
EU Green Deal targets 50% pesticide risk reduction by 2030; Isagro must pivot to lower‑toxicity and biologicals. CAP ≈€387bn (2021–27) and Horizon Europe €95.5bn (2021–27) steer subsidies and R&D; NextGenerationEU €723.8bn funds green transition. Global crop protection market ≈USD66bn (2024); divergent MRLs and stronger enforcement raise compliance and registration costs.
| Political Factor | Key Metric | Implication |
|---|---|---|
| EU Green Deal | 50% reduction by 2030 | Shift to biologicals |
| CAP | ≈€387bn | Farmer subsidies affect demand |
 Detailed Word Document
Explores how external macro-environmental factors uniquely affect Isagro across six dimensions—Political, Economic, Social, Technological, Environmental, and Legal—each section backed by data and current trends to identify threats and opportunities. Designed for executives and investors, it offers forward‑looking insights and ready‑to‑use formatting for reports and decks.

 Customizable Excel Spreadsheet
A concise, visually segmented Isagro PESTLE summary that clarifies external risks and market drivers at a glance, easily dropped into presentations or shared across teams. Editable notes and simple language let users tailor insights to regions or business lines, speeding alignment and decision-making during planning sessions.
Commodity price swings strongly affect farmer purchasing power and input intensity; fertilizer prices fell about 40% from 2022 peaks to 2024 (World Bank), enabling higher input use when prices recover. High commodity prices support sales of premium Isagro formulations, while low prices drive down‑trading. Isagro needs tiered product lines plus flexible financing and in‑season promotions to stabilize demand.
Input cost inflation—solvents, intermediates and energy—remains a margin risk for Isagro after European industrial electricity fell roughly 30% from 2022 highs but input prices stayed elevated; global container rates normalized to about USD 2,000 in 2024, exposing freight-driven cost volatility. Supply shocks and freight spikes can squeeze profitability, so Isagro should secure strategic suppliers and apply hedging where feasible. Formulation optimization can reduce raw-material intensity by up to 10%, improving resilience.
Euro trading near 1.08 USD in July 2025 directly affects Isagro export competitiveness and the cost of imported active ingredients and equipment. Multi-currency exposure requires prudent hedging via forwards and options to lock margins and manage cash flows. Pricing must reflect customer FX pass-through tolerance, and contracts can include indexation or adjustment clauses to share volatility risks.
Industry consolidation concentrates distribution and R&D: the top five agrochemical players now control roughly 65% of global crop protection sales, tightening shelf-space access and negotiating leverage against smaller firms. Isagro can pivot to niche crops, specialty formulations and co-development deals while forming distributor alliances to preserve market reach.
Population growth (UN proj. 9.7 billion by 2050) and static arable land per capita sustain crop protection demand; buyers now demand ROI with lower environmental impact. Isagro’s biostimulants and selective chemistries can command price premiums, but broad adoption depends on demonstrated field performance and measurable yield gains.
Fertilizer prices fell ~40% 2022–24 (World Bank), boosting input use; high commodity levels favor premium Isagro sales while lows drive down‑trading. Input inflation (solvents, energy) still risks margins despite EU industrial electricity ~30% below 2022; global container rates ~USD 2,000 in 2024. EUR ≈1.08 USD (Jul 2025) affects export competitiveness; top‑5 firms ≈65% market share. UN projects 9.7B by 2050; biostimulants ≈$3.8B (2023).
| Metric | Value |
|---|---|
| Fertilizer change 2022–24 | −40% |
| EUR/USD (Jul 2025) | 1.08 |
| Top‑5 market share | ≈65% |
| Biostimulants (2023) | $3.8B |
| Container rate (2024) | ≈$2,000 |
The preview shown here is the exact Isagro PESTLE Analysis document you’ll receive after purchase—fully formatted and ready to use. The content, structure and insights visible are the final file with no placeholders or edits. After payment you’ll download this same, professionally structured report instantly.
Rising consumer demand for residue-free and organic produce—reflected in a global shift toward sustainable sourcing—pushes down acceptable pesticide presence and forces retailers to set private MRLs tighter than legal limits. EFSA reported 97.2% of samples within legal MRLs in 2022, highlighting scrutiny on the remaining 2.8% non-compliant cases. Isagro must prioritize low-residue chemistries, clear stewardship programs and transparent residue data sharing to maintain market access and buyer trust.
Risk-averse growers demand demonstrated efficacy and compatibility, so peer trials, demo plots and advisory support are primary levers driving conversion. Isagro should bundle agronomic services with products to shorten adoption cycles and address on-farm variability. Design for ease of use and tank-mix flexibility to lower practical barriers and increase repeat purchases.
Rural labor shortages—EU farm employment about 4.4% of total employment in 2023 (Eurostat)—push mechanization and simplified spray programs, increasing demand for products that reduce field passes. Products enabling fewer passes or precision application gain favor, supporting Isagro moves into long-lasting, easy-to-apply formulations. Training materials should minimize handling complexity to accelerate adoption and lower labor time per hectare.
Operator safety expectations are rising globally, driving demand for low-odor, low-dermal-exposure chemistries and closed-transfer systems; Isagro can differentiate through safer handling profiles and product reformulation. Certifications and stewardship programs (GHS adopted in 67+ countries) reinforce credibility and market access, supporting premium pricing and reduced liability.
Sustainability branding shapes buyer choices and partnerships as EU CSRD reporting obligations began phasing in from 2024, pushing partners to demand verifiable ESG data; documented environmental benefits enable premium positioning and better B2B contract terms. Isagro should quantify impacts using LCA metrics per ISO 14040/44 to substantiate claims, and third-party labels such as the EU Ecolabel can enhance market access.
Rising demand for residue-free/organic produce (EFSA: 97.2% MRL compliance in 2022) forces tighter private MRLs and low-residue chemistries. Risk-averse growers and EU farm employment at 4.4% (2023) favor bundled agronomy, demo trials and easy-to-apply, fewer-pass products. Stronger safety/ESG scrutiny (CSRD phased from 2024; GHS in 67+ countries) rewards verified LCA claims and stewardship.
| Metric | Value |
|---|---|
| EFSA MRL compliance | 97.2% (2022) |
| EU farm employment | 4.4% (2023) |
AI-aided design and high-throughput screening can shorten discovery cycles by 30–50% and HTS platforms screen 10^4–10^6 candidates weekly; resistance-breaking modes of action are a priority as field resistance incidents rise. Isagro should integrate computational chemistry with genomics/proteomics datasets to prioritize leads, while external partnerships and licensing (industry accounts for >30% of late-stage assets) de-risk pipelines.
Microencapsulation, controlled-release and advanced adjuvant systems increase active ingredient efficacy and reduce off-target drift, supporting the EU Farm to Fork target of 50% pesticide use reduction by 2030. Formulation technology enables lower dose rates and fewer applications, improving cost per hectare and environmental profile. Isagro can tailor delivery profiles to crop and climate needs, while formulation patents and proprietary platforms extend product lifecycle value.
Microbial and botanical solutions fit regulatory and consumer trends, with the EU Fertilising Products Regulation (EU) 2019/1009 enabling CE-labelled biostimulants and the segment growing at about 11% CAGR (2018–2024). Production scale-up and product stability remain key hurdles, pushing Isagro to target robust QC and shelf-life benchmarks (≈12 months). Field consistency variability and formulation challenges mean combining bio with chemistries to create integrated programs is essential.
Sensors, satellite data and variable-rate technology enable optimized application timing, lowering inputs and improving efficacy; precision‑ag market hit about $9B in 2024 and adoption of VRT/sensor systems rose ~20% year‑on‑year. Decision‑support tools typically lift product ROI 15–25% and reinforce stewardship; Isagro can embed prescriptive recommendations in digital platforms while data partnerships can cut churn ~10%.
Manufacturing automation—advanced process control, PAT and robotics—raises batch-to-batch quality and lowers unit costs; industrial robot shipments grew about 11% in 2023 (International Federation of Robotics), supporting efficiency gains.
Safer, automated plants reduce incidents and unplanned downtime, improving OEE and protecting margins.
Isagro should modernize toward modular, flexible lines to enable faster changeovers for specialty batches and capture premium margins.
AI/HTS shorten discovery 30–50% and prioritize resistance‑breaking MOAs; precision‑ag $9B (2024) with VRT +20% YoY raising product ROI 15–25%. Microbial/botanical ~11% CAGR (2018–24) but scale/shelf (~12 months) constrain roll‑out. Automation (robotics +11% shipments 2023) and modular lines cut unit costs and speed changeovers.
| Tech | Impact |
|---|---|
| AI/HTS | Discovery −30–50% |
| Precision‑ag | $9B (2024); ROI +15–25% |
| Biologicals | ~11% CAGR; shelf ~12m |
| Automation | Robotics +11% (2023) |
EU and global registrations require extensive dossiers—often exceeding 1,000 pages—and market authorisations in the EU commonly take 3–5 years. Changing data requirements and post-submission requests can delay launches further. Isagro must plan multi-year regulatory roadmaps tied to 3–5 year cycles and allocate budget accordingly. Early engagement with authorities reduces surprises and shortens review risks.
REACH mandates registration for substances manufactured or imported above 1 tonne/year; substance evaluation, exposure scenarios and reporting are compulsory, with the ECHA candidate list already exceeding 200 SVHCs. Non-compliance can trigger enforcement actions including market withdrawal and financial penalties under member-state law. Isagro therefore needs rigorous data management, regular audits and contractual alignment with supply‑chain partners on obligations.
Patents provide up to 20 years of protection while regulatory data exclusivity for agrochemicals commonly yields around 10 years of market protection, securing returns on Isagro’s R&D investments. Evergreening through new formulations and uses extends commercial coverage beyond base patents. Isagro must actively monitor freedom to operate and be prepared to defend rights in key markets. Strategic licensing can monetize non-core IP assets and capture additional revenue streams.
Adverse events can trigger legal claims and reputational damage under EU pesticide law (Regulation (EC) No 1107/2009) and EFSA oversight, exposing manufacturers to enforcement and civil liability.
Clear labels, operator training and fast complaint handling reduce exposure; Isagro should adopt pharmacovigilance-like surveillance and root-cause case management.
Comprehensive product liability insurance plus batch-level traceability and supply‑chain records materially strengthen resilience.
EU CSRD expands reporting duties from about 11,700 to roughly 50,000 EU companies with phased application 2024–2026, and explicitly brings supply‑chain due diligence and Scope 3 metrics into scope; Isagro must build auditable data pipelines and governance to track value‑chain impacts. Non‑financial KPIs will materially influence investor access and cost of capital.
Isagro faces 3–5 year EU approval timelines, REACH with >200 SVHCs and penalties for non‑compliance, patents 20y/data exclusivity ~10y, and CSRD expanding to ~50,000 companies with Scope 3 (>70% agribusiness emissions) reporting needs; robust data governance, insurance, traceability and early regulator engagement are essential.
| Item | Key figure |
|---|---|
| EU approvals | 3–5 yrs |
| REACH SVHCs | >200 |
| CSRD scope | ~50,000 firms |
Extreme weather alters pest pressure and disease cycles, with FAO estimating pests and diseases cause 20–40% of global crop losses; global average temperature is about 1.1°C above pre‑industrial levels (IPCC). Product demand shifts seasonally and regionally, forcing Isagro to maintain adaptable portfolios and faster supply responses to pest spikes. Stress‑mitigation biostimulants are rising, with the global biostimulants market ~4.5 billion USD in 2024 and ~10–12% CAGR expected.
Pollinator and beneficial insect safety face high regulatory scrutiny under the EU Sustainable Use Directive 2009/128/EC and EFSA ecotoxicology guidance (honey bee guidance updated 2013/2018), pushing Isagro to prioritize selective modes and precise application timing to limit non-target impacts. Isagro should generate robust ecotox datasets and clear label guidance; member states increasingly mandate buffer zones and drift-control measures to reduce off-target exposure.
Runoff and leaching risks are tightening regulation, reinforced by the EU Farm to Fork target to reduce pesticide use and risk by 50% by 2030. Low-PPM, soil-friendly formulations are favored by buyers and regulators. Isagro can prioritize low-mobility actives and safeners to lower off-target movement. Stewardship programs with training and residue monitoring support compliant use.
Packaging take-back and recyclability are rising expectations across EU markets, where packaging waste reached about 79.3 million tonnes in 2020 (Eurostat), pushing regulators and buyers toward circular solutions.
Concentrates and refill systems reduce plastic use and transport volumes, with industry case studies showing packaging and logistics cuts often in the 30–70% range; Isagro should redesign packs and join collection schemes.
LCA-led product and pack choices can lower cradle-to-gate footprints materially; many LCAs report 20–40% GHG reductions from lightweighting, refill and material shifts.
Energy-intensive synthesis in crop science raises Isagro’s Scope 1 and 2 CO2e, with the chemical sector responsible for around 5% of global CO2 emissions, highlighting material exposure to energy costs and carbon pricing in 2024–25. Transitioning to green-chemistry pathways and procuring renewable power can materially lower CO2e, while SBTi-aligned targets provide a credible framework to measure and report progress. Optimising logistics and distribution networks further trims fuel-related emissions and operating costs.
Climate-driven pest shifts threaten yields (FAO 20–40% losses) as global temp ≈+1.1°C (IPCC), boosting demand for biostimulants (global market ~4.5bn USD in 2024, ~10–12% CAGR). EU rules (Farm to Fork −50% pesticide risk by 2030, pollinator safeguards) and packaging pressure (79.3 Mt waste EU 2020) force low‑mobility actives, refill systems and LCA‑led design. Chemical sector ≈5% of global CO2e, pushing renewables, green chemistry and SBTi targets.
| metric | value |
|---|---|
| pest losses | 20–40% |
| temp rise | +1.1°C |
| biostimulants | $4.5bn (2024) |
| EU packaging | 79.3 Mt (2020) |
| chem CO2e | ~5% |


