
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
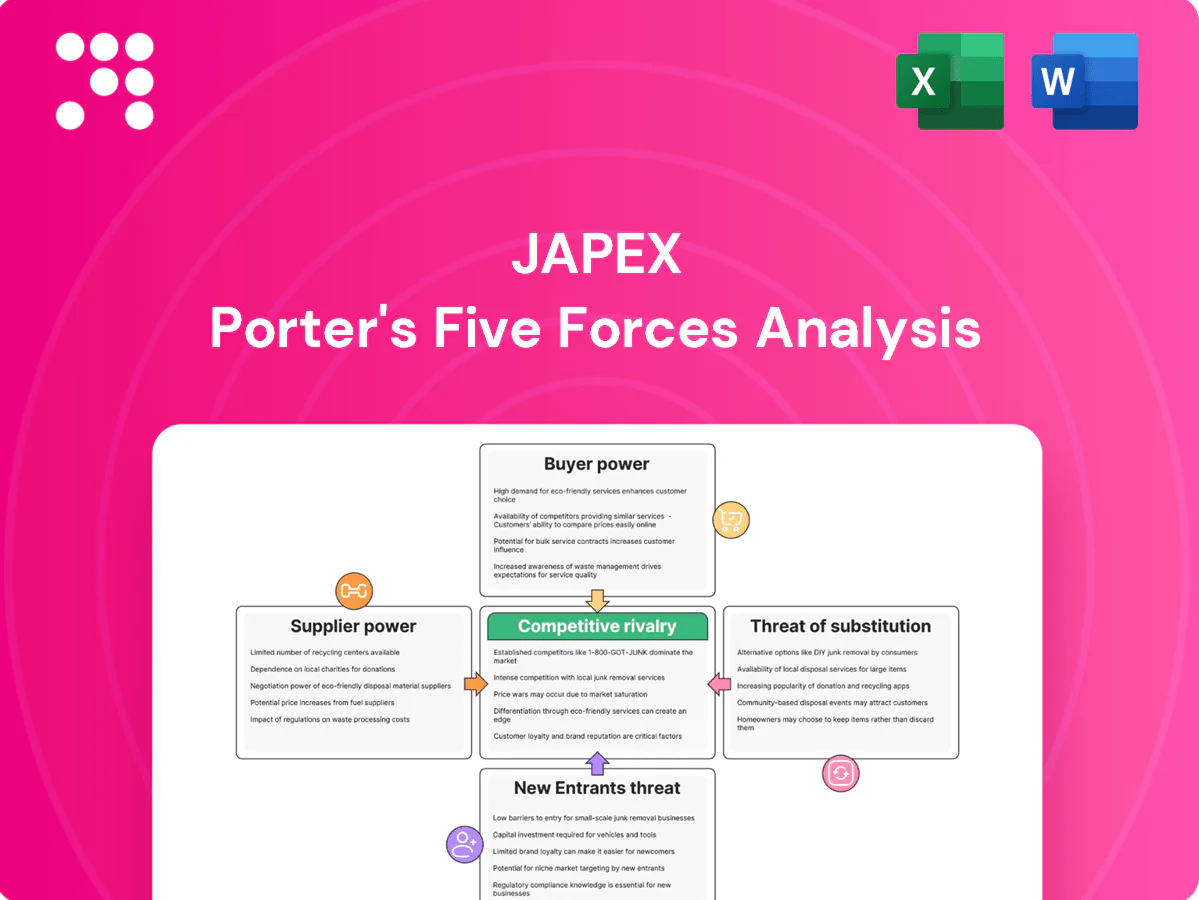
Japex’s Porter’s Five Forces snapshot highlights supplier leverage, buyer dynamics, new entrant barriers and substitute pressures shaping its energy market standing. Against tightening regulations and capital intensity, competitive intensity is moderate-to-high. Strategic levers and risk exposures are identified. This brief snapshot only scratches the surface—unlock the full Porter's Five Forces Analysis to explore Japex’s competitive dynamics in detail.
JAPEX depends on host governments for exploration licenses, fiscal terms and approvals, giving sovereigns substantial leverage; Japan imports roughly 90% of its energy (2023–24), amplifying strategic importance of access. Concession terms, local content rules and taxation can shift project NPV rapidly. Negotiation power rises in geopolitically attractive basins or amid resource nationalism. Stable JV structures and long-term state ties partially mitigate this leverage.
Specialized drilling, seismic and completion services are concentrated: the global oilfield services market was about $240 billion in 2024, with the top three providers capturing roughly 50% of revenue, raising switching costs and enabling higher day rates in upcycles. Tight capacity and rig/utilization levels near 80–90% plus lead times of 12–24 months for rigs, subsea gear and pressure-control systems can delay projects. JAPEX’s project phasing and framework contracts help temper pricing spikes, while HP/HT and geothermal technology differentiation further strengthens supplier power.
Access to LNG carriers, FSRUs, and regas capacity is constrained and cyclical, tightening in peak seasons; the global fleet surpassed 700 LNG carriers and about 40 FSRUs in 2024, but utilization spikes cause local shortages. Charter rates and terminal slots can become bottlenecks, giving logistics providers pricing power during peaks. JAPEX’s in-house transportation and storage reduce but do not eliminate exposure to spot shortages. Long-term charters and multiple port options hedge availability risk.
For refining, gas-processing and geothermal projects a concentrated set of EPC firms and OEMs (GE, Siemens, MHI) gives suppliers strong leverage; industrial gas-turbine lead times stretched to roughly 12–18 months in 2023–24, raising costs and delay risk. Performance guarantees and modular designs can shift leverage back; localization and multi-vendor sourcing lower single-point dependence.
Supplier power is high: host governments control licenses and fiscal terms, with Japan importing ~90% of energy (2023–24). Oilfield services are concentrated (top 3 ≈50% of $240bn market, 2024), rig/utilization ~80–90% raising lead times. Skilled-staff shortages flagged by ~70% of upstream firms (2024) sustain wage pressure.
| Metric | 2023–24 |
|---|---|
| Japan energy imports | ~90% |
| OFS market | $240bn; top3 ~50% |
| Rig util. | 80–90% |
| Skilled shortage | ~70% |
 Detailed Word Document
Tailored Porter's Five Forces analysis for Japex that uncovers competition drivers, supplier and buyer power, entry barriers, substitutes and emerging threats to its market position.

 Customizable Excel Spreadsheet
Concise Japex Porter's Five Forces snapshot—quickly identify supply, buyer, entrant and regulatory pressures to simplify strategy decisions and slide-ready summaries.
Japanese utilities and city-gas companies, serving roughly 27 million gas households and accounting for about 20% of global LNG imports in 2024, exert strong bargaining power through scale and procurement expertise. They demand flexible offtake, price reviews and destination freedom, forcing JAPEX to offer competitive JKM-linked or hybrid pricing. Long-term reliability and verified ESG performance can support modest contract premiums.
Industrial and refining customers benchmark feedstock to global indices (JKM), which softened to roughly $8/MMBtu in late 2024, heightening margin pressure for suppliers. Low switching costs let customers move among fuels or suppliers with minimal process changes, raising their bargaining power. JAPEX mitigates this via bundled supply contracts, logistics reliability and quality guarantees. Offering efficiency services tied to energy sales raises customer stickiness and reduces churn.
Transparent commodity pricing—Brent/Dubai for oil and JKM/TTF-linked structures for gas—anchors JAPEX negotiations, limiting pricing discretion; Brent averaged about $84/bbl in 2024 and JKM roughly $13/MMBtu in 2024, tightening seller margins. Frequent price reviews and pass-through clauses shift volatility risk back to producers, so JAPEX uses hedging and portfolio diversification to manage exposure. Buyers often demand optionality in contract terms, increasing contract complexity and execution risk.
Buyers increasingly demand lower-carbon molecules, GHG disclosures and methane intensity targets, raising compliance costs and creating leverage to negotiate price and contract terms; Japan’s 2050 net-zero commitment continues to drive corporate procurement standards in 2024. JAPEX’s geothermal and low-carbon initiatives can differentiate offers and support premium pricing or preferred-contractor status. Carbon-neutral cargoes and third-party certification are trending toward becoming table stakes.
Buyers prize suppliers who guarantee delivery reliability, seasonal swing capacity and storage access, rewarding uptime with long-term contracts while penalizing delivery failures through fines and reputational loss, which raises buyer leverage before contracts are signed. JAPEX’s ownership and control of transport and storage assets enhances its ability to meet flexibility demands and reduce penalty exposure. Diversified sourcing in buyers’ portfolios lowers concentration risk and weakens single-supplier bargaining power.
Japanese utilities/city-gas (27m households) and buyers accounting for ~20% of global LNG imports in 2024 exert strong bargaining power, pushing JKM-linked or hybrid pricing; Brent averaged $84/bbl and JKM ~$13/MMBtu in 2024. Low switching costs and index benchmarking compress margins; JAPEX uses logistics, storage, hedging and low-carbon projects to secure premiums and long-term deals.
| Buyer group | 2024 metric | Bargaining leverage | JAPEX response |
|---|---|---|---|
| Utilities/city-gas | 27m hh; ~20% global LNG | High | Flexible offtake, reliability |
| Industry/refiners | JKM ~$13/MMBtu | Benchmarking | Bundled services, hedging |
This preview shows the exact Japex Porter’s Five Forces Analysis you'll receive immediately after purchase—no surprises or placeholders. The document displayed here is fully formatted, professional, and ready for download and use the moment you buy. You're looking at the actual deliverable; once payment is completed you'll get instant access to this same file.
Japan’s upstream and LNG sector features capable incumbents—INPEX (operator of the Ichthys LNG project, 8.9 mtpa capacity), JX Nippon/ENEOS and major trading houses—that compete aggressively for acreage, LNG volumes and utility contracts. Domestic players vie for a share of Japan’s large LNG market (roughly 70 mtpa import scale in 2024). JAPEX differentiates through extensive domestic gas infrastructure and an accelerated geothermal push, while JV collaboration often tempers direct rivalry.
International IOCs and independents bring scale and advanced E&P technology that lower unit costs and intensify competition for global tenders. NOCs control roughly 75% of world oil and gas reserves (2024), dominating access in resource-rich regions and squeezing independents. JAPEX routinely enters joint ventures to access projects and share capital and operational risk, while niche basins and brownfield optimization remain viable competitive angles.
Rivalry intensifies in downcycles as firms chase limited capex and offtake, compressing margins—Brent averaged about 80 USD/bbl in 2024, tightening cashflows and prompting price cuts to secure contracts. In upcycles service bottlenecks curb volumes available to win, lifting dayrates and margins for operators with capacity. JAPEX’s balanced portfolio and hedging programs smooth participation, reducing revenue volatility. Countercyclical investments can capture share when peers retrench, as seen in prior post-downturn recoveries.
As JAPEX diversifies, it competes with specialized geothermal and renewable IPPs where victory hinges on permitting speed, resource assessment accuracy, and EPC execution; Japan had roughly 540 MW of installed geothermal capacity in 2024, keeping projects scarce and competition tight. JAPEX’s subsurface expertise and local ties lower exploration risk, while access to feed-in tariffs and growing corporate PPAs (rising interest in 2024) intensifies rivalry.
Competitive rivalry in JAPEX’s sectors is high: Japan LNG imports ~70 mtpa (2024) with incumbents like INPEX (Ichthys 8.9 mtpa) and trading houses competing for contracts; NOCs hold ~75% of global reserves (2024), squeezing independents. Downcycles compress margins (Brent ~80 USD/bbl in 2024) while tech/digital spend (+18% to $7.1B in 2024) and geothermal scarcity (≈540 MW installed, 2024) raise stakes for execution and permitting.
| Metric | 2024 Value |
|---|---|
| Japan LNG imports | ≈70 mtpa |
| INPEX Ichthys capacity | 8.9 mtpa |
| NOC reserve share | ≈75% |
| Brent avg | ≈80 USD/bbl |
| Digital spend | $7.1B (+18%) |
| Geothermal capacity JP | ≈540 MW |
Expanded nuclear restarts in Japan, aligned with the government 2030 target of 20–22% nuclear in the power mix, can displace gas-fired generation and reduce LNG and pipeline gas offtake, creating substitute risk for JAPEX. Policy and safety approvals remain the swing factors determining restart pace. JAPEX faces volume risk in power-sector sales during periods of high nuclear availability, though long-term gas contracts and steady industrial demand provide a buffer.
Rapid growth in solar, wind and batteries is eroding gas and oil demand as renewables made roughly four fifths of global power capacity additions in 2023–24 and utility‑scale solar LCOE has fallen by more than 80% since 2010, increasing substitution pressure.
Declines in battery and storage costs—about a 90% drop since 2010—improve firm dispatchability and deepen electrification across transport and heat, further displacing hydrocarbons in some end‑uses.
JAPEX’s geothermal and renewables investments hedge this trend by capturing low‑cost baseload and variable generation value streams, while offering grid flexibility services that can complement rather than directly compete with fossil supply.
Heat pumps and electric boilers increasingly replace gas in buildings and industry, with global heat pump sales reaching about 20 million units in 2023 (IEA), directly cutting gas volumes where feasible. Tighter efficiency standards and appliance upgrades lower energy intensity and curb fossil demand. JAPEX can pivot to selling integrated energy solutions and electrification services rather than only molecules. Demand-side management and utility partnerships further reduce substitution-driven erosion.
Policy-backed pilots in Japan are advancing hydrogen and ammonia co-firing as substitutes for gas and coal, with government support scaling since 2021; green hydrogen LCOH ranged about US$3–6/kg in 2024, keeping costs and infrastructure as main barriers to large-scale uptake.
Biofuels and e-fuels can directly substitute refined oil in transport and aviation, driven by Japan's 2050 net-zero commitment and rising corporate net-zero targets; JAPEX can engage via blending, trading, or production partnerships to capture demand.
Expanded nuclear restarts (target 20–22% by 2030) and rapid renewables growth (≈80% of global capacity additions 2023–24) pose substitution risk to JAPEX, tempered by long‑term gas contracts and industrial demand. Solar LCOE is down >80% since 2010 and battery costs ~-90% since 2010, deepening electrification and heat-pump adoption (≈20m units sold in 2023). Green H2 LCOH ~US$3–6/kg (2024) keeps scale barriers.
| Metric | Value |
|---|---|
| Nuclear target (Japan) | 20–22% by 2030 |
| Renewables additions | ≈80% (2023–24) |
| Solar LCOE change | −>80% since 2010 |
| Battery cost change | ≈−90% since 2010 |
| Heat pump sales | ≈20m units (2023) |
| Green H2 LCOH | US$3–6/kg (2024) |
Exploration, drilling and LNG logistics demand very large upfront capital and specialized expertise—new greenfield LNG trains typically cost $5–10 billion and brownfield projects still run into multibillion-dollar ranges. Long project cycles often exceed 10 years and exploration well success rates hover around 20–30%, deterring entrants and protecting JAPEX’s core upstream positions. Access to experienced teams and long-standing contractor relationships further raises the bar.
Permitting, environmental reviews, and community engagement in Japan and abroad impose multi-year lead times and intensive local consultation. New entrants face substantial reputational and financial risks during protracted approvals. JAPEX, founded 1955, leverages decades of regulatory relationships and project track record. As of 2024, stronger ESG expectations act as a practical filter against underprepared entrants.
Prime acreage remains dominated by governments, NOCs, and incumbents via legacy concessions; in 2024 NOCs held roughly 80% of proven oil reserves. Midstream access is often capacity-constrained, raising gatekeeper risks for newcomers. JAPEX’s stakes in transport and storage create a defensive moat, protecting cash flows. New entrants typically accept minority JV roles to gain access to blocks and infrastructure.
Commodity swings strain newcomer balance sheets and debt covenants, making sustained capex during downturns difficult. Incumbents with diversified cash flows and existing LNG, oil and gas contracts can outlast price cycles. JAPEX’s asset portfolio and active hedging reduce vulnerability and support financing access. Banks prefer counterparties with proven execution histories, limiting fresh entrant credit lines.
In geothermal/renewables barriers are lower than offshore oil but still meaningful due to resource risk and EPC execution; Japan’s estimated geothermal potential ~23 GW (2024) keeps resource competition focused.
New IPPs and trading houses raise competitive pressure, but JAPEX’s subsurface know‑how, land access and O&M experience plus early site control and PPAs mitigate entry threats.
High capital intensity, decade-plus project cycles and ~20–30% exploration success rates keep entry barriers high, protecting JAPEX’s upstream positions. Regulatory, ESG and permitting lead times (multi-year) further deter newcomers; NOCs hold ~80% of proven reserves (2024). Geothermal/renewables lower barriers but Japan potential ~23 GW (2024) still concentrates competition.
| Metric | Value (2024) |
|---|---|
| Greenfield LNG capex | $5–10B |
| Project cycle | >10 years |
| Exploration success | 20–30% |
| NOC reserve share | ~80% |
| Japan geothermal potential | ~23 GW |


