
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
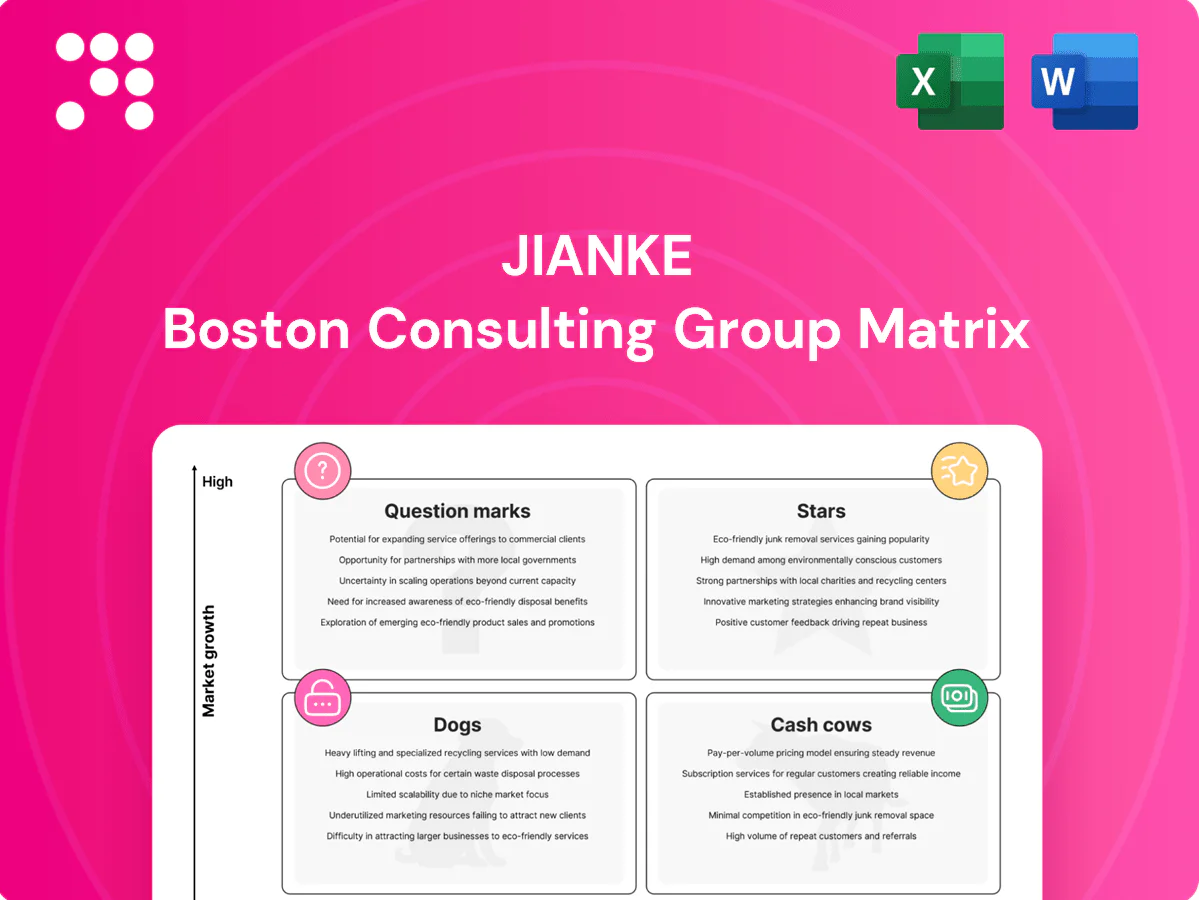
The Jianke BCG Matrix quickly shows which products are Stars, Cash Cows, Question Marks, or Dogs—giving you a sharp snapshot of where value and risk live. This preview teases the quadrant logic; buy the full BCG Matrix to get precise placements, data-backed recommendations, and a clear roadmap for capital allocation. You’ll get a ready-to-use Word report plus a high-level Excel summary so you can present and act fast. Purchase now for the strategic clarity your leadership team needs.
High growth demand is driven by the chronic disease burden—WHO reports noncommunicable diseases account for roughly 74% of deaths globally in 2024—making Jianke’s chronic disease management hub a Stars candidate with sticky, long‑term users. Jianke controls the patient journey from consult to script to refill, but sustaining that lead requires heavy investment in care teams and product polish. Management must keep funding to defend share as the market expands; if momentum holds, the hub can mature into a cash cow once growth cools.
E-prescription plus teleconsult follow-ups sit in a fast-growing, regulated, trust-driven segment where Jianke has traction; the global telemedicine market was about 90 billion USD in 2023 with roughly 20% CAGR into 2024–27. It consumes cash for compliance, physician supply, and patient acquisition, pressuring near-term margins. The payoff is category leadership that raises switching costs. Maintain share now to bank future margins.
Auto-refill subscriptions capture recurring revenue amid a rapid offline-to-online shift; the global e-pharmacy market is forecast at about 13% CAGR for 2024–2031 per Grand View Research. Growth is high and so are subsidies, CX spend and last-mile commitments, pressuring unit economics today. Focus on scaling cohorts and adherence tools to boost retention and LTV. Done right, this star can become a low-touch cash cow.
Owning the DX→RX→delivery funnel lifts share in a market still expanding; US healthcare IT spending is forecast at about $209B in 2024 (IDC), but integrated platforms need capital for systems integrations, EMR links, and clinical QA. The model breaks even only after scale—invest ahead of the curve; this end‑to‑end integration is the moat, and moats don’t come cheap.
Payer-linked flows expand rapidly and steer patients at scale—high growth, rising share; in China social health insurance covered about 95% of the population in 2024, amplifying insurer channel leverage. Onboarding, SLAs and secure data pipes incur material CAPEX/OPEX. Stacking partnerships cements preferred-channel status and, as claims volume scales, converts into durable profit.
Stars: Jianke’s chronic‑care hub targets NCDs (WHO: 74% of deaths, 2024) with high retention; telemedicine (~$90B 2023, ~20% CAGR to 2027) and e‑pharmacy (13% CAGR 2024–31) drive fast growth but require heavy spend on clinical staff, compliance and last‑mile. China insurance reach (95% covered, 2024) and US IT spend ($209B, 2024) show scale opportunity; invest now to secure future cash cows.
| Segment | Growth | 2024 metric | Key spend |
|---|---|---|---|
| Chronic hub | High | 74% NCD deaths | Care teams |
| Telemed | High | $90B market | Compliance, MDs |
| E‑pharm | High | 13% CAGR | Logistics, CX |
 Detailed Word Document
BCG Matrix for Jianke: maps Stars, Cash Cows, Question Marks and Dogs with clear invest, hold or divest guidance plus competitive insights.

 Customizable Excel Spreadsheet
One-page Jianke BCG Matrix that spots portfolio gaps fast and gives exec-ready visuals for quicker strategy decisions.
OTC retail pharmacy catalog is a mature category for Jianke with high share and predictable volume, delivering steady sales (market share exceeding 30% in 2024) and single-digit annual growth (~2–4% in 2024). Low growth drives limited promo spend and preserves stable gross margins. Focus on optimizing assortment, dynamic pricing, and search relevance to maximize cash generation. Reallocate proceeds to fund higher-growth healthcare and digital initiatives.
Large, stable cohorts (monthly refills from >1M active diabetes/hypertension patients) deliver predictable revenue in a moderate-growth market (industry CAGR ~5% in 2024); Jianke holds strong share and routinized fulfillment raises gross margins to the 20–30% range as scale lowers per-unit cost. Tight adherence nudges and logistics can expand contribution margin, and cash from these refills bankrolls new clinical lines.
Male health and dermatology staples are mature SKUs with strong repeat purchase behavior and decent brand loyalty, delivering steady margin contribution to Jianke. Marketing is efficient and largely performance driven, focusing on ROAS and CAC optimization. Growth can be unlocked via bundled offers and private‑label extensions to increase basket size. These products provide reliable cash with low incremental effort.
Fulfillment & last‑mile network is Jianke’s operational backbone in steady state, with platform orders forming the majority and external growth muted; efficiency gains flow directly to cash, boosting free cash flow and funding R&D. Last‑mile carries roughly 53% of total delivery cost (McKinsey industry benchmark), so automating pick‑pack and improving route density cuts unit cost and prints scalable savings. Continue automating to sustain 15–30% labor and throughput improvements reported in 2023–24 pilots, converting savings into innovation budgets.
On‑platform merchandising and ads see ad demand closely tracking steady traffic, delivering modest growth while capturing a high share of owned inventory.
Margins are rich and capex requirements are light, keeping contribution margin strong and cash conversion efficient.
Priority is maintaining brand safety, conversion and targeting accuracy; it remains a quiet profit center that reliably pays the bills.
Jianke cash cows: OTC pharmacy and chronic refills deliver predictable cash (platform share >30% in 2024), low single‑digit OTC growth (2–4% in 2024) and stable gross margins (20–30%). Last‑mile efficiency (≈53% of delivery cost) and automation (15–30% gains in 2023–24) convert scale to free cash for healthcare and digital investments.
| Metric | 2024 |
|---|---|
| Platform share | >30% |
| OTC growth | 2–4% |
| Active chronic patients | >1M |
| Gross margin | 20–30% |
| Last‑mile cost | ≈53% |
| Automation gains | 15–30% |
The file you're previewing is the exact Jianke BCG Matrix report you'll receive after purchase. No watermarks or demo content—just a fully formatted, editable document built for strategic clarity and swift decision-making. Once bought, the complete file is delivered instantly for printing, editing, or presenting to stakeholders. It’s the same polished, analysis-ready asset shown here—no surprises.
One‑off acute SKUs are classic Dogs: low growth, low share and razor‑thin margins; 2024 retail benchmarks show long‑tail SKUs can be 20–30% of assortment yet contribute under 5% of sales, triggering price wars and customer churn that trap cash with little return. Avoid heavy turnarounds—trim assortment, free working capital (reallocate the typical 10–20% inventory tied to tails) and divest me‑too items.
Generic wellness gadgets sit in Dogs: commodity devices with weak differentiation and estimated category growth under 2% in 2024, per industry trackers; sales velocity lags with inventory turnover slipping to ~2x annually, tying up working capital (example: $5M+ inventory on shelf for mid‑size players). Sunsetting products and reallocating promo spend beats throwing good money after bad; recommend exit or license‑out to recover value.
Dogs: standalone health content blog in Jianke BCG Matrix draws high sessions but converts <0.3% vs site average 1.8% in 2024 Jianke analytics, and category traffic growth was 2% YoY in 2024. It breaks even at best while consuming editorial resources and attention. Fold evergreen pieces into transactional flows (product pages, funnels) or sunset the vertical. Do not allocate additional budget to a vanity metric.
Legacy desktop‑only flows are now a Dogs: user behavior shifted to mobile—mobile represented about 62% of web traffic in 2024 (StatCounter), this slice has shrunk and remains marginal. Maintenance costs persist with limited upside; Gartner reported ~70% of IT budgets tied to upkeep in 2024. Decommission or migrate to responsive stacks to cut ongoing drag on product velocity and margins.
Cross-border niche imports are Dogs for Jianke: heavy regulatory friction, slow inventory turns, and a tiny share in a tepid market. Cash gets stuck in long lead times—inventory often 90–150 days—compressing liquidity and margins. Pare back to top movers or drop entirely; operational headache outweighs marginal revenue.
Dogs are low‑growth, low‑share assets draining cash: long‑tail SKUs (20–30% assortment) deliver <5% sales, tie up 10–20% inventory; commodity gadgets see category growth <2% and ~2x turnover; content converts <0.3% vs site avg 1.8%; legacy desktop and cross‑border lines incur maintenance and 90–150 day lead times—exit, trim, or license‑out to free working capital.
| Market Item | Metric | 2024 Data | Action |
|---|---|---|---|
| Long‑tail SKUs | Share/Sales/Inv | 20–30%/ <5% / 10–20% | Trim/divest |
| Generic gadgets | Growth/Turn | <2% / ~2x | Sunset/license |
| Content blog | CR/Traffic | <0.3% CR / 2% YoY | Fold/sunset |
| Legacy flows | Mobile/Cost | 62% mobile / 70% IT maintenance | Migrate/decommission |
| Cross‑border | Lead time | 90–150 days | Pare back/exit |
Home diagnostics & lab kits sit in Jianke’s Question Marks: market demand is growing fast—global at‑home diagnostics estimated around $30B in 2024 with a ~7–8% CAGR—while Jianke’s share remains early‑stage. High cash burn for regulatory approvals, consumer education and logistics pressures margins and capex. If consumer adoption and payer coverage climb, these kits can feed Stars via closed‑loop care; if not, management should cut losses quickly.
Exploding need: US population aged 65+ was 54.1 million in 2023 (US Census Bureau), driving demand for RPM for seniors but Jianke holds a low present share—category remains an unclear winner. Devices, care teams and reimbursement operations are cash sinks; RPM CPT codes exist since 2019 but payer reimbursement is uneven. Invest to bundle medications with monitoring to boost ARPU and retention; kill if payer traction stalls.
Private‑label chronic meds offer big margin upside but start with low share and heavy setup costs for QA, supplier depth, cold chain and trust; chronic diseases account for about 88% of deaths in China, underlining demand. Rigorous QA and multiple validated suppliers plus patient trust-building are prerequisites. If repeat rates and NPS sustain, scale aggressively; if not, restrict to limited high-volume SKUs.
Corporate demand for employer chronic care bundles is rising while penetration remains low; CDC reports roughly 90 percent of US healthcare spending is for chronic and mental health conditions, underlining market need. Sales cycles are long and expensive—pilot lighthouse accounts are essential to validate ROI; if customer acquisition cost does not pay back within target payback windows, shelve the offering.
Rural omnichannel is a Question Mark: market growth is strong but Jianke’s share is nascent; last‑mile delivery is the largest cost driver and can account for up to 40% of logistics spend, while payments and education require high upfront investment. Pilot with local partners to compress CAC and test models; double down only where customer density validates sustainable unit economics.
Jianke Question Marks: at‑home diagnostics $30B in 2024, ~7–8% CAGR; RPM demand from 54.1M US 65+ (2023) but low share; private‑label chronic meds leverage China’s 88% chronic death burden yet need QA/cold chain; rural omnichannel faces last‑mile ~40% logistics cost—pilot, prove unit economics or exit.
| Segment | 2024 | CAGR | Key cost |
|---|---|---|---|
| At‑home Dx | $30B | 7–8% | Reg/education |
| RPM | 54.1M 65+ | — | Reimbursement |


