
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
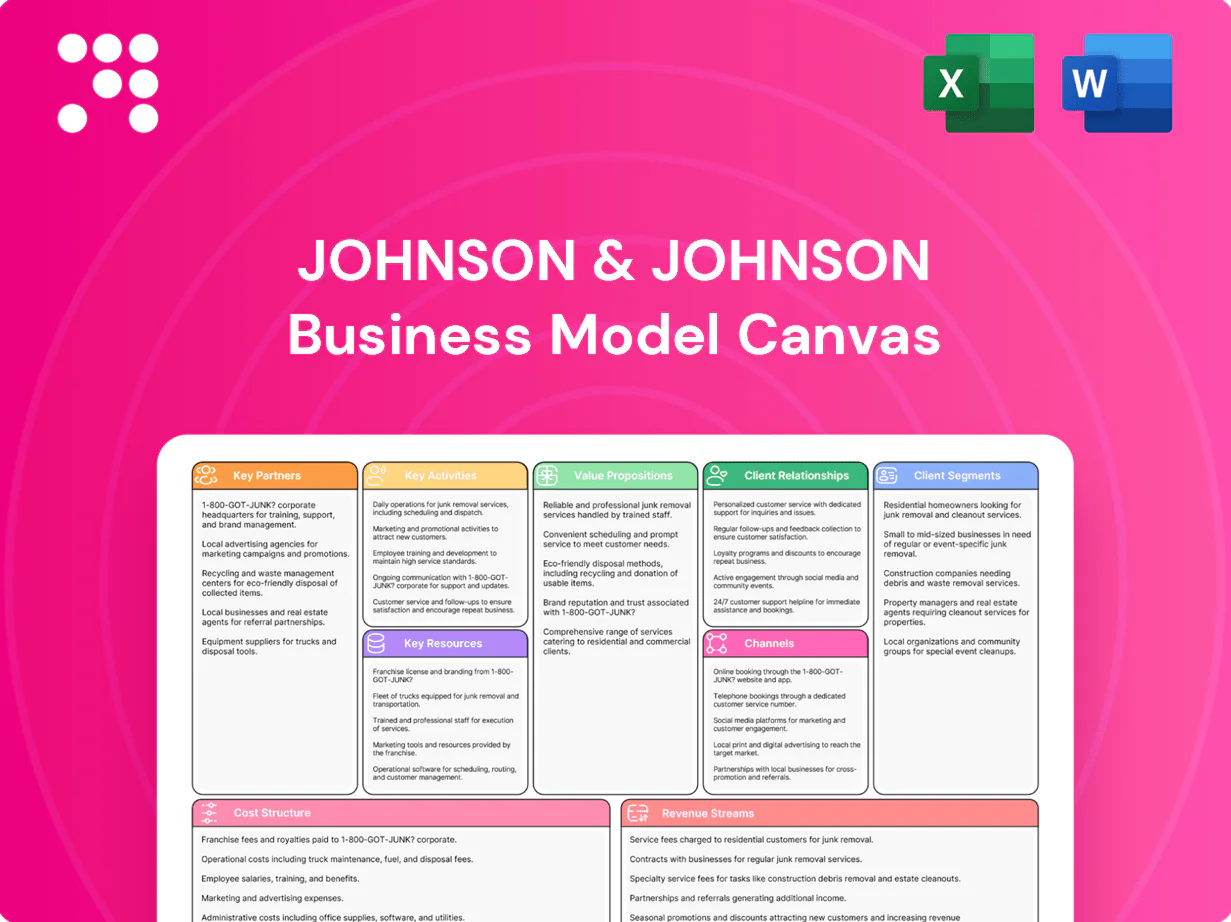
Unlock Johnson & Johnson’s strategic blueprint with a concise Business Model Canvas that maps its value propositions, key partners, and revenue engines across pharmaceuticals, medtech, and consumer health. Ideal for investors, consultants, and founders seeking actionable, company-specific insights—download the full Word/Excel canvas to benchmark and apply proven growth levers.
Collaborations with universities and biotech firms accelerate discovery and de-risk early science, with J&J leveraging co-development and option-to-license deals alongside incubators such as JLABS (launched 2012) that have supported over 1,000 startups globally. These alliances expand the pipeline—across oncology, immunology, neuroscience and cardiovascular—by adding novel modalities and platform technologies. J&J sustains multi-billion-dollar annual R&D investment to co-fund and scale external innovation.
Johnson & Johnson MedTech relies on surgical KOLs and integrated delivery networks for co-design, training and evidence generation, with >200 hospital partnerships supporting device iterations and surgeon proctoring. Clinical networks enable multi-center trials (dozens–100+ sites) and real-world data capture to drive regulatory and reimbursement claims. ERAS adoption and procedure standardization cut LOS by ~2 days and complications by 30–50%, accelerating device uptake.
Early scientific advice from FDA (PDUFA target 10 months, 6 months for priority review) and EMA (centralised review target 210 days) helps J&J align trial design with regulatory expectations. Engagements with HTA bodies like NICE (QALY thresholds ~£20,000–30,000) and payer partners shape value dossiers and economic models. These partnerships accelerate approvals, optimize market access and coordinate post‑market commitments for label expansion and safety monitoring.
Complex biologics and advanced devices demand resilient supply chains and specialized inputs; Johnson & Johnson leverages API suppliers, contract manufacturers and precision component makers across its global network, operating in more than 60 countries (2024). Dual-sourcing, binding quality agreements and GMP audits reduce disruption risk, while strategic CDMO capacity is scaled during launches and commercial scale-ups to meet demand.
Pharmaceuticals flow through specialty distributors and pharmacies to hospitals and clinics, with specialty drugs accounting for about 50% of US drug spend in 2023 (IQVIA); J&J leverages these channels for access and patient support. MedTech benefits from GPO contracts that cover roughly 70% of US hospital purchasing and regional distributors for last-mile delivery, streamlining tendering, inventory and cold-chain logistics to broaden reach across mature and emerging markets.
J&J partners with universities, biotech and JLABS (>1,000 startups) to de-risk early science and expand pipelines, backed by multi-billion-dollar annual R&D. MedTech co-design with >200 hospital partners and surgical KOLs accelerates adoption. Global supply/CDMO and distributors span 60+ countries (2024); specialty drugs ~50% US drug spend (2023); GPOs ~70% hospital coverage.
| Partner | Role | Metric |
|---|---|---|
| JLABS/startups | Early innovation | >1,000 startups |
| Hospitals/KOLs | Co-design/trials | >200 partners |
| Supply/CDMO | Manufacture/scale | 60+ countries (2024) |
| Channels | Access | Specialty drugs 50% (2023); GPOs ~70% |
 Detailed Word Document
A comprehensive Business Model Canvas for Johnson & Johnson mapping customer segments, channels, value propositions, key resources, partners, activities, cost structure and revenue streams with strategic insights. Designed for presentations and investor discussions, it links competitive advantages and SWOT analysis to each BMC block for actionable decision-making.

 Customizable Excel Spreadsheet
High-level view of Johnson & Johnson’s business model with editable cells to condense its complex healthcare, pharmaceutical, and consumer segments into a single-page strategic snapshot, saving hours of formatting and simplifying boardroom or team discussions.
Rigorous translational research feeds a diversified pipeline leveraged by J&J’s 138-year legacy (founded 1886); global Phase I–III trials run across 60+ countries with embedded biomarker strategies. Adaptive designs and decentralized elements accelerate enrollment and real-world insights. Evidence packages are assembled to satisfy regulators, payers and clinicians.
End-to-end QA/QC ensures safety across Johnson & Johnson medicines and devices, with integrated testing and batch release protocols. In 2024 regulatory teams managed submissions, inspections, and continuous vigilance reporting to regulators. ISO and GMP standards anchor manufacturing and post-market surveillance, and robust compliance programs lower recall and legal risk.
Advanced manufacturing at Johnson & Johnson leverages bioreactors, aseptic fill-finish, and additive manufacturing across 250+ global manufacturing sites to support complex biologics and device portfolios in 175+ countries. Network planning optimizes cost, resilience and service levels through regional capacity balancing. Digital twins and serialization improve traceability and yield. Continuous improvement programs reduce COGS while preserving quality.
Value dossiers and cost-effectiveness models underpin reimbursement decisions, with health technology assessment used in over 50 countries in 2024; outcomes-based agreements and risk-sharing contracts align incentives and are increasingly used to secure access. Tender bid management optimizes volume and margin in centralized markets, where price erosion can exceed 20% on single-source tenders. Real-world evidence supports renewals and line extensions by demonstrating effectiveness and safety post-launch.
Surgeon proctoring, simulation labs and in-the-OR support enable safe adoption of J&J technologies by reinforcing skills and reducing procedural variability; field service teams sustain device uptime and instrument readiness through preventive maintenance and rapid repairs. Patient support programs improve adherence and access, while closed-loop feedback from clinicians and patients informs product iterations and targeted training content.
Translational R&D fuels a diversified pipeline; global Phase I–III trials ran in 60+ countries (2024) with biomarker-led adaptive designs.
QA/QC and GMP across 250+ manufacturing sites ensure supply to 175+ countries; 2024 regulatory teams managed submissions and inspections.
HTA dossiers used in 50+ countries (2024); outcomes-based deals and tenders (up to >20% price erosion) drive access strategies.
| Activity | 2024 metric |
|---|---|
| Trials | 60+ countries |
| Manufacturing sites | 250+ |
| Countries served | 175+ |
| HTA use | 50+ countries |
The document you're previewing is the actual Johnson & Johnson Business Model Canvas you'll receive—it's not a mockup. Upon purchase you'll get this exact, fully editable file with all sections intact, formatted for presentation and analysis. No placeholders, no surprises—what you see is what you own.
Patents, trade secrets and regulatory exclusivities underpin Johnson & Johnsons innovation moat, supported by a global portfolio spanning thousands of patent families and branded-drug exclusivities. Large randomized trials and registries — comprising hundreds of trials and millions of patient records — provide robust efficacy and safety evidence. These data assets enable label expansions, strengthen payer negotiations, and feed AI-driven discovery and post-market analytics.
Johnson & Johnson leverages expert teams across biology, engineering, biostatistics and regulatory science, supported by a global KOL network of thousands that shaped pivotal trial design and adoption in 2024; the company’s R&D investment was about $13B in 2024. High talent density accelerates problem‑solving in complex modalities, while cross‑functional squads shortened lab‑to‑launch cycle times on key programs by double‑digit percentages.
Sites for biologics, small molecules and devices across more than 60 countries provide scale and flexibility; validated processes and a global QMS support regulatory compliance worldwide. Redundancy and tech‑transfer capabilities reduce disruption risk, while ongoing automation investments—backed by a global workforce of ~132,000—improve consistency and lower unit costs.
Decades of clinical presence—Johnson & Johnson, founded 1886 (over 135 years)—underpin credibility with clinicians and payers. Strong product brands Ethicon, DePuy Synthes and Vision Care drive preference in surgery, orthopedics and vision. Trust reduces adoption friction, supports premium positioning and influences tenders and formulary decisions.
Patents, trade secrets and regulatory exclusivities (thousands of patent families) underpin J&J’s innovation moat; R&D spend was about $13B in 2024. Global data assets from hundreds of trials and millions of patient records enable label expansions and AI analytics. A ~132,000 workforce, 60+ regional distribution centers and sales in 175+ countries support scale and market access.
| Metric | 2024 |
|---|---|
| R&D spend | $13B |
| Workforce | ~132,000 |
| Countries | 175+ |
| Distribution centers | 60+ |
Innovative Medicines targets oncology, immunology and neuroscience with novel mechanisms, biomarker-driven programs and optimized dosing to deliver clinically meaningful outcomes. In 2024 J&J reported over 200 clinical-stage programs, prioritizing therapies designed to cut hospitalizations and overall disease burden. Durable responses have driven payer interest through lower long-term costs and measurable quality-of-life gains.
Devices and instruments enhance surgical precision and workflow, with advanced tools enabling tissue-sparing techniques that have been shown to reduce operative variance and improve outcomes. Integrated systems reduce OR time by up to 20% and can lower complication rates by as much as 30%, shortening length of stay. Reusable/consumable ecosystems improve economics for providers through lifecycle cost reductions. Data-enabled insights drive continuous performance improvement via real-world analytics.
Rigorous quality systems and regulatory compliance at Johnson & Johnson have historically reduced adverse events and recalls, supporting its role as a global medtech leader with products sold in over 175 countries. Consistent clinical performance builds clinician confidence, reinforced by the company’s scale—2023 revenue of about 81.3 billion dollars evidences market trust. Global manufacturing footprint ensures supply continuity, while robust post-market surveillance and support sustain lifecycle value.
End-to-end support accelerates safe adoption through comprehensive surgeon education, improves access and adherence (WHO estimates ~50% adherence to long-term therapies in high-income countries), and boosts outcomes via patient services; field service maximizes device uptime and asset utilization while custom protocols align care pathways to value-based targets.
Johnson & Johnson leverages a portfolio spanning pharmaceuticals, medical devices and consumer health to meet diverse clinical needs across geographies, with products sold in 175+ countries (2024). Localized evidence generation and tender approaches adapt to system constraints while pricing and access models are tailored to payer expectations. Strong emerging market presence in 2024 expanded patient reach and uptake.
J&J delivers clinically meaningful therapies via 200+ clinical-stage programs (2024), focusing on oncology, immunology and neuroscience to reduce hospitalizations and long-term costs. Devices cut OR time up to 20% and complications up to 30%, while portfolio reach spans 175+ countries (2024) with localized access models. Comprehensive education, field service and patient support lift adherence from ~50% baseline and maximize device uptime.
| Metric | Value (2024) |
|---|---|
| Clinical-stage programs | 200+ |
| Countries sold | 175+ |
| OR time reduction | up to 20% |
| Complication reduction | up to 30% |
| Baseline adherence | ~50% |
Dedicated key-account teams manage IDNs, hospital systems and ASCs, coordinating multi-year (typically 3–5 year) contracts, onsite training and agreed service-levels. They oversee implementation, warranty and sterile logistics while aligning pricing and formulary access. Data-sharing agreements enable joint KPI tracking (utilization, outcomes, supply-costs) to drive clinical and operational improvement. Long-term partnerships focus on retention and expanding share-of-wallet through bundled solutions and renewal cadence.
In 2024 Johnson & Johnson’s non-promotional medical affairs teams engaged clinicians on science and data, separating educational dialogue from commercial activities to ensure compliance and trust.
Advisory boards and congress activities collected clinician feedback across therapeutic areas, informing pipeline prioritization and post-market strategy.
Peer-reviewed publications and real-world evidence generation sustained confidence post-approval by demonstrating effectiveness and safety in routine practice.
Targeted educational grants funded guideline-aligned continuing medical education and implementation projects to improve uptake of evidence-based care.
Johnson & Johnson hub services streamline enrollment, co-pay assistance and patient navigation to remove financial and logistical barriers to therapy access. Adherence tools and nurse hotlines boost treatment persistence and support clinical decision-making. Outcomes tracking feeds real-world data to care teams and payers to demonstrate value and guide interventions. Programs are structured for regulatory compliance and transparency, with public reporting and audit-ready processes.
On-site engineers and reps ensure proper setup and maintenance, minimizing setup errors and ensuring device compliance; rapid-response teams reduce downtime and surgical delays through prioritized service coordination. Preventive programs optimize instrument lifecycles via scheduled maintenance and parts replacement, while remote monitoring enables proactive issue resolution and fewer emergency visits.
Digital provider portals streamline ordering, tracking and training access, while CRM-driven insights personalize interaction cadence and enable targeted outreach. Self-service portals reduce friction for routine needs and free reps for complex sales. Analytics inform account planning and cross-sell opportunities across J&J's portfolio.
Dedicated key-account teams manage IDNs, hospital systems and ASCs with multi-year (typically 3–5 year) contracts, onsite training, warranty and sterile logistics to retain and expand share-of-wallet. In 2024 Johnson & Johnson separated non-promotional medical affairs engagement from commercial activities to maintain compliance and clinician trust. Hub services, on-site engineers and digital portals streamline access, adherence and uptime, feeding real-world outcomes to payers and care teams.
| Metric | Fact |
|---|---|
| Contract length | Typically 3–5 years |
| 2024 policy | Medical affairs non-promotional engagement |
| Service channels | Hub services, on-site engineers, digital portals |
Specialized salesforces engage surgeons, procurement teams and value committees in over 1,000 U.S. IDNs as of 2024, using demonstrations and perioperative trials to drive conversion; contracting is structured around procedural volumes and agreed outcomes metrics, and dedicated post-sale service teams (clinical reps, education, technical support) cement long-term relationships and adoption.
GPOs aggregate provider demand to secure lower prices and product standardization, with over 80% of US hospitals participating in GPOs in 2024. National and regional tenders frequently award multi-million-dollar, high-volume contracts that shape market share. Compliance with technical specs and service KPIs is mandatory for award and retention. Competitive differentiation relies on robust value evidence and lower total lifecycle cost.
Specialty distributors and licensed wholesalers deliver Johnson & Johnson pharma products to hospitals, clinics and oncology centers under strict cold-chain controls. Specialty pharmacies manage complex therapies and adherence, with specialty medicines accounting for about 50% of US drug spend. Cold-chain integrity and over 70 FDA REMS programs as of 2024 are maintained. Real-time data feeds enable inventory and outcomes visibility across the channel.
Digital platforms integrate with hospital ERP and e-catalogs to simplify ordering, while online education and virtual demos expand reach to clinicians and procurement teams; analytics from digital interactions feed demand planning and reduced stockouts. Secure portals manage documentation and service tickets, supporting compliance and faster resolution. Johnson & Johnson reported approximately 55.3 billion USD in sales in 2024, fueling digital investments.
In-country J&J teams navigate regulation, pricing and reimbursement across more than 175 countries, tailoring submissions and market access strategies to local frameworks.
Local distributors extend coverage into thousands of smaller providers and clinics, while regional service hubs deliver training, maintenance and repairs to support product uptime.
Partnerships adapt the channel mix by market maturity, shifting from distributor-led models in emerging markets to direct clinical and hospital partnerships in developed markets.
Omnichannel mix: direct surgical sales in 1,000+ US IDNs (perioperative trials), GPO/tender dominance (80%+ US hospitals), specialty distributors/pharmacies for cold-chain and REMS-covered therapies, and digital ERP/e-catalog integrations driving ordering and analytics; J&J reported 55.3 billion USD sales in 2024 enabling channel investments.
| Metric | 2024 | Note |
|---|---|---|
| US IDNs | 1,000+ | Direct sales focus |
| Hospitals in GPOs | 80%+ | Price/standardization |
| REMS programs | 70+ | Compliance |
| J&J sales | $55.3B | Channel investment |
Hospitals and IDNs are the primary buyers of Johnson & Johnson surgical systems, instruments and implants, comprising more than 6,000 US hospitals and large global IDNs. Value committees evaluate clinical outcomes and total cost of ownership, increasingly requiring real-world evidence and cost-effectiveness data. Multi-year contracts (typically 3–5 years) prioritize reliability, service SLAs and >99% uptime. Standardization initiatives favor comprehensive portfolios that simplify procurement and reduce TCO.
Surgeons and procedural specialists across orthopedic, general, interventional, and ophthalmic fields drive device selection; in 2024 surgeon preference remained the primary determinant in >50% of hospital purchasing decisions. Training, ergonomics, and clinical outcomes are top purchase drivers, with simulation programs improving uptake by an estimated 20%. KOLs accelerate peer adoption and protocol updates, and frontline feedback directly shapes product roadmaps and iterative releases.
Coverage and pricing decisions determine access and volumes for Johnson & Johnson, with public payers financing roughly 60% of global health spending (WHO). HTA outcomes and budget impact analyses drive reimbursement decisions across OECD and emerging markets. Risk-sharing and outcomes contracts align incentives between payers and J&J, while tender mechanisms dominate procurement in many regions.
Patients with high-burden conditions directly experience clinical benefits and risks from J&J therapies; access support and education improve adherence and outcomes. WHO reports medication nonadherence averages about 50% in chronic diseases, making support programs critical. Patient-reported outcomes increasingly inform value narratives and payer negotiations, while advocacy groups shape awareness and policy.
Hospitals/IDNs (>6,000 US hospitals) and surgeons (surgeon preference >50% in 2024) drive surgical device revenue via 3–5 year contracts prioritizing >99% uptime and TCO; payers (public ~60% of spending) and HTA shape access; hospital pharmacies/specialty clinics manage complex biologics and real-world reporting; patients (WHO nonadherence ~50%) and advocacy influence uptake.
| Segment | 2024 metric | Impact |
|---|---|---|
| Hospitals/IDNs | >6,000 US; 3–5yr contracts | Service SLAs, standardization |
| Surgeons | >50% purchase influence | Training/KOLs drive adoption |
| Payers | Public ~60% spend | Reimbursement, HTA |
| Patients | Nonadherence ~50% | Support programs critical |
Johnson & Johnson incurred approximately $12.0 billion in R&D in 2024, reflecting significant investment across discovery, clinical trials, and post‑market studies. Complex biologics and device trials drive unit costs higher, while global site management and data operations add substantial overhead. Portfolio management focuses capital on high‑probability assets to optimize ROI and pipeline throughput.
COGS for Johnson & Johnson encompass raw materials, direct labor, and stringent quality controls; in 2024 COGS ran at roughly 30% of net sales, reflecting high material and QA intensity. Redundancy and cold-chain logistics—critical for biologics and vaccines—add substantial freight and storage premiums. Ongoing equipment validation and maintenance drive recurring OPEX. Continuous yield improvements and scale economies progressively lower unit costs over time.
Salesforces, training programs and congress presence drive material SG&A spend at Johnson & Johnson, with pharma commercial and medical affairs historically accounting for a high-single-digit to low-double-digit percent of revenue; 2023 company revenue was about 63.8 billion USD, scaling these costs. Ongoing medical education and evidence dissemination add incremental spend, while CRM, digital tools and content production expand reach. KAM structures raise fixed costs but deepen market penetration.
Regulatory submission fees, continuous audits and pharmacovigilance are ongoing cost drivers for Johnson & Johnson, requiring sustained investment in safety monitoring and compliance to avoid fines and market disruption; post-market surveillance demands dedicated teams and integrated IT systems. Intellectual property protection and litigation reserves represent material balance-sheet items given global product exposure, with operations across 175+ markets increasing regulatory complexity.
External innovation deals combine upfronts and contingent milestones, with J&J continuing to deploy large upfronts and mid-to-high double-digit milestone structures in 2024 to accelerate pipelines.
Royalties on partnered products compress margin profiles over the product life, particularly in biologics and pharma franchises where royalty rates often run in the mid-teens percent range, affecting long-term gross margin.
Co-development cost shares shift near-term cash flow timing toward partners; J&J’s 2024 R&D outlay (~US$12B) reflects both internal spend and expensed collaboration costs.
Active portfolio mix management balances owned high-margin assets vs partnered programs to optimize cash generation and risk-return across launch waves.
Johnson & Johnson cost structure centers on R&D (~US$12.0B in 2024), COGS (~30% of net sales in 2024) and sizeable SG&A (high-single to low-double-digit % of revenue). Regulatory, PV, IP/litigation and cold‑chain logistics are material fixed and semi‑fixed drivers across 175+ markets. Partner upfronts/milestones and royalties compress near‑term cash and long‑term margins.
| Metric | 2024 |
|---|---|
| R&D | US$12.0B |
| COGS | ~30% rev |
| Markets | 175+ |
Revenue from innovative medicines in 2024 is concentrated in immunology, oncology, neuroscience and cardiovascular therapies, with specialty pricing reflecting clinical differentiation and outcome-based value. Growth is propelled by label expansions and geographic rollout of new indications. Lifecycle strategies—line extensions, reformulations and targeted patent settlements—manage near-term patent cliffs. Commercial focus remains on high-margin specialty segments.
MedTech sales span orthopedics, surgical, interventional and vision portfolios, contributing approximately $18 billion in 2024 to Johnson & Johnson’s revenue. Capital equipment sales are complemented by high-margin disposables and procedure kits that scale with procedure volume and mix. Procedure volumes—joint replacements, cataracts and interventional cases—directly drive consumable demand. Service contracts and software/hardware upgrades add recurring annuity revenue, ~10–15% of segment sales.
Consumables and service contracts deliver steady recurring revenue for Johnson & Johnson, driven by sterile supplies, lenses and instrument sets supplied to hospitals and ASC networks. Preventive maintenance and technical support are typically bundled with sales, while extended warranties and uptime SLAs command premium pricing. High retention rates stabilize cash flows, and in 2024 these service-led streams remained core to MedTech recurring income.
Tenders and institutional contracts deliver stable, multi-year revenue for Johnson & Johnson, with hospitals, GPOs and public health systems committing volumes in exchange for price and service guarantees; J&J reported approximately $63.5 billion in pharmaceutical and medical device sales in 2024, underpinning institutional penetration.
Volume commitments typically yield price concessions and fixed-service SLAs; performance bonuses tied to outcomes are used in value-based procurement, increasing contract lift and renewal rates.
J&J’s broad portfolio across devices, pharma and consumer health raises win probability in bundled tenders and integrated care deals.
Licensing and collaboration income for Johnson & Johnson includes upfronts, milestone payments, and royalties from partnered programs; out-licensing non-core R&D monetizes assets while platform technology access generates multi-asset revenue streams and co-promotion agreements add incremental promotional revenue.
Revenue in 2024 centered on specialty pharma (immunology, oncology, neuroscience, CV) and MedTech consumables, with lifecycle management and value-based contracts driving pricing and renewals. MedTech sales ~18 billion, service/software annuity ~10–15% of segment sales; J&J reported ~63.5 billion in pharma and device sales in 2024. Licensing and collaborations add upfronts, milestones and royalties, supporting pipeline monetization.
| Stream | 2024 | Notes |
|---|---|---|
| Pharma & Device | $63.5B | Corporate total |
| MedTech | $18B | Consumables + devices |
| Services/Software | 10–15% | of MedTech sales |
| Licensing | — | upfronts/milestones/royalties |


