
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
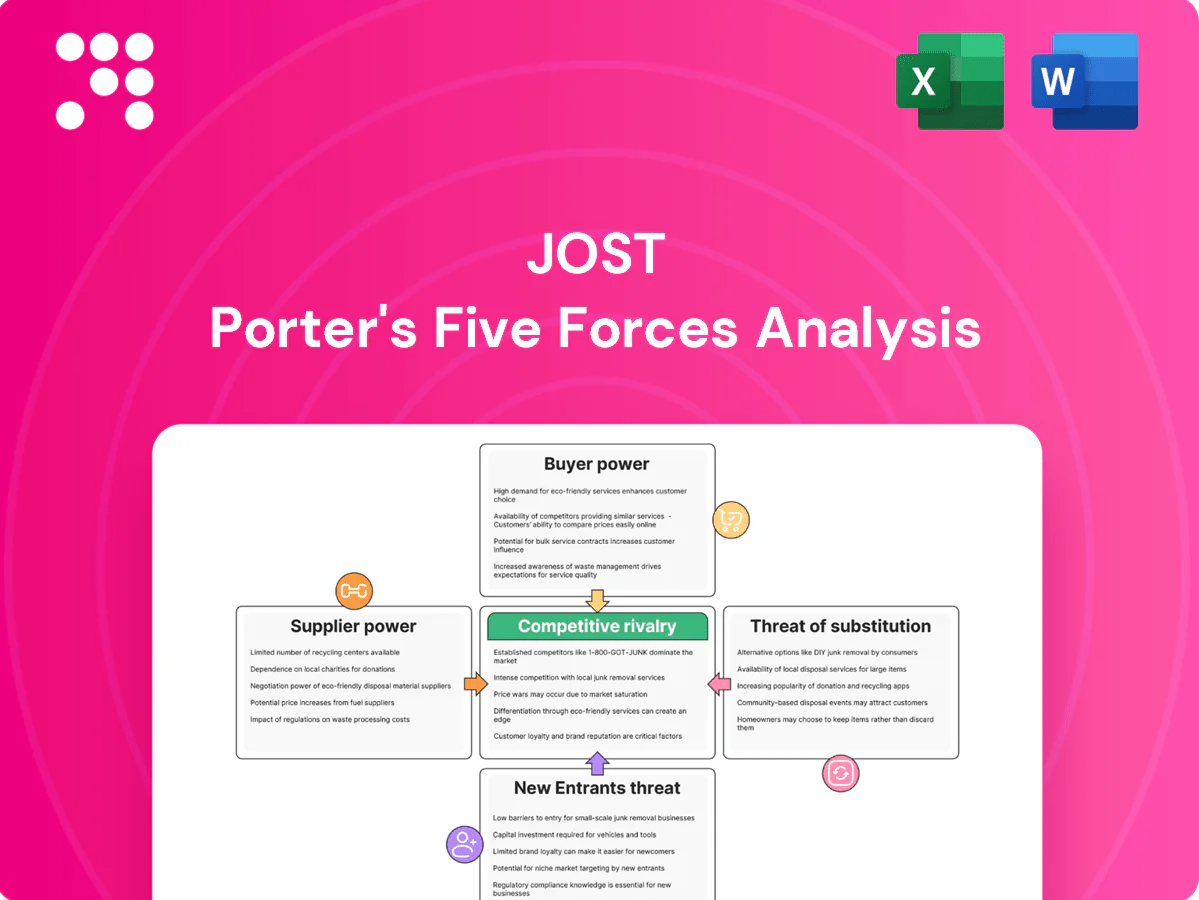
JOST's competitive landscape is shaped by five key forces: the bargaining power of buyers and suppliers, the threat of new entrants and substitutes, and the intensity of rivalry among existing competitors. Understanding these dynamics is crucial for strategic decision-making.
The complete report reveals the real forces shaping JOST’s industry—from supplier influence to threat of new entrants. Gain actionable insights to drive smarter decision-making.
JOST's reliance on specialized suppliers for safety-critical components, such as advanced braking systems or high-strength steel for fifth wheels, can significantly concentrate bargaining power. When only a handful of manufacturers possess the unique engineering capabilities or proprietary processes for these essential parts, their leverage over JOST naturally escalates. This is especially evident for components requiring highly technical materials or specialized, patented manufacturing techniques, limiting JOST's ability to easily switch suppliers.
Switching costs for JOST are a significant factor influencing supplier bargaining power. These costs include the expense of retooling manufacturing equipment, the time and resources required for re-certification of new components, and the potential for production line disruptions during the transition. For instance, JOST's commitment to stringent quality and safety standards means new suppliers must undergo extensive validation, often taking months and substantial investment.
Suppliers who provide highly unique or patented technologies for crucial vehicle systems, like advanced braking or powertrain components, naturally hold more sway. When JOST's product line relies on these specialized inputs, the suppliers can dictate higher prices or impose less favorable contract terms. For instance, a supplier holding a patent for a specific lightweight alloy used in JOST's heavy-duty truck components could leverage this exclusivity.
The threat of suppliers integrating forward and producing finished goods similar to JOST's offerings significantly bolsters their bargaining power. If a supplier can credibly threaten to manufacture components that directly compete with JOST's own products, it creates leverage in price negotiations and supply terms.
While JOST operates in a market with high capital intensity and specialized expertise, which generally acts as a deterrent to forward integration, the possibility remains for suppliers of crucial, albeit less complex, sub-components. Such a supplier could potentially broaden its manufacturing scope, thereby encroaching on JOST's market space and exerting considerable pressure.
The quality and cost of inputs from suppliers are crucial for JOST's product competitiveness. Given that JOST's systems are safety-critical, the reliability of components sourced from suppliers is paramount.
Any lapse in input quality can result in product malfunctions, costly recalls, and significant reputational harm. This underscores the substantial bargaining power held by suppliers who consistently deliver high-quality, dependable components.
JOST's bargaining power with suppliers is influenced by the concentration of suppliers for critical components. For instance, if only a few specialized manufacturers can produce advanced braking systems, they hold significant leverage. This concentration was evident in 2024, where the lead time for certain high-performance steel alloys, essential for JOST's fifth wheels, extended due to limited global production capacity, increasing supplier pricing power.
High switching costs also empower suppliers. JOST faces substantial expenses and delays in retooling, component re-certification, and potential production halts when changing suppliers. For example, adopting a new supplier for a safety-certified electronic control unit in 2024 required an estimated $1.5 million in retooling and over six months for regulatory approval, reinforcing supplier leverage.
Suppliers offering unique or patented technologies, like those for advanced hydraulic systems used in JOST's trailer couplings, command greater influence. A supplier holding exclusive rights to a crucial, high-efficiency hydraulic pump in 2024 could dictate terms, as alternatives were either unavailable or technically inferior, impacting JOST's product innovation and cost structure.
| Factor | Impact on JOST | 2024 Data/Example |
|---|---|---|
| Supplier Concentration | Increases supplier leverage | Limited suppliers for advanced braking systems; extended lead times for specialized steel alloys. |
| Switching Costs | Empowers existing suppliers | Estimated $1.5M retooling and 6+ months for ECU supplier change in 2024. |
| Uniqueness of Inputs | Grants suppliers pricing power | Exclusive rights to high-efficiency hydraulic pumps for trailer couplings in 2024. |
 Detailed Word Document
JOST's Porter's Five Forces analysis dissects the competitive intensity within its operating environment, examining the threat of new entrants, the bargaining power of buyers and suppliers, the threat of substitutes, and the rivalry among existing competitors.

 Customizable Excel Spreadsheet
Quickly identify and mitigate competitive threats by visualizing the intensity of each of Porter's Five Forces.
JOST's customer base includes both original equipment manufacturers (OEMs) and aftermarket clients, with large OEMs being particularly significant due to their substantial purchase volumes. For instance, major truck and trailer manufacturers, by virtue of their scale, can wield considerable influence over pricing and contractual terms with suppliers like JOST. These large order quantities naturally grant them significant negotiation leverage.
Customer switching costs significantly influence JOST's bargaining power. For Original Equipment Manufacturers (OEMs), once JOST components are integrated into a vehicle's design, the costs associated with re-testing, re-designing, and re-certifying a new supplier's parts can be substantial, often running into millions of dollars and significant lead times.
However, the picture changes for the aftermarket segment. Here, switching costs for more standardized replacement parts, like certain types of couplings or landing gear, can be considerably lower. This increased ease of switching makes these customers more price-sensitive, potentially eroding JOST's pricing power in that particular market.
Customer price sensitivity is a significant factor for JOST, especially with large Original Equipment Manufacturers (OEMs) in the commercial vehicle sector. These customers operate in a highly competitive landscape, constantly facing cost pressures. For instance, in 2024, the average profit margin for commercial vehicle manufacturers often hovers in the single digits, making every cost component critical.
The commercial vehicle market itself is projected for growth, with some analysts forecasting a compound annual growth rate (CAGR) of around 5% to 7% through 2028. However, this growth is tempered by ongoing challenges such as persistent supply chain disruptions and rising component costs, which were particularly acute in 2023 and continued into early 2024. These conditions amplify the OEMs' need to negotiate aggressively with their suppliers like JOST.
Large Original Equipment Manufacturers (OEMs) in the trucking industry, such as PACCAR and Daimler Truck, hold significant leverage due to their potential to backward integrate. For instance, if a substantial portion of JOST's revenue comes from more commoditized components, these OEMs could explore producing them internally, reducing their reliance on JOST and thus strengthening their bargaining position. This threat is particularly relevant for parts with less complex manufacturing processes.
However, the high capital expenditure and specialized engineering knowledge needed for JOST's core safety-critical products, like advanced fifth wheel couplings and robust landing gear systems, present a substantial barrier to full backward integration for most customers. These systems often require specific certifications and extensive R&D, making it economically unfeasible for many OEMs to replicate JOST's expertise and product quality in-house. For example, developing and validating a new fifth wheel design can cost millions of dollars and take years.
The bargaining power of customers for JOST is influenced by the degree of product standardization versus differentiation. While JOST operates in safety-critical systems, some components might be more commoditized, giving customers more choices and leverage.
However, JOST's strategic focus on innovation and highly differentiated offerings, such as advanced integrated smart features or superior performance characteristics, directly counters this by creating unique value propositions. This differentiation makes it harder for customers to switch and reduces their ability to negotiate on price or terms.
JOST's customer bargaining power is moderated by the significant switching costs for OEMs, especially for safety-critical components. However, for more standardized aftermarket parts, customers have greater price sensitivity and can more easily switch suppliers, increasing their leverage.
The potential for large OEMs to backward integrate into producing simpler components poses a threat, but the high capital investment and specialized expertise required for JOST's core, safety-critical products like advanced fifth wheels act as a strong deterrent, limiting this power.
JOST's ability to differentiate its offerings through proprietary technology and integrated smart features directly combats customer bargaining power by creating unique value and increasing switching costs.
| Factor | Impact on JOST's Customer Bargaining Power | Example/Data Point |
|---|---|---|
| Customer Concentration (Large OEMs) | High Leverage | Major truck manufacturers' substantial order volumes grant significant negotiation power. |
| Switching Costs (OEM Integration) | Low Leverage | Millions of dollars and extensive lead times for re-testing and re-designing new supplier parts. |
| Switching Costs (Aftermarket Standardization) | High Leverage | Lower costs for standardized replacement parts increase price sensitivity. |
| Price Sensitivity (OEMs) | High Leverage | Single-digit profit margins for commercial vehicle manufacturers in 2024 amplify cost pressure. |
| Backward Integration Threat | Moderate Leverage | Potential for OEMs to produce commoditized components internally. |
| Barriers to Integration (Specialized Systems) | Low Leverage | Millions in R&D and years of validation needed for advanced fifth wheels. |
| Product Differentiation | Low Leverage | Proprietary technology and smart features reduce alternatives and price sensitivity. |
This preview showcases the complete JOST Porter's Five Forces Analysis, reflecting the exact document you will receive immediately after purchase. You'll gain instant access to this professionally formatted and ready-to-use analysis, providing a clear understanding of the competitive landscape. No placeholders or sample content; what you see is precisely what you get to inform your strategic decisions.
The commercial vehicle component market, particularly for fifth wheels and landing gears, features a robust mix of global and regional manufacturers. Companies such as SAF-Holland, a prominent player, actively compete with numerous other established entities. This diversity ensures a dynamic marketplace where innovation and pricing are key differentiators.
The commercial vehicle market is seeing robust expansion, with global sales anticipated to climb from 2024 through 2025 and into the future. This upward trend in demand can somewhat soften the intensity of rivalry, as a larger market pie means less direct competition for every slice. However, the battle for market share within this growing sector remains fierce.
JOST distinguishes itself through robust brands and a commitment to innovation, particularly in safety-critical systems. This focus on advanced features and superior quality allows JOST to carve out a distinct market position, setting it apart from competitors offering more standard products.
For instance, JOST's continuous investment in R&D, which saw significant allocation in their 2024 fiscal year, directly translates into industry-leading products. This innovation pipeline is crucial in fending off rivals who might compete primarily on price or less sophisticated offerings.
High capital requirements for manufacturing plants, specialized research and development, and deeply entrenched customer loyalty significantly hinder companies from exiting the commercial vehicle components sector. These substantial investments mean that once a company is in, it's very difficult and costly to get out.
This difficulty in exiting the market forces existing players to remain, even when market conditions are unfavorable. Consequently, this intensifies competition among those who are already established, as they are committed to their operations.
JOST faces significant price competition, even with its safety-critical components for commercial vehicles. This is particularly evident in securing large volume Original Equipment Manufacturer (OEM) contracts and within the aftermarket segment. The pressure from numerous competitors, combined with the cost-consciousness of truck manufacturers, often forces aggressive pricing tactics.
For instance, in 2024, the global commercial vehicle market experienced fluctuating demand. This volatility, coupled with ongoing supply chain challenges that impacted component costs, intensified the need for competitive pricing. JOST’s ability to manage its cost structure is therefore crucial to maintaining market share and profitability in this price-sensitive environment.
Competitive rivalry in the commercial vehicle component market, including JOST, is intense due to numerous global and regional manufacturers. This dynamic landscape means companies must constantly innovate and offer competitive pricing to stand out.
Despite a growing market, the battle for market share remains fierce, with companies like JOST differentiating themselves through strong brands and advanced, safety-critical systems. This focus on quality and innovation is key in a sector where price pressure is significant, especially for large OEM contracts and the aftermarket.
| Competitor Example | Key Differentiator | 2024 Market Focus |
|---|---|---|
| SAF-Holland | Broad product portfolio, established global presence | OEM partnerships, aftermarket expansion |
| JOST | Brand strength, safety-critical innovation | R&D investment, premium product positioning |
| Other Established Players | Price competitiveness, regional strength | Cost optimization, volume sales |
The primary threat of substitutes for JOST's safety-critical systems stems from entirely different technologies or designs that can perform the same core functions. While JOST's current coupling mechanisms for trailers are dominant, the long-term emergence of alternative technologies or new vehicle architectures presents a significant substitution risk.
The threat of substitutes hinges on their ability to offer a compelling performance-price trade-off. If an alternative can deliver comparable safety and reliability at a much lower cost, or even better performance for a similar price, it presents a significant challenge. For instance, in the automotive sector, electric vehicles (EVs) are increasingly offering a competitive total cost of ownership compared to traditional internal combustion engine vehicles, driven by falling battery prices and lower running costs.
For original equipment manufacturers (OEMs), the safety-critical nature of JOST's products means customer willingness to switch to unproven or significantly different substitute technologies is inherently low. Rigorous testing protocols and stringent regulatory compliance, often taking years and substantial investment, create high switching costs for OEMs, anchoring them to established and certified suppliers like JOST.
Aftermarket customers, however, may exhibit a greater openness to cost-effective alternatives if these substitutes can demonstrably maintain the same safety standards. While JOST's premium brand and proven reliability are significant factors, the economic pressures in the aftermarket could drive some customers to explore substitutes, particularly if price differentials are substantial and third-party validation of safety is available.
Technological advancements in vehicle design represent a significant threat of substitutes for JOST. Innovations like modular chassis platforms and integrated smart systems could diminish the demand for specific, separate components that JOST currently provides. For instance, the increasing integration of vehicle functions into fewer, more complex modules might reduce the number of individual parts needed, directly impacting JOST's product portfolio.
The automotive sector's rapid embrace of artificial intelligence (AI), advanced driver-assistance systems (ADAS), and autonomous driving technologies is reshaping component requirements. These evolving technologies may lead to the development of entirely new types of components or render existing ones obsolete. By 2024, the global market for ADAS was valued at approximately $30 billion, with projections indicating substantial growth, suggesting a shift in demand towards more sophisticated, integrated electronic and sensor-based systems.
Stringent regulatory and safety standards for commercial vehicles significantly act as a barrier to substitutes. Any new technology entering the market must not only perform but also meet or surpass these rigorous requirements, which often involve extensive testing and certification processes. For instance, in 2024, the European Union continued to update its General Safety Regulation (GSR), mandating advanced driver-assistance systems (ADAS) in new vehicles, a costly hurdle for potential disruptors.
JOST's long-standing compliance and well-earned reputation for safety provide a substantial advantage against emerging substitutes. Their existing infrastructure and expertise in navigating these complex regulations mean they are better positioned to adapt to evolving standards. This established trust with customers and regulators makes it harder for new entrants, lacking this track record, to gain market traction.
The threat of substitutes for JOST's products is moderate, primarily due to the high switching costs and regulatory hurdles in the commercial vehicle sector. While new technologies could emerge, the established safety standards and JOST's reputation create a significant barrier to entry for alternatives.
However, the automotive industry's rapid evolution, particularly in areas like advanced driver-assistance systems (ADAS) and integrated vehicle platforms, presents a growing substitution risk. The global ADAS market, valued at approximately $30 billion in 2024, signifies a major shift towards electronic and software-driven solutions, potentially impacting demand for traditional mechanical components.
| Factor | Impact on JOST | Notes |
|---|---|---|
| Technological Advancements | Moderate to High | Emerging integrated systems and autonomous driving tech could reduce demand for standalone components. |
| Regulatory Compliance | Low to Moderate | Stringent safety standards (e.g., EU GSR) create high barriers for substitutes, favoring established players like JOST. |
| OEM Switching Costs | Low | Rigorous testing and certification for safety-critical parts make OEMs hesitant to switch from trusted suppliers. |
| Aftermarket Price Sensitivity | Moderate | Cost-conscious aftermarket customers may explore validated, lower-cost substitutes if safety standards are met. |
The capital requirements for entering the commercial vehicle component market, especially for safety-critical parts, are immense. Companies need to invest heavily in research and development, cutting-edge manufacturing plants, and rigorous testing facilities to meet stringent industry standards. For instance, establishing a new, compliant production line for advanced driver-assistance systems (ADAS) components could easily run into tens of millions of dollars, if not hundreds of millions.
JOST, as an established leader in the commercial vehicle components sector, enjoys significant cost advantages due to its economies of scale. For instance, in 2024, JOST's substantial production volumes allowed for more efficient raw material purchasing and optimized manufacturing processes, leading to lower per-unit costs that a new entrant would find exceptionally difficult to replicate. This scale directly translates into competitive pricing power, creating a substantial hurdle for newcomers aiming to gain market share.
JOST benefits from deeply ingrained brand loyalty and decades-long relationships with major Original Equipment Manufacturers (OEMs) and aftermarket clients globally. This established trust is a significant barrier for newcomers. For instance, in 2024, the heavy-duty truck market, a key sector for JOST, continued to emphasize supplier stability and product performance, making it challenging for unproven brands to secure initial contracts.
Newcomers face significant hurdles in securing access to the well-established global distribution networks for commercial vehicle components, encompassing both original equipment manufacturer (OEM) and aftermarket channels. JOST's existing, far-reaching distribution infrastructure represents a formidable competitive barrier that is not easily replicated in the short term.
This difficulty in accessing distribution channels directly impacts the threat of new entrants by limiting their ability to efficiently reach customers and establish a market presence. For instance, in 2024, the commercial vehicle aftermarket was characterized by strong loyalty to established suppliers with proven distribution capabilities, making it harder for new players to gain shelf space or secure partnerships.
JOST's robust portfolio of proprietary technology and patents presents a significant hurdle for potential new entrants. These intellectual property rights create legal barriers, making it difficult and costly for competitors to replicate JOST's innovative and safety-critical systems. For instance, patents on advanced coupling technologies or automated fifth-wheel systems would require extensive R&D and legal navigation for any new player.
The sheer investment and time needed to develop comparable, compliant, and equally effective solutions are substantial deterrents. This technological moat not only protects JOST's existing market share but also allows it to command premium pricing and maintain its leadership position in the commercial vehicle component industry.
The threat of new entrants into the commercial vehicle component market, where JOST operates, is generally considered low. This is primarily due to the substantial capital required for research, development, and manufacturing, coupled with the need to meet stringent safety and performance standards. For example, in 2024, the cost to establish a compliant production facility for advanced braking systems could easily exceed $50 million.
JOST's established economies of scale, strong brand loyalty, and extensive distribution networks further solidify this barrier. New players struggle to match JOST's per-unit cost efficiencies, which are a result of high production volumes. Furthermore, securing contracts with major Original Equipment Manufacturers (OEMs) in 2024 remained challenging for unproven entities, as OEMs prioritize supplier reliability and proven performance.
The company's portfolio of proprietary technology and patents also acts as a significant deterrent. Developing comparable, innovative, and safety-certified components requires immense R&D investment and often involves navigating complex intellectual property landscapes. This technological advantage, combined with the high entry costs, makes it exceptionally difficult for new competitors to gain meaningful traction.
| Factor | Impact on New Entrants | JOST's Advantage |
| Capital Requirements | Very High (R&D, Manufacturing, Testing) | Economies of scale, established infrastructure |
| Brand Loyalty & OEM Relationships | Low (Difficult to establish) | Decades of trust, proven track record |
| Distribution Networks | Limited Access (Costly to replicate) | Global, well-established channels |
| Proprietary Technology & Patents | High Barrier (R&D, Legal) | Patented innovations, strong IP portfolio |


