
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
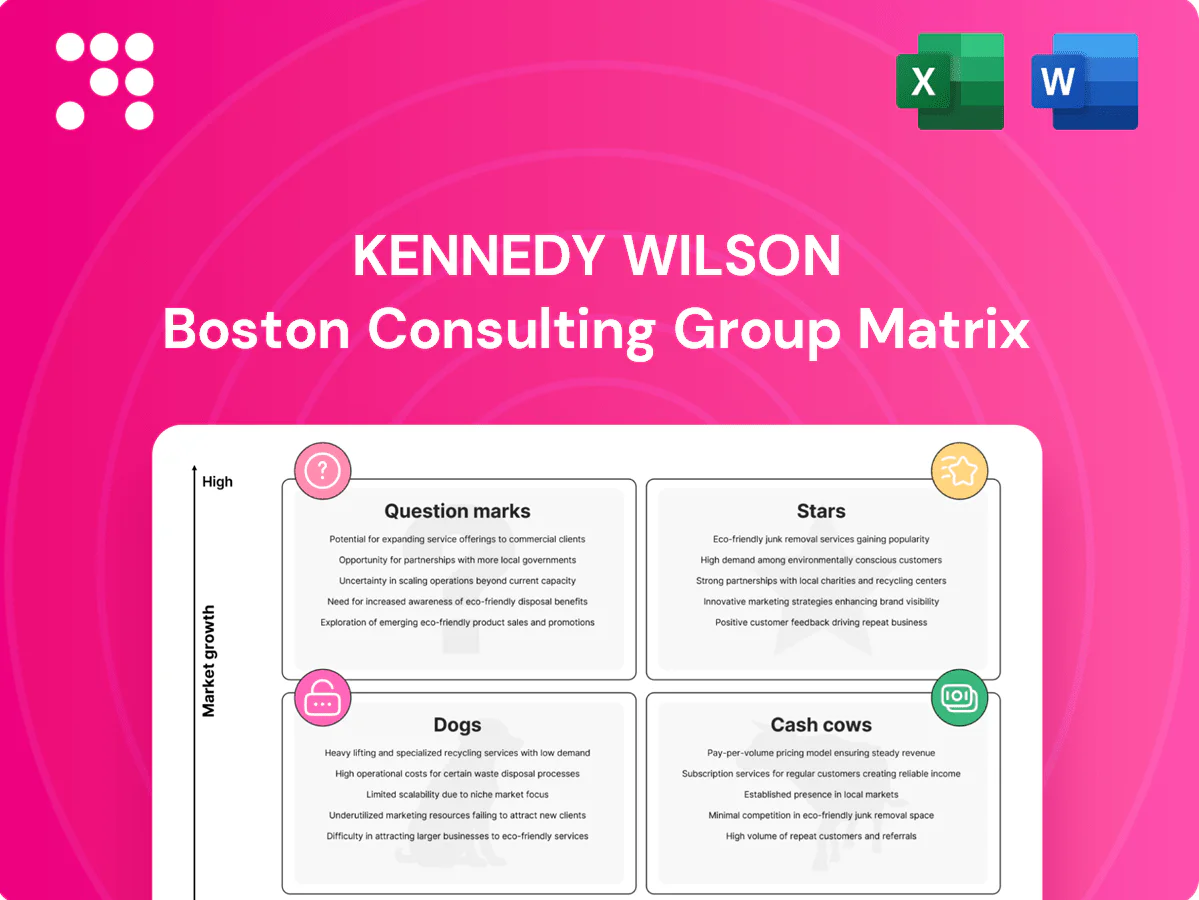
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Kennedy Wilson’s assets sit — Stars, Cash Cows, Dogs, or Question Marks? This preview scratches the surface; the full BCG Matrix gives you quadrant-by-quadrant placement, data-backed recommendations, and tactical moves tailored to this portfolio. Buy the complete report for a ready-to-use Word summary plus an Excel dashboard you can present or act on immediately. Get clarity fast and decide where to invest, divest, or double down.
High occupancy above 95% in 2024 and mid-single-digit rent lifts last year paired with deep operating know-how place Kennedy Wilsons Western value-add multifamily platform in the lead as demand climbs. It soaks up acquisition and renovation capital but cashflow velocity and NOI uplifts repay investments quickly; keep feeding it to compound the edge, then hold share as growth moderates and it tilts into cow territory.
Lease-up momentum is strong and constrained supply is driving share gains for Kennedy Wilson’s U.K. & Ireland build-to-rent Stars; industry pipeline exceeded 150,000 homes in 2024, keeping demand durable. These assets require heavy upfront capex and branding to scale, but improving absorption—rent growth and occupancy recovery—has started to reward that outlay. Execution risk is real, yet the runway remains long; stay aggressive while the market expands.
Kennedy Wilsons assets under management climbed into the mid-teens billion range by 2024, driving scale as its operating engine extracts differentiated returns in hot rental markets. Fund launches and co-invests require upfront cash for origination, teams and incentives, often compressing near-term cash flow. The payoff is recurring management fees (typically ~1–1.5%) plus performance upside (carried interest ~10–20%). Lean into anchor mandates and first‑close speed to accelerate fee-bearing AUM growth.
Multifamily repositioning and lease‑to‑market at Kennedy Wilson targets fast‑growing Sunbelt submarkets where operational playbooks yield rapid rent roll‑ups; industry data in 2024 showed average rent growth of ~8–10% in top Sunbelt metros, offsetting turn costs typically $3,000–5,000/unit and delivering NOI uplifts often in the high single‑digits to low double‑digits within 12–18 months.
Competitors accelerate acquisitions, but KW’s scale, proprietary leasing and asset‑management datasets and repeatable turn processes sustain a competitive edge; the strategy emphasizes recycling capital into the highest‑IRR turns, consistent with reported portfolio prioritization in 2024 toward value‑add multifamily.
Selective distressed acquisitions in supply‑constrained nodes create leader’s advantage where Kennedy Wilson can move first; these opportunities are cash‑hungry and demand sharp underwriting plus intensive asset management. Early entries establish pricing power as markets normalize, converting current investments into future cash cow positions.
Western value‑add multifamily: >95% occupancy (2024) and rapid NOI payback; feed capital to compound returns. U.K./Ireland BTR: pipeline ~150,000 homes (2024), strong lease‑up but high upfront capex. AUM mid‑teens $bn (2024) drives fee income while recycling capital into highest‑IRR turns.
| Metric | 2024 |
|---|---|
| Occupancy | >95% |
| Rent growth (Sunbelt) | 8–10% |
| AUM | mid‑teens $bn |
| Pipeline UK/IE | ~150,000 homes |
 Detailed Word Document
Concise BCG Matrix review of Kennedy Wilson's assets—stars, cash cows, question marks, dogs—with investment and divestment guidance.

 Customizable Excel Spreadsheet
One-page Kennedy Wilson BCG Matrix placing each business unit in a quadrant to remove analysis friction for faster exec decisions
Stabilized Class B/B+ multifamily in core Western markets typically shows high occupancy around 95% in 2024, modest capex (~$700–$1,200/unit/year) and dependable cash flow yielding roughly 6–8% stabilized cash-on-cash. Limited market growth reduces promotion spend and keeps margins steady, quietly funding new investments. Optimize expenses and pursue refinances to shave 100–200 bps off cost of capital and boost yield.
Kennedy-Wilson (NYSE: KW) holds core commercial assets with long leases to strong credits that reliably generate free cash flow, keeping leasing risk and TI/LC burn contained. Hold these cash cows, prune only when market pricing is rich. Milk proceeds into higher-growth rental opportunities to boost portfolio returns and capital deployment.
In-house property management on the owned portfolio lets Kennedy Wilson capture fees and control service quality from a platform managing over $10bn AUM in 2024, already scaled across thousands of units. Low incremental cost to add doors improves margins as same teams/technology absorb growth. Standardizing ops, tech, and procurement widens the spread. The predictable cash flow from management fees reliably backstops development timing.
Asset management and promote on seasoned funds/JVs generate predictable base fees with occasional promote crystallizations tied to asset disposals; growth is modest but retention of LPs and operating partners remains high and operating costs are largely fixed.
Stabilized NOI from de‑risked Kennedy Wilson assets supports favorable refinancing and interest‑savings, freeing cash flow despite limited organic growth; real dollars can be repatriated to the mothership to fund operations or capital allocation priorities.
Stabilized Class B/B+ multifamily: occupancy ~95% in 2024, capex $700–$1,200/unit/year, stabilized cash-on-cash 6–8%. Core commercial long leases generate predictable free cash flow; hold and deploy proceeds into higher-growth rentals. In-house management across >$10bn AUM (2024) expands margins and funds refinancings to trim cost of capital.
| Metric | 2024 |
|---|---|
| Occupancy | ~95% |
| CapEx/unit | $700–$1,200 |
| Cash-on-cash | 6–8% |
| AUM | $10bn+ |
The file you're previewing here is the exact BCG Matrix report you'll receive after purchase—no watermarks, no demo fluff, just the finished, professionally formatted document. It’s built for immediate use: edit, print, or present straight away. Delivered instantly to your inbox, the analysis is market-ready and clear. No surprises, just strategic clarity you can plug into planning or client decks.
Legacy suburban office holdings face low demand and 19.3% U.S. office vacancy (Q1 2024, CBRE), with concessions up ~25% year‑over‑year and capex needs rising ~15%—a clear cash trap. Kennedy Wilson’s market share in such assets is small and shrinking versus flex and urban alternatives. Turnarounds require heavy capital with thin odds. Best course: sell, convert to alternative use, or walk away fast.
Non-core retail strips in declining trade areas show tenant quality and traffic down, with market vacancy around 7% in 2024 and secondary retail cap rates near 8–10%. Re‑leasing costs often run ~$40 per sq ft, which absorbs most operating cash flow. These assets offer minimal growth and little operational control. Exit on any reasonable bid given weak fundamentals and cash burn.
Small one-off third-party services divert Kennedy Wilson management without scale advantages; such boutique services typically run at single-digit operating margins and industry churn often exceeds 25% annually, leaving weak pricing power. Time and talent are tied up for little return, eroding fee revenue and operational focus. Consolidate into scalable platforms or exit to preserve capital and improve portfolio weighting.
Dogs: over‑custom construction management for tiny projects is high touch, low ticket and produced messy margins in 2024, with small renovation jobs averaging under 10% gross margin (industry reports); scope creep routinely wipes out fees and billing velocity. Pipeline volume for micro‑projects is insufficient to justify dedicated bandwidth at Kennedy Wilson; standardize pricing and scope or exit.
Remote geographies outside Western U.S./U.K./Ireland show limited relationships and no scale moat, driving operational headaches while returns remain muted for Kennedy Wilson.
Market share in these regions stays low and stagnant, prompting a dispose-and-refocus approach to redeploy capital where KW has proven competitive advantages.
Dogs: legacy suburban offices (US vacancy 19.3% Q1 2024), non‑core retail (vacancy ~7% 2024), micro construction (avg gross margin <10% 2024) and remote geographies show low growth, high capex and thin margins—recommend dispose, convert, standardize or exit.
| Asset | 2024 Metric | Action |
|---|---|---|
| Suburban office | 19.3% vacancy | Sell/convert |
| Retail strips | ~7% vacancy | Exit |
| Micro construction | <10% margin | Standardize/stop |
Kennedy Wilson's Ireland post‑delivery pipeline is a Question Mark: big upside if lease‑ups hit pro‑forma in a tight Dublin market where office vacancy was ~17% in 2024, supporting rent recovery and valuation upside. Construction and timing risks remain until stabilization, with exposure to cost overruns and financing shifts. Requires a marketing push and accelerated lease velocity; consider funding through completion or partnering down equity if delays stack up.
U.K. fund vehicles targeting rental housing attract strong LP interest but early track records remain thin; the private rented sector comprises about 20% of households per ONS 2021, underpinning demand. Fee ramps hinge on timing of first closes and deployment speed; several PRS platforms achieved first closes in 2024. With anchor commitments they could scale into a Star. Sponsor must commit origination resources and GP co‑invest or shelve.
Massive demand tailwinds — NLIHC estimates a shortage of roughly 7.3 million rental homes affordable to extremely low-income households in 2024 — but complex execution: land, entitlement and service-delivery JVs raise development timelines and risk. Returns hinge on layered incentives, tight cost control and speed to lease; current market share for Kennedy Wilson is small but can compound via JVs. Decision: scale with a dedicated team to capture subsidy stacking and operational synergies or exit quietly.
Pipeline for credit/loan acquisitions tied to multifamily is expanding amid lender pullback since the 2023 banking stress, but pricing discovery remains dislocated; servicing and workout expertise are essential to capture accretive returns.
Early platform wins can scale into a niche—test, prove, then commit capital selectively to convert optionality into earnings.
Light industrial/last‑mile in select Western submarkets shows healthy demand—average vacancy ~3.2% in 2024—and strong rent momentum, but Kennedy Wilson’s share is nascent and competition is seasoned; operating playbook must be built from scratch. If pilot purchases demonstrate sustained rent growth of 3–5% and capex <6% of asset value, scale quickly; otherwise pass and remain residential‑centric.
Kennedy Wilson Question Marks: Ireland office pipeline offers upside if lease‑ups meet pro‑forma amid Dublin 17% vacancy (2024). UK PRS platforms (PRS ~20% households, ONS 2021) need scale to become Stars. Affordable housing shows 7.3M shortage (NLIHC 2024); execution risk high. Last‑mile vacancy ~3.2% (2024) — pilot then scale.
| Asset | Key 2024 metric | Trigger |
|---|---|---|
| Ireland office | 17% vacancy | stabilize leases |
| UK PRS | 20% households | scale & fees |


