
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
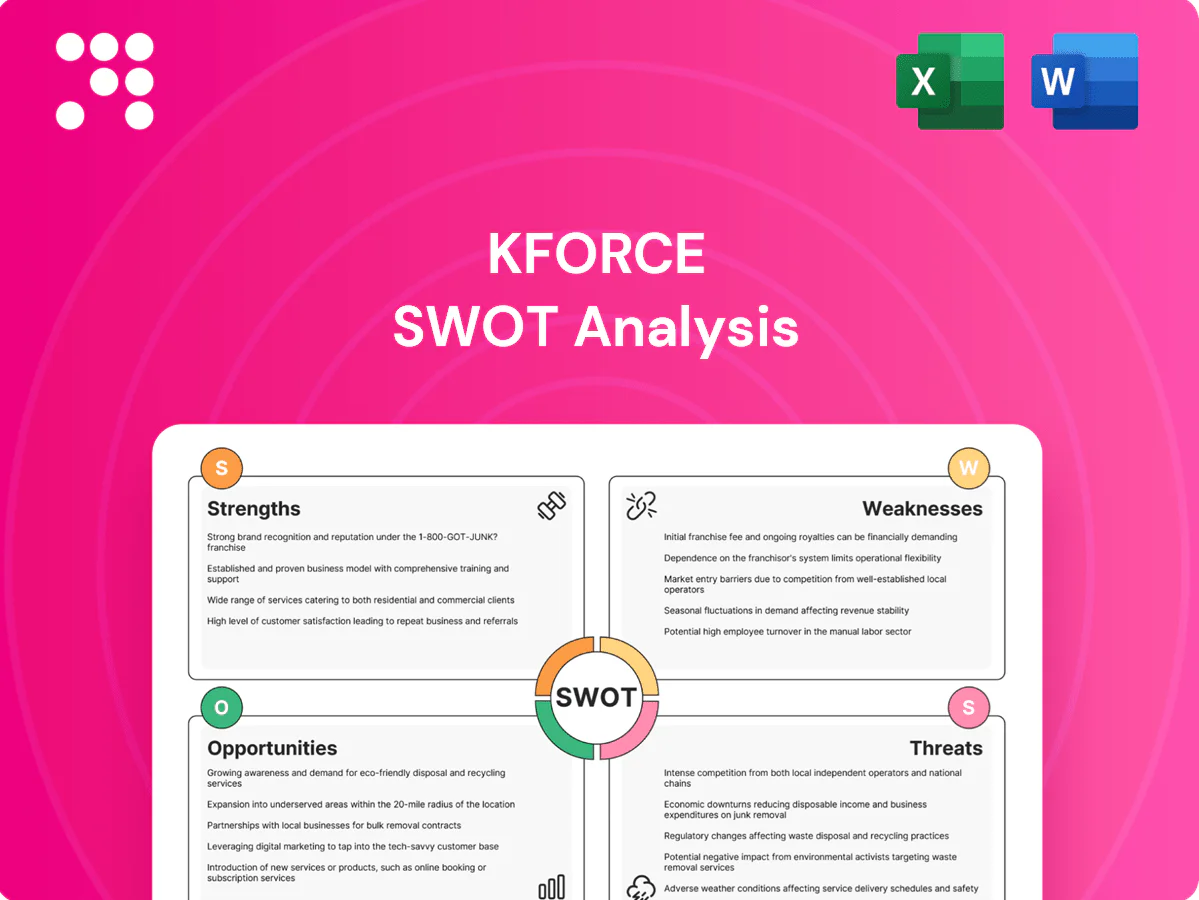
Kforce's SWOT analysis highlights its strong client relationships and flexible staffing model, alongside risks from market cyclicality and competitive pressure. Explore growth drivers like digital services expansion and margin improvement opportunities. Purchase the full, research-backed SWOT report (Word + Excel) for actionable insights to inform strategy, investment, or pitches.
Focused domain expertise in Tech and F&A elevates candidate quality and speed-to-fill, supporting Kforce’s FY2024 revenue of roughly $1.6 billion and its ~2,800 employees serving specialist roles. Recruiters build niche talent pools for high-demand skills like cloud and fintech, enabling bill-rate premiums versus generalists. This specialization drives higher placement retention and measurable client satisfaction gains.
Balanced mix of contract and direct hire diversifies Kforce revenue and smooths cyclical swings, with contracting delivering recurring billings while direct hire enhances margins during upcycles.
Clients value a single partner for contingent and permanent staffing, increasing wallet share and reducing vendor fragmentation.
This blend improves client stickiness and supports stable cash flow and margin expansion over cycles.
Longstanding client relationships at Kforce (NASDAQ: KFRC) — which generated about $1.9B in revenue in fiscal 2024 — shorten sales cycles and lift repeat business, improving revenue visibility. Alumni candidates and referral pipelines cut sourcing costs and time-to-fill. Network effects raise fill rates for niche IT and finance roles, creating defensible differentiation versus new entrants.
Standardized recruiting workflows and integrated ATS/CRM enable Kforce to scale delivery efficiently; the firm generated $1.34B in revenue in FY2023, underscoring operational reach. Robust onboarding, payroll and worker-classification controls materially reduce compliance and misclassification risk. Compliance strength is a decisive buyer criterion for enterprise accounts and supports multi-location programs and rapid surge hiring.
Kforce delivers technology and finance & accounting talent across healthcare, financial services, retail and the public sector, which mitigates single-industry shocks and helps stabilize utilization rates. Cross-industry demand broadens hiring pipelines and keeps placement volumes more consistent through economic cycles. Diverse sector exposure supports growth opportunities when one vertical softens.
Kforce’s Tech & F&A specialization drives higher bill rates, faster fills and strong retention; FY2024 revenue ~ $1.9B and ~2,800 employees underpin scale. Mix of contract and direct hire smooths cycles and boosts margins in upcycles. Enterprise-grade ATS/CRM, payroll and compliance reduce misclassification risk and support multi-location surge staffing.
| Metric | Value |
|---|---|
| FY2024 Revenue | $1.9B |
| FY2023 Revenue | $1.34B |
| Employees | ~2,800 |
 Detailed Word Document
Delivers a strategic overview of Kforce’s internal and external business factors, outlining strengths, weaknesses, opportunities, and threats to assess its competitive position, growth drivers, operational gaps, and future risks.

 Customizable Excel Spreadsheet
Provides a focused SWOT for Kforce to quickly identify talent-market risks and growth levers, easing strategic prioritization and accelerating decision-making for executives and HR leaders.
Demand tracks IT and corporate hiring cycles closely, so slowdowns, hiring freezes or capex cuts hit Kforce volumes quickly and can reduce billable hours and placements. Kforce’s SEC filings note limited visibility beyond near-term requisitions, and revenue often fluctuates sharply quarter to quarter. This cyclicality increases forecast risk and working-capital volatility.
Enterprise clients increasingly route roles through VMS/MSP intermediaries; Everest Group reported in 2024 that MSPs/VMS manage roughly 60% of enterprise contingent workforce spend, pushing more volume off direct channels.
Standardized rate cards and supplier scorecards compress spreads, narrowing Kforces bill-to-pay margin even as placements scale.
Heightened compliance, reporting and SLA obligations raise cost-to-serve and operational overhead, diluting profitability despite large volumes.
Competition for cloud, data, cybersecurity and AI talent is intensifying, driving longer time-to-fill and higher pay rates that compress Kforce's gross margins; increased candidate falloffs and counteroffers raise rework and recruiting costs. Delivery risk grows for niche roles as placements are harder to secure and retain, straining bench utilization and client SLAs.
Staffing services like Kforce face low switching costs as clients treat talent suppliers as substitutable; Kforce reported roughly $1.5B revenue in FY2024, yet relies on repeat requisitions rather than locked-in contracts. Clients often keep multi-vendor lists and rotate work, making differentiation beyond speed and price hard to sustain, so churn risk persists without embedded solutions.
Kforce's revenue is heavily concentrated in the U.S., with major exposure to technology and financial services verticals, so regional tech slowdowns quickly reduce req volumes and billable hours. Limited international operations constrain geographic diversification, which can magnify volatility during U.S.-centric downturns. This concentration raises sensitivity to local labor-market and economic shocks.
Demand tracks hiring cycles, causing quarter-to-quarter revenue volatility; FY2024 revenue was $1.5B. MSP/VMS manage ~60% of enterprise contingent spend (Everest 2024), reducing direct volume and compressing spreads. Competition for cloud/data/AI talent and low switching costs raise time-to-fill, recruiting costs and churn risk.
| Metric | Value |
|---|---|
| FY2024 revenue | $1.5B |
| MSP/VMS market share | ~60% (Everest 2024) |
| Geographic focus | Primarily U.S. |
This is the actual Kforce SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report; buying unlocks the complete, editable version with in-depth strengths, weaknesses, opportunities, and threats. The file shown is the real analysis you'll download post-purchase.
Cloud, data modernization and cybersecurity initiatives drove sustained IT staffing demand, with enterprise security spending topping roughly $180B globally in recent years, boosting contractor needs. Finance transformation and ERP upgrades are expanding F&A roles as companies modernize back offices. Multi-year programs create steady 12–24 month requisition pipelines. Kforce can align talent pipelines to these roadmaps to capture recurring demand.
Offering statements of work and outcome-based teams can lift Kforce margins by shifting revenue from low-margin headcount to higher-margin project work; industry data show managed services grew about 10–12% in 2024, driving client demand for deliverables over bodies. Clients increasingly prefer vendors that guarantee outcomes, which deepens account embedment and creates upsell pathways, differentiating Kforce from pure staff-augmentation peers.
AI-enabled sourcing, matching, and de-biasing can cut time-to-fill by up to 30% and improve fit, while Deloitte 2024 found 42% of firms using AI in HR, signaling adoption tailwinds for Kforce. Predictive analytics can lift forecast accuracy and guide rate-setting, supporting margin management during demand swings. Productivity gains (20–25% reported in industry pilots) expand recruiter capacity and make data products a client-facing revenue stream.
Train-to-hire and reskilling pipelines let Kforce close client skill gaps faster while converting trainees into billable consultants, strengthening margin stability and repeat business. Partnerships with bootcamps and universities secure early-career talent pipelines and lower sourcing costs. Co-funded client programs increase retention and create a proprietary, high-fit candidate supply for hard-to-fill roles.
Public sector, healthcare, and financial services drive countercyclical staffing demand; BLS projects healthcare employment growth of about 12% from 2022–2032, and Kforce reported FY2024 revenue of approximately $1.9B, reflecting strength in regulated verticals. Compliance-heavy buyers prefer vetted suppliers and contract vehicles (GSA, IDIQ) that create recurring revenue visibility, helping diversify and stabilize Kforce’s portfolio.
Cloud/data modernization, cybersecurity ($180B enterprise spend) and ERP/finance transformations fuel 12–24 month staffing pipelines; Kforce FY2024 revenue ~$1.9B positions it to capture recurring demand. Shift to outcome-based managed services (10–12% growth in 2024) and AI sourcing (42% HR AI adoption, 30% faster fill) can lift margins and capacity.
| Tag | Stat | Impact |
|---|---|---|
| Cybersecurity | $180B | Higher contractor demand |
| Managed services | 10–12% 2024 | Margin uplift |
| AI/HR | 42% adoption | 30% faster fill |
| Healthcare | BLS +12% (22–32) | Countercyclical demand |
Recession risks and persistent Fed tightening (federal funds ≈5.25–5.50% mid‑2025) quickly curtail discretionary projects and push clients to pause hiring. Cost‑cutting and rate sensitivity delay requisitions, elongating decision cycles and lowering pipeline conversion. Even with unemployment near 3.7% (end‑2024), client uncertainty depresses billable hours and shortens project scopes, pressuring Kforce’s revenue visibility.
Marketplaces and freelance platforms (Upwork revenue ~$1.03B in 2024) lower transaction costs, while many enterprises pilot direct-sourcing programs to bypass vendors; procurement digitization is shrinking curated vendor lists. For Kforce (FY2024 revenue ~$1.62B) this trend can erode volumes and pricing power, pressuring margins and bill rates.
Shifts in worker-status rules such as California's AB5 and expanding state-level tests increase compliance costs for Kforce by complicating onboarding and payroll processes. Misclassification can trigger back taxes, benefits liabilities and penalties that have cost firms hundreds of thousands per matter in high-profile cases. Intensified federal and state enforcement since 2020 raises audit risk across jurisdictions. Clients may cut contractor use to avoid exposure, pressuring revenue.
Talent pay growth has risen faster than client bill-rate inflation, narrowing spread per hour and squeezing Kforce gross margins; US average hourly earnings rose about 3.5% y/y in 2024 while benchmark bill-rate increases lagged, and the Fed funds rate remained near 5.25% into 2025, tightening client budgets. Competitive bidding forces discounting, so profitability falls even if staffing volumes remain steady.
Global staffing majors compete on scale and price, pressuring margins as the global staffing market exceeded $500 billion in 2024 (SIA). Niche boutiques outmaneuver Kforce on specialized roles and speed, while consulting firms shift engagements into managed services, reducing traditional placement volumes. Intensified share battles lift acquisition costs and compress win rates across key verticals.
Macro tightening (fed funds ~5.25–5.50% mid‑2025) and recession risk curb client hiring and billable hours, reducing revenue visibility for Kforce (FY2024 revenue ~$1.62B). Marketplaces (Upwork ~$1.03B 2024) and direct sourcing compress volumes and pricing; wage growth (~3.5% y/y 2024) outpaces bill‑rate gains, squeezing margins. Regulatory shifts (AB5/state tests) raise compliance/audit costs and client contractor pullback.
| Metric | Value |
|---|---|
| Fed funds | ~5.25–5.50% (mid‑2025) |
| Kforce rev | ~$1.62B (FY2024) |
| Upwork rev | ~$1.03B (2024) |
| Staffing mkt | >$500B (2024) |


