
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
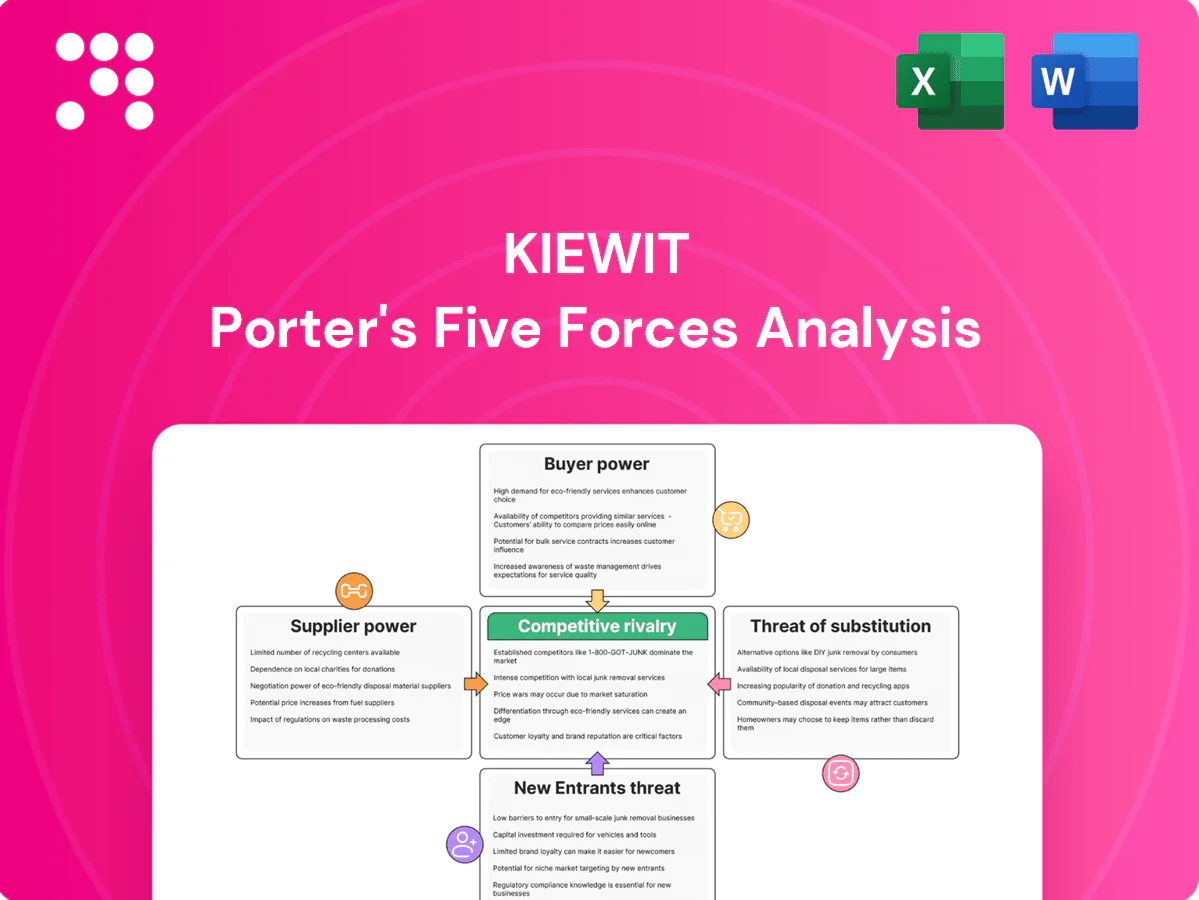
Kiewit's Porter's Five Forces snapshot highlights strong supplier relationships, moderate buyer power, high rivalry in construction and engineering, barriers limiting new entrants, and limited substitute threats. This brief view teases key strategic pressures and competitive levers. Unlock the full Porter's Five Forces Analysis to explore force-by-force ratings, visuals, and actionable insights tailored to Kiewit.
Large Kiewit projects rely on cement, steel, turbines, pipe and heavy equipment from concentrated global suppliers — China produced about 54% of world steel in 2024, reinforcing supplier concentration. Multiple vendors exist but rigorous qualification and 12–24 month turbine/equipment lead times limit substitution. Bulk commodity price swings have shifted leverage mid-project; Kiewit offsets risk via multi-sourcing and hedging where feasible.
Skilled subs in electrical, instrumentation and tunneling became bottlenecks in the 2024 market, pushing specialty trade wage growth and leading to project delays. Unionization in construction is around 13% (BLS 2023–24), which elevates regional supplier leverage and wage baselines. Tight capacity increases performance risk; Kiewit’s self-perform model materially reduces dependence on high-power subcontractors.
BIM/CAD, survey and project-controls platforms create switching costs and training dependencies—firms often face 3–5 year contract terms and onboarding costs commonly in the $50k–$200k range. Certification and data-integration requirements limit rapid provider changes, letting vendors exert moderate power via licensing and support terms, while long-term enterprise agreements partially temper pricing exposure.
Overseas fabrication, port congestion and volatile freight rates undermine delivery certainty for Kiewit; the Drewry World Container Index fell over 80% from 2021 peaks to 2024 but schedule risk remains and lead-time variability rose in Red Sea and Suez-area disruptions. Schedule sensitivity increases supplier leverage when expediting is needed; geopolitical constraints narrow alternative sources. Early procurement and buffer stock reduce pressure.
Kiewit’s vertical integration—self-performing civil, structural and select MEP scopes—internalizes value and captures margin that would otherwise flow to subcontractors. Owning extensive equipment fleets reduces dependence on rental suppliers, blunting supplier pricing power and schedule risk while strengthening negotiation leverage with remaining vendors.
Suppliers wield moderate-to-high power on materials (steel: China 54% of 2024 output) and long-lead turbines (12–24mo), while specialty subs and 13% construction unionization (BLS 2023–24) raise labor leverage. Kiewit’s self-perform, equipment fleets, multi-sourcing and hedging mitigate pricing and schedule risk; BIM/contracts add switching costs ($50k–$200k onboarding).
| Metric | 2024 value |
|---|---|
| China share of steel | 54% |
| Turbine/equipment lead time | 12–24 months |
| Construction unionization | 13% (BLS 2023–24) |
| Drewry WCI change vs 2021 | down >80% |
| Onboarding cost (BIM/tools) | $50k–$200k |
 Detailed Word Document
Uncovers key drivers of competition, customer influence, and market entry risks tailored to Kiewit's construction and engineering operations, evaluating supplier and buyer power, threat of substitutes, intensity of rivalry, and barriers that protect incumbents.

 Customizable Excel Spreadsheet
One-sheet Porter's Five Forces tailored for Kiewit—instantly highlights contractor-specific risks and bargaining pressures for faster, board-ready decisions. Swap in updated project data or scenarios to see strategic pressure shift and relieve analysis bottlenecks.
Public agencies, utilities and energy majors procure at scale under professional processes, supported by federal programs such as the Bipartisan Infrastructure Law which authorized about 550 billion dollars in new infrastructure funding. Their sophistication and volume give them strong negotiating leverage to dictate contract terms, risk allocation and compliance. Kiewit counters with a long track record and documented capability to deliver complex EPC scopes, and is regularly ranked among ENR’s top contractors.
Competitive tendering—driven by low-bid and best-value RFPs—compresses margins as owners increasingly prize price and measurable value, often forcing 5–15% bid concessions in contested heavy-civil projects. Pre-bid transparency tools let owners compare apples-to-apples, amplifying buyer power and favoring fixed-price, lump-sum EPC structures that shift cost and schedule risk to contractors. Kiewit, reporting roughly $13 billion revenue in 2024, counters with rigorous estimating, standardized contingency governance and disciplined risk allocation to protect margins.
Owners push liquidated damages, performance guarantees, and onerous change terms, elevating buyer leverage over cost, schedule, and quality; Flyvbjerg et al. show large projects average ~28% cost overruns, underscoring this pressure. Contractors must price or negotiate these risks effectively, shifting or pricing contingencies. Kiewit’s legal and project controls discipline materially helps balance exposures on high-stakes bids and change management.
Long-term master agreements and partnering models reduce transactional pressure by locking in multi-year workstreams, while buyers demand continuous improvement and periodic cost-downs as contract conditions. Relationship capital from repeat engagements lowers switching frequency and supports predictable backlog that can offset lower unit margins.
End-market exposure across six sectors—transportation, water, power, OGC, buildings, and mining—limits Kiewit’s dependence on any single buyer and reduces buyer concentration risk through cycle diversification. This sector mix lets management reallocate resources toward higher-margin or faster-growing projects when markets diverge, lowering aggregate buyer power over time. Operational scale across those markets strengthens bargaining leverage with large public and private clients.
Public agencies and energy majors wield strong leverage via scale and federal programs (BIL ~550 billion), while Kiewit reported ~13 billion revenue in 2024 and leverages reputation to negotiate. Competitive tendering compresses margins (typical bid concessions 5–15%) and owners push liquidated damages amid ~28% average cost overruns. Long-term agreements across six sectors reduce buyer concentration and stabilize backlog.
| Metric | Value | Note |
|---|---|---|
| Revenue 2024 | $13B | Company reported |
| BIL funding | $550B | Authorized |
| Bid concessions | 5–15% | Typical |
| Avg cost overrun | 28% | Large projects |
| Sectors | 6 | Diversified exposure |
You’re viewing the Kiewit Porter's Five Forces Analysis preview: the exact, fully formatted document you’ll receive immediately after purchase. This file is complete, professional, and ready for download—no placeholders or samples. Purchase grants instant access to this same analysis for use in decision-making, reporting, or strategy work.
Rivalry is intense with Bechtel, Fluor, Skanska, AECOM, Jacobs, Turner, PCL and regional majors, many listed among ENR Top 400 contractors in 2024. Overlapping EPC and heavy-civil capabilities drive frequent head-to-head bids, forcing aggressive pricing. Brand, safety record and past performance provide differentiation but are costly to secure. Margins compress sharply in crowded pursuits, pressuring bid discipline and backlog quality.
When backlogs thin peers often discount to keep crews and equipment utilized, compressing margins and forcing tactical pricing; Kiewit’s scale—about 28,000 employees—helps redeploy crews across regions. In booms selective bidding reduces price rivalry but intensifies competition for labor and subs, lifting input costs and bid cutoffs. Cyclicality drives volatile win rates and shifts in project mix, making utilization smoothing a strategic advantage for Kiewit.
Kiewit’s deep self-perform capability, constructability expertise and strong safety culture win best-value awards; ENR 2024 ranks Kiewit among the industry leaders, reflecting the scale behind that execution edge. Superior project controls reduce change-order disputes and claims, and owners in 2024 increasingly prioritize reliable delivery on critical-path packages. These execution factors temper pure price rivalry.
Consortia routinely form to meet bonding and capability thresholds on megaprojects, which commonly exceed $1 billion. JVs convert rivals into partners while widening bidder pools and preserving access to large contracts. Cross‑partner knowledge sharing narrows capability gaps over time, raising baseline competition. Careful partner selection—technical fit, balance sheet, past JV performance—is a decisive competitive lever.
Regional contractors defend home markets through entrenched relationships and local permitting know-how, creating de facto micro-moats that raise rivals’ bid costs; Kiewit, with roughly 28,000 employees and exposure to the US infrastructure boom funded by the $550 billion IIJA, mitigates but does not erase these effects. National players must price overhead and mobilization premiums into bids.
Rivalry is intense with ENR 2024 peers (Bechtel, Fluor, AECOM); overlapping EPC/civil bids force aggressive pricing and margin compression. Kiewit (~28,000 employees) uses scale to smooth utilization amid IIJA $550bn-driven demand. JVs/consortia for >$1bn projects widen bidder pools but preserve access to megaprojects.
| Metric | Value |
|---|---|
| Employees | ~28,000 |
| IIJA | $550bn |
| Megaproject threshold | >$1bn |
Owners frequently defer or downscope projects or choose maintenance over new builds, substituting opex for capex and directly reducing construction demand. Economic slowdowns magnify this behavior as firms preserve liquidity and delay capital projects. Such deferrals pressured backlog growth across contractors in 2023–24. Counter-cyclical public funding, notably the IIJA ($1.2 trillion enacted), can partially offset lost private demand.
Large utilities and DOTs often self-perform routine, predictable scopes, reducing contractor share, even as the Bipartisan Infrastructure Law (2021) mobilizes $1.2 trillion in infrastructure investment and expands in-house capacity. Peak loads and specialized tasks—e.g., tunnel, marine, and accelerated schedule work—still require prime contractors. Kiewit remains competitive on complex, schedule-critical packages where scale, technical depth, and bonding capacity are essential.
Prefabrication shifts value toward module yards and OEMs as offsite construction can cut onsite labor demand by up to 60% and compress schedules by as much as 50% (reported in industry studies through 2024). Site labor scope shrinkage alters contractor economics, reducing marginable onsite work and favoring integrators with module expertise who retain share. Kiewit’s EPC capability and yard partnerships position it to capture value from this shift.
Owners defer or downscope projects, cutting construction demand despite IIJA $1.2T support; prefabrication can cut onsite labor up to 60%, shifting value to yards/OEMs. DERs comprised ~10% of US capacity additions in 2024, while 3D printing ($1.8B) and composite pipes ($6.5B) accelerate substitution risk.
| Metric | 2024 |
|---|---|
| IIJA | $1.2T |
| Prefab labor reduction | 60% |
| DER share | 10% |
| 3D printing market | $1.8B |
| Composite pipes | $6.5B |
Large surety lines, substantial working capital and heavy equipment fleets—often requiring hundreds of millions to billions in liquidity and bonding—create steep entry costs. Megaprojects demand balance sheets and bonding capacity measured in hundreds of millions, favoring incumbents. Kiewit’s employee-owned structure aligns risk and incentives but still requires deep financial resilience. These factors form a high structural barrier.
Regulatory, safety, and QA/QC regimes impose high compliance costs for Kiewit-scale work, driving capital and certified-staff requirements. Owners commonly mandate a 3-year safety/incident record and EMR at or below 1.0 for prequalification, excluding many inexperienced firms. Incident history and EMR are routinely scrutinized, so new entrants typically require 2–5 years to build comparable credibility.
Owners heavily weight past performance and referenceability; Kiewit, founded 1884 (140 years in 2024), leverages deep, documented EPC track records that owners seek. Complex engineering-procurement-construction histories and repeatable systems are hard for newcomers to replicate, raising entry costs. Failures in large EPC projects often create long-lived brand penalties, and Kiewit’s legacy materially raises the bar for new entrants.
Kiewit leverages relationship-driven preferred subs, union halls, OEM allocations and yard slots; entrants lack that priority in 2024, raising costs and schedule risk during capacity crunches. Established networks and a ~28,000-strong workforce reinforce a durable moat against new entrants.
Local specialists can enter Kiewit niches in limited geographies or scopes, but scaling to national, multi-sector EPC level is constrained by complex data integration, proprietary systems, and advanced risk management capabilities; Kiewit operates with about 28,000 employees and nationwide project controls that raise the bar for entrants.
High capital and surety needs—bonding and working capital often in the $100M–$1B+ range—create steep financial barriers for new entrants in 2024.
Regulatory, safety and QA prequalification (typical 3-year safety record, EMR ≤1.0) plus 2–5 years to build credibility further deter newcomers.
Incumbent scale (≈28,000 employees), preferred-sub networks and proprietary systems make national multi-sector entry low.
| Metric | Value (2024) |
|---|---|
| Employees | ≈28,000 |
| Typical bonding/capital | $100M–$1B+ |
| Prequal safety | 3 yrs / EMR ≤1.0 |


