
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
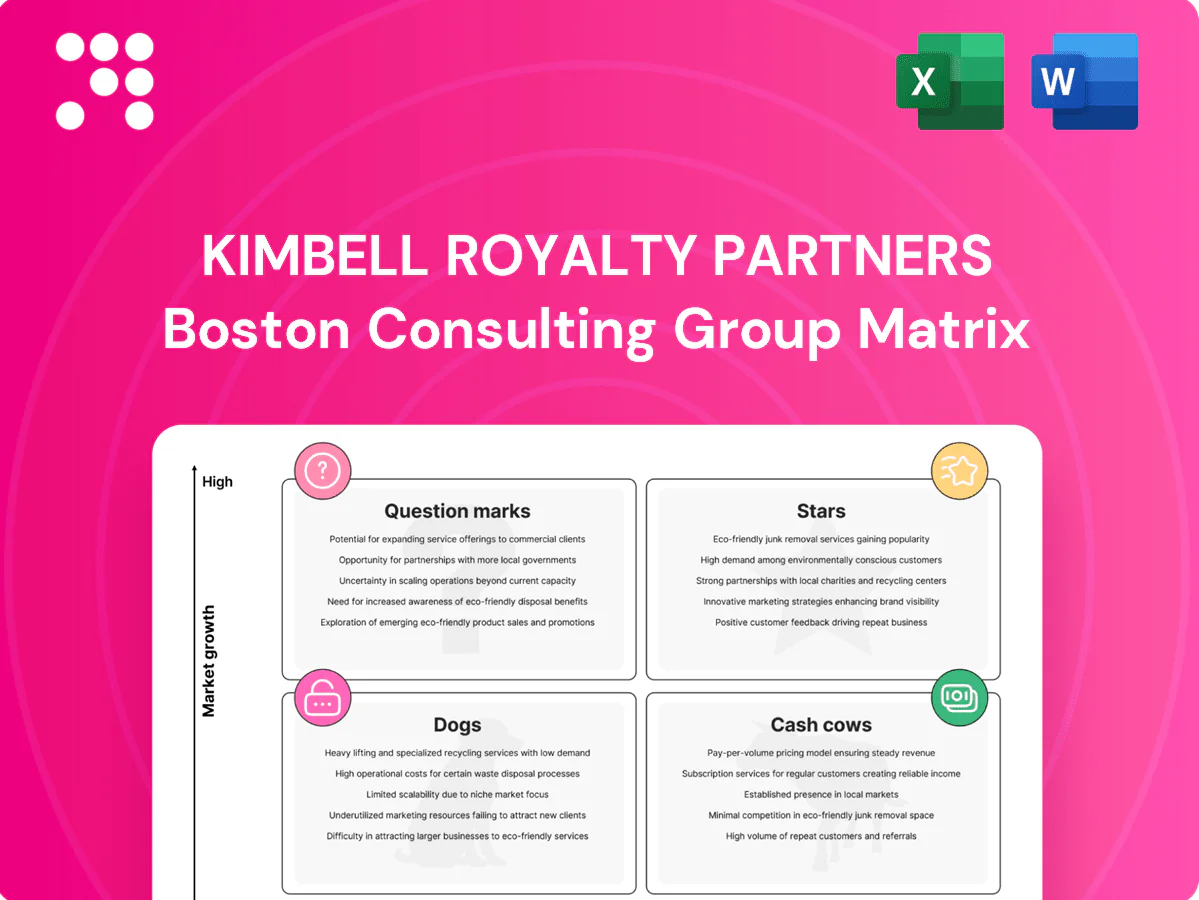
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Quick snapshot: Kimbell Royalty Partners’ BCG Matrix teases which assets are pulling market weight and which are costing you cash — but the preview’s just the appetizer. Buy the full BCG Matrix to get quadrant-by-quadrant placements, data-backed recommendations, and a ready-to-use Word report plus a high-level Excel summary. Skip the guesswork and get strategic clarity you can act on today.
Top-tier shale basin royalties occupy high-growth Permian and Delaware tracts with dense rig activity (Permian ~330 rigs, Baker Hughes 2024) and deep inventory that sustains rising royalty checks as new wells come online. Decline from legacy wells is offset by fresh drilling, helping these tracts act as growing cash engines. They require ongoing land buys, data investment and operator engagement to protect and grow share. Keep feeding them to mature cash flows.
Oil-weighted positions in premium hubs amplify cash generation when oil prices rally, as operators prioritize liquids benches and sustain pad development, keeping volumes climbing. Kimbell benefits from minimal marketing costs on royalty interests but needs disciplined reinvestment to acquire adjacent cores that preserve and grow per-well cash flow. Maintain market share and let compounding of royalty cash flows drive long-term value.
When top-tier E&Ps control the drillbit, cycle times shorten and well results are repeatable, turning mineral checks into a reliable growth stream; in 2024 Kimbell Royalty Partners leaned into these dynamics across core basins. Kimbell does not fund capex, so management should double down on adjacent royalty and mineral acquisitions to capture outsized upside from operator-led efficiency. The runway lies in concentrated acreage positions operated by high-performing E&Ps.
Kimbell's royalty interests tied to ready-to-complete (DUC) inventory convert into cash quickly as operator completion activity accelerates; completions boost royalty revenue with no capex burden to Kimbell. As completions hit, topline spikes while margin stays high, but growth depends on operator schedules and offset unit changes, requiring active monitoring to retain acreage share. Industry DUC inventories declined through 2024, supporting near-term completion-driven cash flow.
Stacked-pay, contiguous blocks multiply multi-zone potential within the same tract, compounding well density and EURs as pads and infill follow. Contiguity raises the probability of repeat development by the same operator, shortening development cycles and lowering per-well costs. Current cash flows are redeployed into acreage and drilling — cash in equals cash out while growth consumes free cash; stay funded to capture future Cash Cows.
Top-tier Permian/Delaware royalties sit in high-growth pads (Permian ~330 rigs, Baker Hughes 2024) driving rising checks as new wells offset legacy decline. Oil-weighted hubs amplify upside on price rallies while Kimbell bears no capex, so reinvestment into adjacent mineral/royalty acreage is key. Monitor operator schedules and DUC conversion as 2024 DUC inventories declined, enabling near-term cash spikes.
| Metric | 2024 |
|---|---|
| Permian rigs (Baker Hughes) | ~330 |
| Capex burden | None (royalty) |
| DUC trend | Declined through 2024 |
 Detailed Word Document
BCG Matrix of Kimbell Royalty Partners: quadrant insights with clear guidance on which units to invest in, hold, or divest.

 Customizable Excel Spreadsheet
One-page BCG matrix that quickly spots winners and laggards—clean, export-ready for decks and C-level meetings.
Legacy PDP-heavy royalty base delivers steady cash in 2024 as mature wells exhibit predictable declines and minimal surprise risk, allowing largely maintenance-free cash flow. Little to no incremental capital is required to sustain checks, freeing distributable cash to fund acquisitions and cover overhead. Focus on milking gently while maintaining title cleanliness to protect long-term royalty receipts and deal optionality.
Fully developed units require no new drilling yet deliver attractive royalty revenue; Kimbell Royalty Partners trades on NYSE as KRP in 2024. Operating partners absorb capex and lifting costs while Kimbell books receipts, preserving cashflow. Margins remain high in a flat-growth profile; prioritize optimized collections and minimal admin friction to sustain returns.
Conventional fields with long tails deliver low single-digit decline rates (about 3–5% annually) and modest price sensitivity, producing predictable cash flows that drove Kimbell Royalty Partners to prioritize steady distributions in 2024. They won’t drive growth but reliably fund payouts and debt reduction. Use cash from these assets to pay down leverage and sustain distributions. Avoid heavy reinvestment—keep them humming.
Gas-weighted tracts with firm takeaway produce steady cash even with low growth: U.S. dry gas ran near 100 Bcf/d in 2024, and mature basins typically show single-digit annual decline so volumes hold. Price swings affect revenue, but contracted pipeline capacity limits basis risk and smooths cash flow, reducing portfolio volatility. Hedge exposure via product mix and short-term hedges, not incremental capex.
Leases with favorable royalty terms serve as Kimbell Royalty Partners' cash cows, where legacy contracts deliver outsized per-unit cashflows relative to their production decline; per Kimbell's 2024 public filings these legacy royalties continue to outperform nominal decline metrics. Minimal placement spend and disciplined administration keep operating capital low, while focused audits and title cleanup projects in 2024 lifted netbacks modestly. Quiet, high-margin cash generation from these contracts underpins free cashflow and distributions.
Legacy PDP-heavy royalties supply steady, maintenance-free cash in 2024, funding distributions and acquisitions with minimal capex. Mature wells show ~3–5% annual decline and limited surprise risk, while operator-paid capex preserves Kimbell Royalty Partners' margins. Focus remains on title/audit work to protect long-term receipts and optionality.
| Metric | 2024 Value |
|---|---|
| Decline rate | 3–5% ann. |
| US dry gas | ~100 Bcf/d |
| Ticker | KRP (NYSE) |
The file you're previewing is the exact Kimbell Royalty Partners BCG Matrix you'll receive after purchase. No watermarks, no placeholders—just a fully formatted, analysis-ready report tailored for clarity and decision-making. It’s the same downloadable document you'll edit, print, or present to stakeholders immediately after payment. Crafted by strategy pros, it arrives ready to plug into your planning without surprises.
Stranded acreage shows no rigs, no permits and no near-term plan—capital is effectively parked while parcels generate only minor admin and monitoring costs that still consume management time. Without a basin-wide catalyst the odds of turnaround are poor, so these assets are prime candidates to prune or package for exit to free up deployable capital.
Tiny fractional interests generate micro checks but carry the same back-office load, so unit economics typically do not pencil. Title curative and suspense-release work can cost more than the asset’s value, eroding returns. These assets rarely scale into meaningful cashflow or portfolio weight. Consider divestiture or batch sale to reduce admin overhead and improve portfolio efficiency.
Late-life, edge-of-play shale tails at Kimbell Royalty Partners produce small, rapidly fading cash flows—typical decline profiles run 50–80% in year one and often fall below ~50 boe/d within 2–3 years (2024 industry benchmarks). Without follow-on drilling they stagnate and consume operational oversight with little strategic upside. Best minimized or monetized while there is bid interest to capture remaining PV and free up capital for core assets.
Dogs: Regulatory-constrained parcels for Kimbell Royalty Partners NYSE: KRP in 2024 suffer permitting friction and surface-use restrictions that stall development timelines and defer or eliminate royalty cash flows.
Cash often trickles, if at all, volatility and unpredictability rise, and management time is diverted to issues outside Kimbell’s control, so keep exposure light.
Complex title or suspense-heavy interests in Kimbell Royalty Partners act as Dogs: revenue delayed by ownership disputes or messy records erodes asset value, while legal and land work chew into margins; even when cleared, meaningful growth is seldom realized, so trim positions where cleanup costs outweigh projected cash flows.
Stranded acreage shows no rigs or permits and yields negligible royalties; tiny fractional interests produce micro checks while back-office costs persist. Late-life shale tails decline 50–80% in year one and often fall below ~50 boe/d within 2–3 years (2024 benchmark), so prioritize pruning or batch exits.
| Issue | Impact | 2024 metric | Action |
|---|---|---|---|
| Regulatory delays | Deferred cash | Permits stalled | Minimize exposure |
| Late-life decline | Rapid cash fade | 50–80% Y1; <50 boe/d | Monetize/trim |
Rigs are moving into Kimbell tracts—Baker Hughes 2024 basin data showed rig activity up roughly 10% year-over-year in key plays—geology looks promising but Kimbell’s production share isn’t proven across parcels. These Question Marks can flip to Stars if results repeat across wells and EURs scale. They will need capital to acquire bolt-on minerals to build meaningful position. Invest selectively and move fast to capture optionality.
Thesis is solid but early: newly acquired packages sit without a visible operator schedule as of 2024, so near-term value hinges on operator program commitments.
Cash demands show up in diligence and integration rather than capex; if operators commit programs growth follows, if not the assets should be revalued and potentially divested.
Set clear milestones tied to operator schedules and commercial triggers, document dates and decision gates, and hold management to them.
Price-sensitive gas corridors: if Henry Hub firming from 2024 averages near $2.80/MMBtu triggers reactivation, Kimbell Royalty Partners interests can scale quickly as drilling pace returns; today share is low and returns thin given muted 2024 activity. Maintain optionality without overcommitting: buy calls to capture upside and sell if the narrow window closes.
Upside hinges on operator technology and economics, not Kimbell spend; successful refrac/secondary pilots can boost volumes on existing sunk infrastructure, with industry refrac uplifts commonly cited at 15–30% (Rystad Energy 2024). If pilots miss targets, assets trend toward Dog territory. Monitor pilot EUR, IP30/IP90 and FCF; then decide to double down or dispose.
Federal or permitting-dependent tracts sit in high-growth basins (Gulf of Mexico, portions of the Permian) but approvals are policy-driven and often take 12–36 months; the upside can be substantial once approvals land, yet until then cash out (admin, compliance, lease maintenance) routinely exceeds cash in. Stage-gate investment discipline and readiness to pivot are essential to protect capital and capture upside when permits clear.
Rigs up ~10% YoY in key plays (Baker Hughes 2024) but Kimbell’s production share remains low; success depends on repeatable EURs and operator programs. Refrac pilots offer 15–30% uplift (Rystad 2024) — if pilots hit IP30/IP90 targets, flip to Star; if not, revalue and consider sale. Permitting timelines 12–36 months; maintain stage-gate capital, buy optionality not full exposure.
| Metric | 2024 | Decision Trigger |
|---|---|---|
| Rig activity | +10% YoY | Operator schedule |
| Refrac uplift | 15–30% | IP30/IP90, EUR |
| Henry Hub | $2.80/MMBtu | Drill reactivation |
| Permitting | 12–36 months | Permit receipts |


