
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
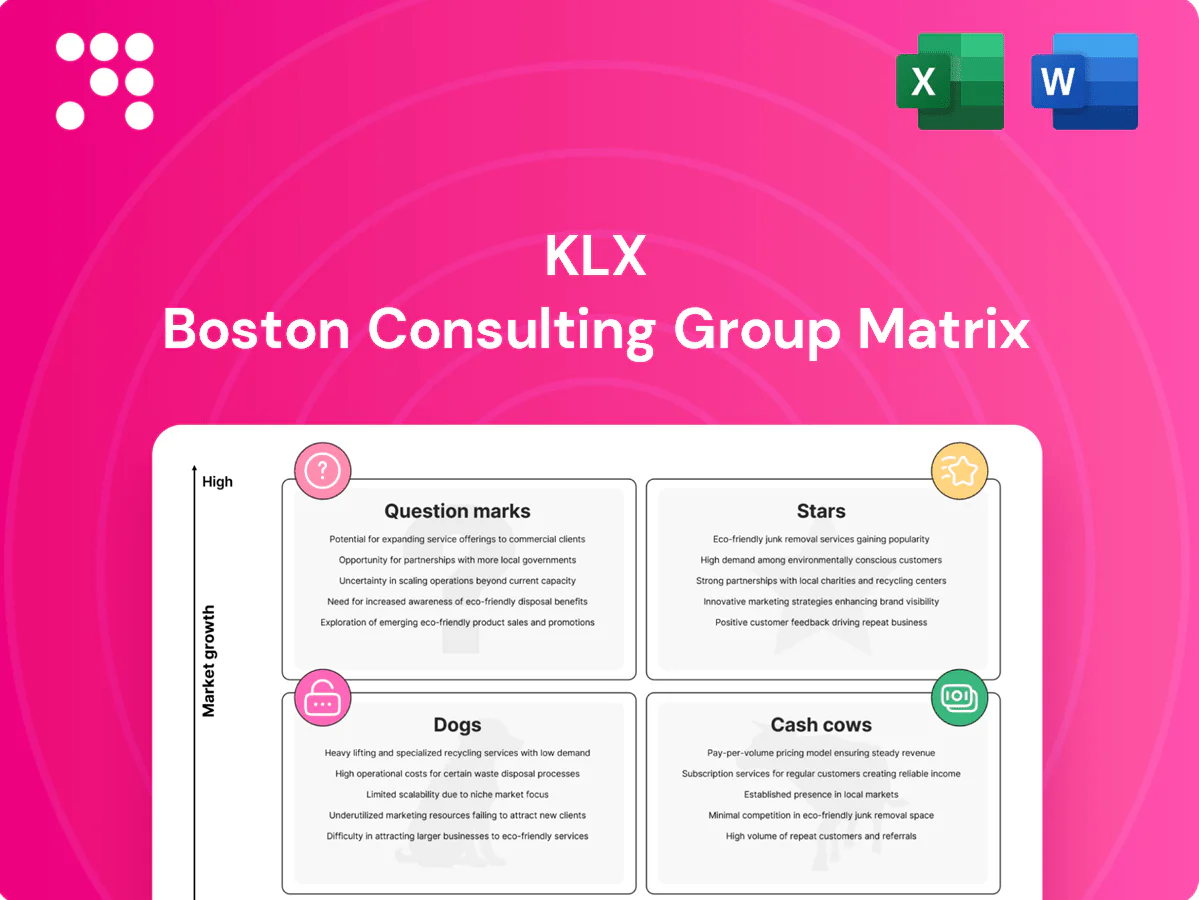
KLX's BCG Matrix snapshot shows where each product sits amid shifting demand — who’s a Star, who’s draining cash, and which Question Marks could be flipped. This preview teases quadrant positions and trends; the full report maps every product, backs placements with data, and lays out prioritized, actionable moves. Purchase the complete BCG Matrix to get Word and Excel deliverables, targeted recommendations, and a ready-to-present roadmap for smarter capital allocation.
Wireline perforating sits high in KLXs BCG matrix thanks to consistent stage counts (commonly 30–40 stages) and sticky operator rosters, with safety and performance KPIs driving repeat business. The market is expanding as lateral lengths approach ~10,000 ft and completion intensity rises, soaking up capex for guns, trucks and crews while revenue converts rapidly. Retaining share supports strong cash generation as the segment matures into a steady cash cow.
Downhole tools for completions sit in KLX’s Stars quadrant as high-velocity consumables and rental tools ride the completions wave in 2024. KLX’s engineered portfolio and on-site field support win bids and keep churn low, driving brisk unit growth. Inventory and logistics intensity push working capital higher, but margins justify the investment while the cycle remains hot.
Frac-support services integration bundles wireline, CT, and downhole tools on‑pad, boosting KLX share and reducing NPT; industry adoption rose through 2024 as operators favor a single accountable vendor. The segment is growthy and resource‑heavy now—Baker Hughes US rig count averaged ~600 in 2024, underpinning sustained activity—and KLX should double down to cement leadership before rivals replicate the model.
Complex high-intensity wells need reliable, rapid intervention; KLX’s integrated packages—pressure control, tools, and dedicated crews—own mindshare on the hardest jobs and shorten downtime. Growth remains strong in 2024 and operations are capital hungry, so KLX should invest to lock multi-year contracts and raise switching costs through equipment pools and service-level guarantees. This strategy secures recurring revenue and premium pricing.
KLX Stars (Permian CT, wireline perforating, downhole tools, frac‑support) drive rapid revenue and require high working capital; 2024 tailwinds include Permian output ~5.6M bbl/d and Baker Hughes US rig count ~600. Stage counts ~30–40 and laterals ~10,000 ft lift consumable demand; action: reinvest to lock share and convert Stars into cash cows.
| Segment | 2024 Growth | Capex/WC | Priority |
|---|---|---|---|
| CT/Wireline/Tools/Frac | High | High | Accelerate investment |
 Detailed Word Document
Comprehensive KLX BCG Matrix review identifying Stars, Cash Cows, Question Marks and Dogs with strategic investment recommendations.

 Customizable Excel Spreadsheet
One-page KLX BCG Matrix that flags underperformers and growth bets—decisions become fast, focused, and presentation-ready.
Routine production interventions in mature basins deliver predictable tickets and high asset turns; KLX leverages established routes, crews, and SOPs to sustain margins. In 2024 upstream activity stayed steady, with US onshore rig counts near 600 and cash conversion for top service players often above 40%. Growth is modest—focus on maintenance, dispatch optimization, and quietly milking cash flow.
Pressure control rentals sit as a cash cow with established inventory and steady utilization around 80–85% across 2024 operations, driving predictable revenue. The business differentiates on reliability and safety rather than bells and whistles, supporting a high uptime target and extended maintenance cycles. Low market growth (~1–3% CAGR) and minimal marketing spend (<1% of revenue) preserve cash flow. Reported EBITDA margins remain solid at roughly 30–40%.
Standard wireline logging & maintenance serves legacy customers with high repeat-work rates and proven workflows; the global well logging market exceeded $6 billion in 2024, underpinning durable volumes. Pricing power is steady rather than flashy, so margins are stable while volumes drive cash. Minimal incremental capex is needed to sustain operations. Protect service quality and let the cash flow.
Thru-tubing tool rentals are high-margin, well-understood SKUs with steady pull-through; turn times and field support drive renewal and kept unit utilization stable in 2024 despite flat market demand. Growth is flat but returns are consistent, supporting predictable cash generation and funding of other segments. Focus on inventory discipline and cross-sell to capture incremental margin uplift.
Field service contracts in mature basins are KLX cash cows: longstanding MSAs with predictable schedules and low churn deliver stable 2024 cash flows; operational excellence and a strong safety record create a durable moat. Little promo or capex is required—maintain SLAs, defend price, harvest cash.
Routine mature-basin services generate predictable high-turn cash flow; 2024 US onshore rig counts ~600 and leading service cash conversion >40%. Pressure-control rentals (utilization 80–85%) and wireline/logging (global market >6B USD) delivered ~30–40% EBITDA margins in 2024. Minimal incremental capex; focus on inventory, SLAs and cross-sell to harvest cash.
| Segment | Util% | 2024 EBITDA | Growth | Priority |
|---|---|---|---|---|
| Pressure control | 80–85% | 30–40% | 1–3% CAGR | Inventory, uptime |
| Wireline/logging | ~75–80% | ~30% | flat | Service quality |
| Field services | High | 30–40% | stable | Protect SLAs |
The file you're previewing here is the exact KLX BCG Matrix report you'll receive after purchase—no placeholders, no watermarks, no demo comments. It's fully formatted and ready to drop into your planning session or client deck. Once you buy, the final file is instantly downloadable and editable, so you can tweak assumptions or print on the spot. Crafted by strategy pros, it’s built for clarity and quick decision-making.
Non-core micro-markets are small basins with thin rig counts, often below 10 rigs, and sporadic work leading to equipment utilization under 20%. KLX holds low share, typically under 5%, so no scale economics and margins compress. Cash is tied up in idle equipment and parts, straining working capital. Best move: exit or consolidate these micro-markets to redeploy capital.
Old CT units, wireline trucks, and pressure-control pods in KLX’s Dogs cluster often run <30% of available hours, sit idle more than they operate, and require maintenance spends that can exceed 20–30% of their book value annually. Each dispatch erodes margins, with field-service margins turning negative on many runs (reported loss-per-dispatch commonly >$500–$1,500). Recommended actions: divest, cannibalize for parts, or scrap to stop cash bleed and redeploy capital.
In 2024 KLX one-off spot jobs face choppy demand and no relationship leverage, driving high logistics and mobilization costs that often consume margins. Pricing rarely covers travel and operational risk, with many jobs only breaking even on a good day. Recommend passing on standalone spots unless bundled with strategic, recurring work or long-term contracts to justify mobilization spend.
Commoditized tool SKUs in the Dogs quadrant face no differentiation and a race to the bottom on price, with market share typically low and many competitors; by 2024 median gross margins in commodity tool segments dropped below 15%, squeezing profitability and trapping working capital in slow-moving inventory with days inventory outstanding often 60+ days.
Legacy geographies show structural demand decline with key customers exiting; maintaining full footprints only burns overhead while market share remains low and contracting—recommend wind-down and redeploy assets to higher-growth regions.
Non-core micro-markets: utilization <20%, share <5% — exit or consolidate. Old CT/wireline: run <30% hours, maintenance 20–30% of book, loss-per-dispatch $500–$1,500 — divest/cannibalize. Commodity SKUs: median gross margin <15%, DIO 60+ days — cut or rebundle. Legacy geographies: structural decline, high overhead — wind down.
| Item | 2024 Metric | Action |
|---|---|---|
| Micro-markets | Util <20%, Share <5% | Exit/Consolidate |
| Old units | Run <30%, Maint 20–30% BV | Divest/Parts |
| Commodity SKUs | GM <15%, DIO 60+ | Cut/Rebundle |
| Legacy geogs | Demand ↓, customers exit | Wind down |
If KLX leans into frac crews the addressable market is tied to U.S. oil activity—U.S. crude production averaged about 13.3 million b/d in 2024 (EIA), underpinning strong service demand—but KLX’s share is early and small. Capex and multi-year crew buildouts are heavy, requiring clear anchor customers or exit. Management must decide fast: scale aggressively or divest.
Digital wellsite analytics is a Question Mark: demand for data-driven completions and interventions surged in 2024, with the digital oilfield analytics market ~USD 6.8bn and double-digit CAGR, yet KLX holds low share and nascent revenue from analytics. KLX’s ops data could become a durable moat if productized, enabling NPT reductions and service upsell. Invest to prove ROI on NPT reduction and bundle analytics across services to move toward Star.
Refrac and restoration programs are rising as operators mine existing inventory, driven by a US rig count near 680 in 2024 and demonstrated refrac uplifts of roughly 30–50% in many basins. The process is complex; early movers can capture premium share through proprietary workflows and data. KLX has pieces of the value chain but lacks dominance. Fund pilots, package integrated offerings, and chase multi-well programs to scale revenue.
CCS and geothermal well services sit in KLXs Question Marks quadrant: adjacent markets with strong policy tailwinds (US 45Q tax credit expansion and EU net-zero targets) and growing demand—global CCS capture ~40 MtCO2/yr and geothermal power ~15 GW in 2024.
KLX operational capabilities largely translate to these services but commercial credentials remain early, reflected in low revenue share and a steep learning curve for subsurface CO2 and high-temperature drilling.
Recommendation: pursue targeted lighthouse projects to validate technical fit, unlock references, and pivot investment toward scaling if pilot economics and utilization exceed 60%.
Operators demand fewer trips and smarter completions; dissolvable and smart downhole tools address this but KLX penetration remains single-digit, requiring targeted R&D and field trials to scale. Tech demand rose in 2024 across the sector, so back winners and partner where speed to market matters.
KLX Question Marks span frac crews, digital analytics, refrac/restoration, CCS/geothermal and smart downhole tools; 2024 anchors: US crude ~13.3m b/d, digital analytics ~USD6.8bn, rig count ~680, CCS ~40MtCO2/yr, geothermal ~15GW. KLX holds low share; priority: lighthouse pilots, prove NPT ROI, partner to scale or divest fast.
| Initiative | 2024 metric | Status | Priority |
|---|---|---|---|
| Frac crews | 13.3m b/d | early | anchor customers |
| Analytics | USD6.8bn | nascent | prove ROI |
| Refrac | rigs~680 | pilots | scale |
| CCS/Geoth. | 40Mt/15GW | capable | lighthouses |


