
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Lampogas SpA faces moderate supplier leverage due to specialized components, rising buyer price sensitivity, and a tightening regulatory environment that raises entry barriers; substitute energy technologies pose a growing threat while rivalry among incumbents remains intense. This brief snapshot only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore Lampogas SpA’s competitive dynamics, market pressures, and strategic advantages in detail.
LPG supply is concentrated among major producers—US, Qatar, Saudi Arabia and Russia—which together account for over 50% of seaborne LPG exports in 2024, giving upstream players pricing leverage. OPEC-linked crude moves and international benchmarks transmit volatility downstream, with periods in 2024 showing double-digit swings in regional LPG spot spreads. Lampogas must hedge and diversify sourcing; long-term offtake contracts lower price risk but constrain flexibility.
Access to import terminals, storage caverns, bottling plants and rail-truck capacity is limited, so suppliers owning key terminals or 3PL networks can command tighter commercial terms. Seasonal peaks — with demand spikes of roughly 30-40% for heating fuels — further tighten capacity and strengthen supplier leverage. Lampogas mitigates this by using multi-modal routes and regional storage hubs to improve negotiating leverage and reduce single-point dependency.
Propane/butane mix requirements and EN 589 odorant standards (still enforced in 2024 for EU transport fuels) plus cylinder and bulk compatibility rules narrow Lampogas SpA acceptable sources, concentrating supply and raising supplier pricing power. Fewer qualified vendors boost dependency and margin risk. Mandatory audits and ISO-style certifications create switching friction. Targeted supplier development programs can expand the qualified pool over time.
International LPG is dollar-priced in 2024, exposing Lampogas to FX risk as local currency moves feed through costs; suppliers historically pass through cost spikes rapidly, compressing margins when Lampogas lacks robust hedging. Indexed supply contracts with collars can rebalance negotiating power and stabilize gross margin volatility.
Multiple European hubs and traders provide alternative sourcing optionality for Lampogas SpA, with spot cargoes and term contracts typically split across portfolios; spot LNG made up about 35% of global LNG trade in 2023, supporting flexibility. Tight winter markets can sharply curtail optionality—2022 TTF spikes (~€340/MWh peak) showed suppliers’ abrupt pricing power. Regional competition for molecules can re-empower suppliers quickly during demand surges.
Supplier concentration >50% and seasonal 30-40% spikes squeeze margins; multi-hub hedges help
Suppliers hold strong leverage: US, Qatar, Saudi and Russia accounted for >50% of seaborne LPG exports in 2024, and USD pricing plus rapid pass-through compress Lampogas margins during spikes (seasonal demand rises ~30–40%). Multi-hub trading and indexed collars are key mitigants to supplier power.
| Metric | 2024 |
|---|---|
| Top-exporters share | >50% |
| Seasonal demand spike | 30–40% |
| Spot share (trading) | ~35% |
 Detailed Word Document
Tailored exclusively for Lampogas SpA, this Porter's Five Forces analysis uncovers key drivers of competition, supplier and buyer power, substitutes and entry barriers, and identifies disruptive threats affecting pricing, profitability and market share.

 Customizable Excel Spreadsheet
A concise one-sheet Porter's Five Forces for Lampogas SpA—visualizes supplier/customer power, competitive rivalry, substitutes and entry threats to speed strategic decisions and relieve analysis bottlenecks.
Residential LPG users are numerous and dispersed—≈25.6 million households in Italy (2024 est.)—so individual bargaining power versus Lampogas SpA remains limited. Switching costs tied to tanks, regulators and mandatory safety inspections raise customer stickiness. Price transparency and spot LPG volatility in peak winter compress margins. Reliable delivery and 24/7 emergency support enable Lampogas to command modest premiums.
SME and industrial contract buyers exert strong bargaining power by purchasing larger volumes and negotiating tougher terms, often running formal tenders and demanding indexed pricing and strict service-level guarantees. Multi-year contracts reduce churn for Lampogas SpA but typically compress unit margins as buyers secure volume discounts. Offering value-added services such as technical support, logistics optimization, or bundled maintenance shifts negotiations away from pure price competition and helps protect margins.
Automotive LPG buyers are highly price-sensitive amid tight retail margins, with Italian autogas retail prices typically 20–30% below petrol in 2024, intensifying switching behavior. Volume concentration at flagship forecourts—top stations often deliver 30–40% of chain volumes—gives operators leverage in procurement. Demand is cyclical and tied to mobility trends and tourism seasonality, while co-investment in forecourt LPG infrastructure creates switching costs and long-term lock-in.
Buyers often view LPG as a commodity in 2024, intensifying price pressure, though Lampogas can differentiate via safety records, delivery reliability and enhanced customer support, shifting negotiation away from pure cost. Branding and digital ordering reduce apples-to-apples comparisons, and contract KPIs (eg service-level targets) move dialogue beyond price.
Some commercial buyers dual-source cylinders or bulk deliveries, reducing Lampogas SpA pricing power as multi-sourcing is common in industrial accounts; long regulatory tank inspections and ownership records add switching friction. Buyback programs and integrated service bundles (installation, safety checks) lower churn by increasing sunk costs. Standard contract notice periods of 30–90 days and early-exit penalties further moderate buyer leverage.
Residential buyers (≈25.6M households in Italy, 2024) have limited individual leverage due to dispersion and switching frictions; SMEs/industrial purchasers wield strong bargaining power via tenders and volume discounts; automotive buyers are highly price-sensitive with autogas 20–30% cheaper than petrol (2024), concentrating volumes at top forecourts (30–40%).
| Metric | 2024 |
|---|---|
| Households | 25.6M |
| Autogas vs petrol | -20–30% |
| Top forecourt share | 30–40% |
| Notice periods | 30–90 days |
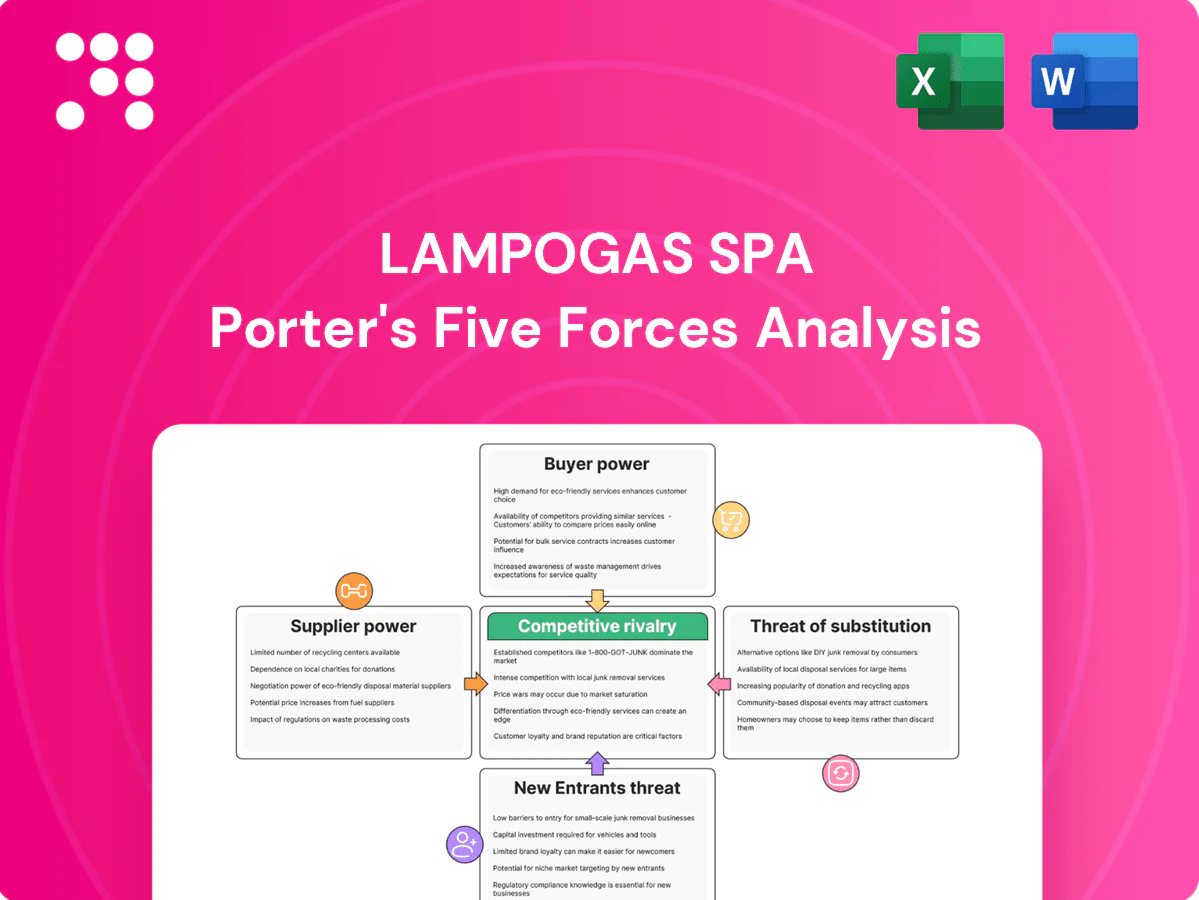
This preview shows the exact Lampogas SpA Porter’s Five Forces analysis you’ll receive immediately after purchase—fully formatted and ready to use. It contains a thorough assessment of competitive rivalry, supplier and buyer power, threat of substitutes, and barriers to entry. No placeholders or mockups—what you see is the final deliverable. Instant download upon payment.
Italy’s LPG market in 2024 features multiple national players (Liquigas, ButanGas, Beyfin) alongside over 200 regional distributors and cooperatives, intensifying local price competition. Market fragmentation drives margin pressure as route density and depot proximity confer transport-cost advantages to dense networks. Lampogas’s broad depot and delivery footprint is therefore a key barrier to share erosion, enabling tighter route optimization and faster replenishment.
Cylinder exchange and small-bulk segments see frequent discounting and promotional campaigns, with deposit policies and short-term offers intensifying rivalry and customer churn. Firms with lean logistics and high asset utilization sustain lower prices longer, pressuring margins across the network. Providers that differentiate through rapid delivery, safety compliance and value-added services face less risk of a race to the bottom.
Compliance, emergency response, and installation quality drive buyer choice in LPG services, with many rivals emphasizing ISO 45001 and ISO 14001 certifications and 24/7 technical support. ILO estimates roughly 2.3 million work-related deaths annually, underscoring why superior safety culture reduces incidents and reputational risk. Lampogas can differentiate through targeted training programs and regular third-party audits to prove performance.
Rural and mountainous areas increase last-mile complexity, with 2024 industry estimates showing last-mile represents about 54% of total delivery costs and rural per-drop costs can be up to three times urban rates. Carriers with dense route networks achieve materially lower per-drop costs and margin resilience. Depot placement and routing/scheduling tech are decisive competitive weapons, and Lampogas’s widespread service points help defend difficult territories.
Ownership of customer tanks and long-term contracts raise exit barriers for rivals, as legal and safety checks delay transfers and decommissioning; competitors counter with free tank swaps or installations to win accounts. Lampogas can deploy lifecycle asset management and predictive maintenance to increase switching costs and extend customer lifetime value. Regulatory safety procedures and certification create natural frictions to rapid customer moves.
Italy’s 2024 LPG market has multiple national players plus over 200 regional distributors, driving intense local price competition and margin pressure. Last-mile logistics account for ~54% of delivery costs and rural per-drop costs can be up to 3x urban rates, favoring dense networks. Safety and certifications (ISO 45001/14001) materially reduce churn and reputational risk.
| Metric | Value (2024) |
|---|---|
| Regional distributors | >200 |
| Last-mile cost share | ~54% |
| Rural per-drop uplift | up to 3x |
| Work-related deaths (ILO) | ~2.3M |
Where the methane grid reaches—Italy’s network topping ~41,000 km in 2024 and covering roughly 70% of households—households and SMEs can switch from LPG; piped gas offers convenience and per-kWh costs typically 30–50% lower than bottled LPG. Ongoing municipal expansions steadily erode LPG pockets, forcing Lampogas to double down on off-grid strongholds and bundled services.
Air-source and ground-source heat pumps increasingly substitute LPG heating: EU heat pump sales rose ~30% in 2023, lowering residential LPG demand. Falling electricity carbon intensity (EU grid ~200 gCO2/kWh in 2023) plus grants and tax credits accelerate uptake. High upfront capex (€6–20k) and unsuitable building fabric slow conversion, while service bundles and hybrid LPG–heat pump systems delay customer churn.
In some markets biomass pellets and district heating—with the global wood pellet market at about 30 million tonnes in 2024—compete with LPG on unit heating cost, especially where district systems supply roughly 10–12% of heat demand in parts of Europe; fuel availability and home storage constraints limit pellet uptake, while evolving EU environmental rules (2024 updates on solid biomass sustainability) can favor or restrict biomass—Lampogas can respond by marketing cleaner LPG combustion and lower-installation-footprint solutions.
Industrial users can switch from LPG to LNG, diesel or electricity depending on process heat and retrofit costs; in 2024 seaborne LNG volumes neared 380 million tonnes, improving LNG availability and competitiveness.
Economics hinge on required temperatures and capex for burners and tanks; security of supply and price volatility drive industrial buyers toward longer LPG contracts.
EV growth threatens automotive LPG demand as global EV sales reached about 12 million in 2024, roughly 15% of new car sales, and policy incentives plus expanding low-emission zones accelerate fleet electrification. However, uneven public charging infrastructure and range gaps in peri-urban/rural areas keep autogas viable in many markets. Co-locating autogas with convenience, CNG or fast-charging can partially hedge demand erosion.
Substitutes materially erode LPG: Italy gas grid ~41,000 km (2024) covers ~70% households, and EU heat pump sales rose ~30% in 2023 reducing residential LPG demand. Biomass pellets (~30 Mt global 2024) and district heating compete regionally; LNG seaborne volumes ~380 Mt (2024) aid industrial switching. EVs (≈12M sales, ~15% new cars 2024) cut autogas but charging gaps keep niche demand.
| Substitute | 2024 metric |
|---|---|
| Methane grid (Italy) | ~41,000 km / 70% households |
| Heat pumps | +30% EU sales 2023 |
| LNG | ~380 Mt seaborne 2024 |
| EVs | ≈12M sales (~15%) 2024 |
Entrants must invest in storage, bottling lines, cylinders, tanks, trucks and IT systems; a 2024 heavy-duty delivery truck costs ~€120,000 and a small bottling line typically requires multi‑million euro outlay, creating high upfront capex and maintenance burdens. Route density takes 3–5 years to build, and Lampogas’s installed base delivers scale and cost advantages that deter newcomers.
ADR rules and the Seveso Directive (2012/18/EU, still in force in 2024) impose strict transport, storage and inspection regimes that substantially raise compliance costs for LPG operators. Permitting for depots and tanks in Italy is lengthy and administratively heavy, delaying market entry. Safety culture, ISO/OHSAS certifications and incident-response systems are hard to replicate quickly. Incumbent technical know-how and site experience form a practical entry barrier.
Securing reliable LPG volumes and terminal slots is challenging because incumbents maintain long-term supply contracts and priority berthing, creating high entry barriers. New entrants relying on spot purchases face price and delivery volatility that can erode margins. Lampogas’s diversified sourcing and established terminal access further reduce opportunities for newcomers to secure stable volumes. This limits scalable market entry without significant capital or contract-backed supply.
LPG is a safety-critical service for homes and factories, so reputation, emergency response and technician quality determine customer trust. New brands face slow adoption without local references and certifications; Lampogas’s long service history and wide network raise switching hurdles. As of 2024 this brand-trust barrier remains the primary deterrent to new entrants.
Profitable LPG delivery depends on dense customer clusters and optimized routing; last-mile logistics can account for roughly 50% of delivery costs, so sparse volumes make new entry uneconomic. Entrants typically lack the volume to fill trucks efficiently, while incumbents' advanced scheduling and telemetry (2024 studies report 10–15% route-cost savings) widen the cost gap. Ownership of customer tanks creates durable lock-in, raising capital and scale barriers to entry.
High upfront capex (heavy truck ≈ €120,000; bottling line = multi‑€m) and 3–5 years to build route density create strong scale barriers. ADR/Seveso compliance and slow permitting raise fixed costs and delay entry. Incumbent supply contracts, terminal access and tank ownership limit scalable volumes; last‑mile can be ~50% of costs while telematics cuts route costs 10–15%.
| Metric | 2024 Value |
|---|---|
| Heavy truck | ≈ €120,000 |
| Bottling line | Multi‑€m |
| Route density build | 3–5 years |
| Last‑mile cost | ≈50% |
| Telematics savings | 10–15% |


