
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
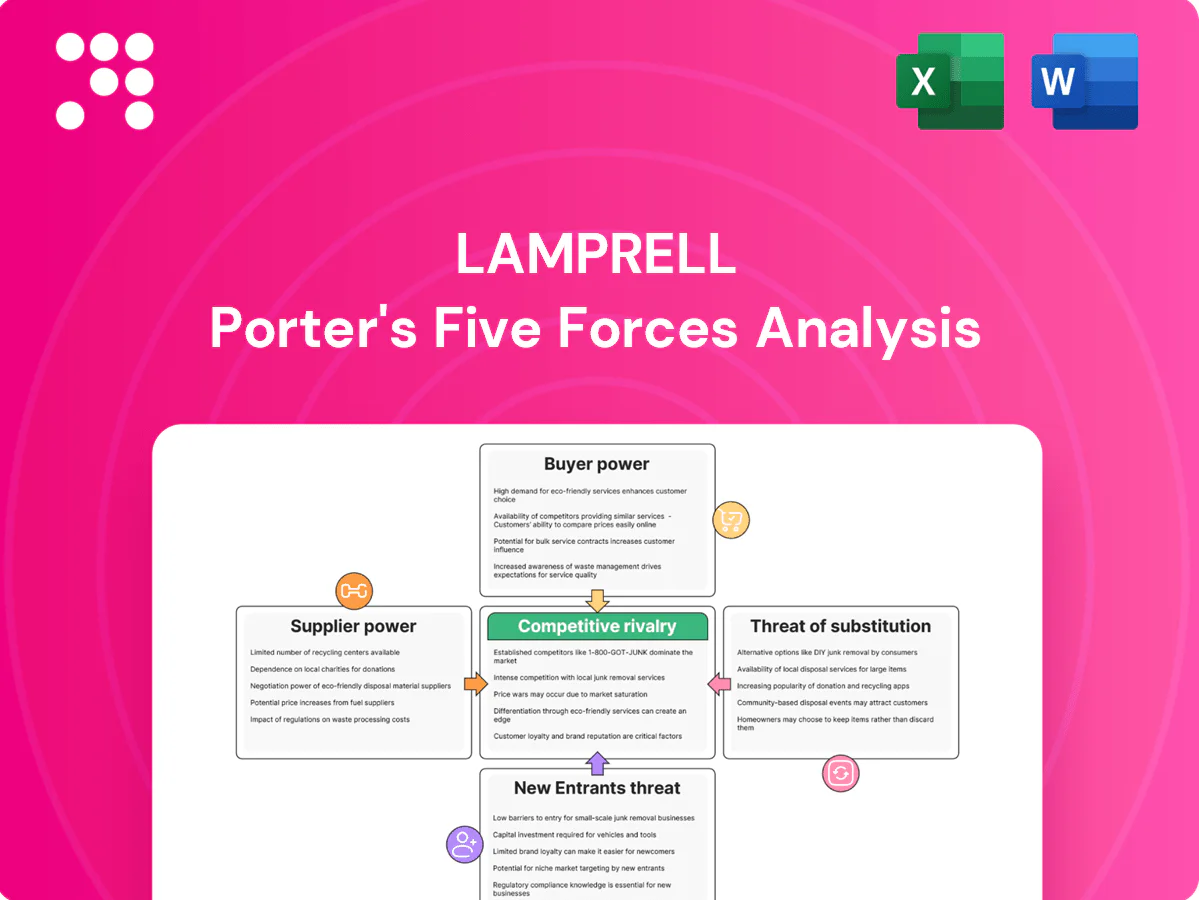
Lamprell's competitive landscape is shaped by the interplay of five key forces: the bargaining power of buyers and suppliers, the threat of new entrants and substitutes, and the intensity of rivalry. Understanding these dynamics is crucial for navigating the offshore, onshore, and oil & gas sectors.
This brief snapshot only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore Lamprell’s competitive dynamics, market pressures, and strategic advantages in detail.
Lamprell's reliance on a global supply chain for highly specialized steel, advanced welding materials, and complex electronic components for offshore rigs and wind farm foundations highlights a key area of supplier bargaining power. The limited pool of qualified suppliers for these critical items grants them significant leverage.
For instance, in 2024, the global market for specialized offshore steel experienced price volatility due to increased demand from energy infrastructure projects and supply chain constraints. This directly impacts Lamprell's project costs and timelines, as these specialized materials are not easily substituted.
The offshore energy fabrication sector, a key area for companies like Lamprell, is heavily reliant on a specialized workforce. This includes highly skilled engineers, certified welders, and project managers who possess the unique experience needed for intricate offshore projects. The demand for these professionals often outstrips the available supply, especially in critical geographical areas.
This scarcity of specialized talent directly translates into increased labor costs for fabrication companies. For instance, in 2024, reports indicated a significant global shortage of skilled trades, with some regions experiencing up to a 30% deficit in qualified welders for specialized industries. This situation amplifies the bargaining power of these skilled workers and the agencies that represent them, as they can command higher wages and better working conditions.
The construction and installation of critical offshore infrastructure, like wind turbine foundations and oil and gas jackets, are heavily reliant on specialized heavy lift and installation vessels. The availability of these large, complex vessels, including wind turbine installation vessels (WTIVs) and heavy lift vessels (HLVs), is currently constrained.
Building these ultra-large vessels is a significant undertaking, involving substantial capital investment and long manufacturing lead times. This scarcity directly translates into considerable bargaining power for the owners of these vessels. For companies like Lamprell, this can mean increased charter rates and potential project timelines being extended due to vessel scheduling.
For instance, the global fleet of WTIVs, crucial for offshore wind, has seen limited expansion. As of early 2024, the number of WTIVs capable of installing the latest generation of larger turbines remains a bottleneck. This limited supply, coupled with growing demand from the burgeoning offshore wind sector, allows vessel owners to command premium pricing and favorable contract terms, impacting the cost structure for installation projects.
Suppliers offering proprietary technologies, like advanced drilling components or specialized fabrication software, wield substantial influence over Lamprell. The company often finds itself needing to license these critical technologies or acquire unique equipment where few substitutes exist.
This reliance can translate into elevated costs and a dependency on a limited number of essential technology providers, potentially hindering Lamprell's operational efficiency and flexibility. For instance, in 2024, the global market for specialized oil and gas fabrication equipment saw prices increase by an average of 8% due to supply chain constraints and the proprietary nature of advanced manufacturing tools.
The bargaining power of suppliers in logistics and transportation services is significant for Lamprell, given the sheer scale and global reach of its projects. Moving enormous fabricated components efficiently is paramount, and any disruptions or cost escalations in shipping can directly impact project timelines and profitability. For instance, the offshore wind sector in Europe has recently grappled with significant supply chain challenges, underscoring the critical role and leverage held by logistics providers.
Securing timely and cost-effective shipping, particularly for international endeavors, presents a considerable challenge. This dependency grants logistics and transportation service providers substantial leverage. In 2024, the global freight market experienced volatility, with shipping rates fluctuating due to geopolitical events and demand shifts, directly affecting companies like Lamprell that rely heavily on these services.
Suppliers of specialized materials, skilled labor, and essential heavy-lift vessels hold considerable sway over Lamprell. This leverage stems from the limited availability of these critical inputs and the high demand within the offshore energy and wind sectors. For example, in 2024, the scarcity of qualified welders for offshore projects led to wage increases of up to 30% in some regions, directly impacting fabrication costs.
Proprietary technologies and specialized logistics providers also exert significant bargaining power. Lamprell's reliance on unique fabrication software and global shipping services means that cost fluctuations and availability issues with these suppliers can directly affect project timelines and profitability. The global freight market in 2024 saw rates fluctuate significantly, impacting companies like Lamprell.
| Supplier Type | Key Factors Influencing Bargaining Power | Example Impact on Lamprell (2024 Data) |
| Specialized Steel & Materials | Limited pool of qualified suppliers, supply chain constraints | Price volatility affecting project costs |
| Skilled Labor (Welders, Engineers) | Global shortage of trades, high demand | Up to 30% wage increases in some regions, increased labor costs |
| Heavy-Lift & Installation Vessels | Limited fleet expansion, high demand from offshore wind | Increased charter rates, potential project timeline extensions |
| Proprietary Technologies | Few substitutes for advanced components or software | 8% average price increase for specialized fabrication equipment |
| Logistics & Transportation | Need for specialized, global shipping of large components | Fluctuating freight rates impacting project expenses and schedules |
 Detailed Word Document
Uncovers the five key forces shaping Lamprell's competitive environment, from supplier power to the threat of new entrants, providing a strategic roadmap for navigating the industry.

 Customizable Excel Spreadsheet
Instantly identify and prioritize competitive threats with a visual breakdown of all five forces, enabling focused strategic action.
Lamprell's primary clients are major international and national oil companies, such as Aramco and ADNOC, alongside prominent renewable energy developers like RWE. These entities are financially robust and possess extensive experience in managing intricate projects, allowing them to wield significant influence over pricing and project specifications.
The sheer scale of these clients, coupled with their strategic importance within the energy sector, grants them considerable leverage. This means they can effectively negotiate favorable terms, push for competitive pricing, and dictate delivery timelines, thereby increasing the bargaining power of customers in Lamprell's market.
Customers often engage Lamprell on a project-by-project basis, frequently utilizing competitive bidding for substantial EPCI contracts. This approach enables them to evaluate various suppliers and secure advantageous conditions for each undertaking, directly impacting Lamprell's pricing flexibility.
The ease with which clients can select different contractors for subsequent projects significantly amplifies their bargaining leverage. For instance, in 2024, the offshore wind sector, a key market for Lamprell, saw continued intense competition among project developers, leading to pressure on service providers to offer competitive bids and flexible contract terms.
While individual projects grant customers negotiation leverage, many also enter into long-term agreements (LTAs) and strategic partnerships. For instance, Lamprell has maintained an extended LTA with Aramco and a framework agreement with ADNOC. These arrangements secure a steady revenue stream for Lamprell but can also fix terms that benefit the customer for years.
The strategic value of these deep relationships might compel Lamprell to make concessions to preserve them. This can significantly influence pricing and contract conditions, effectively reducing Lamprell's pricing power.
Customers with significant internal engineering and fabrication capabilities can exert considerable bargaining power. For example, major energy firms often maintain in-house expertise or robust partnerships with multiple contractors. This allows them to directly compare Lamprell's service costs and performance against internal benchmarks or alternative suppliers, leading to more aggressive price negotiations.
This internal capacity or diversified contractor network enables customers to reduce their dependence on any single provider like Lamprell. Consequently, they are in a stronger position to demand better terms, potentially impacting Lamprell's pricing and margins. In 2024, the global energy sector saw continued consolidation and strategic partnerships, further bolstering the capabilities of large client organizations.
Lamprell's customers, often large international energy companies, possess significant bargaining power due to their global operations and extensive supplier networks. In 2024, major oil and gas clients continued to diversify their fabrication partners, reducing reliance on any single entity.
This ability to source components and services from multiple fabricators worldwide, particularly for standardized offshore modules and structures, directly enhances customer leverage. For instance, a significant portion of offshore wind farm construction in 2024 involved multiple fabrication yards, allowing clients to play suppliers against each other.
Lamprell's customers, primarily major international oil companies and renewable energy developers, wield substantial bargaining power. Their financial strength, project scale, and experience allow them to dictate terms, push for competitive pricing, and influence project specifications, as seen in the intense bidding for offshore wind contracts in 2024.
The ability of these clients to engage in competitive bidding for EPCI contracts and easily switch between contractors for different projects significantly amplifies their leverage. This dynamic limits Lamprell's pricing flexibility and necessitates favorable contract conditions to secure business.
Furthermore, customers possessing in-house capabilities or maintaining relationships with multiple fabricators can benchmark Lamprell's services, leading to more aggressive price negotiations and reduced dependence on any single provider.
The strategic value of long-term agreements, while securing revenue, can also lock in terms that benefit customers for extended periods, potentially influencing Lamprell's pricing power.
| Customer Type | Key Leverage Factors | Impact on Lamprell |
|---|---|---|
| Major Oil & Gas Companies (e.g., Aramco, ADNOC) | Financial robustness, large project scale, long-term agreements (LTAs), in-house capabilities | Strong price negotiation, ability to dictate specifications and timelines |
| Renewable Energy Developers (e.g., RWE) | Project diversification, competitive bidding processes, global sourcing networks | Pressure on pricing due to competition among fabricators, flexibility in contract terms |
| General Customer Base | Ease of switching contractors, benchmarking against alternatives, project-specific negotiations | Reduced pricing power for Lamprell, need for competitive bids |
This preview showcases the complete Lamprell Porter's Five Forces Analysis, offering an in-depth examination of competitive forces within the industry. You're viewing the exact, professionally formatted document you'll receive immediately upon purchase, ensuring no hidden surprises or placeholder content. This comprehensive analysis is ready for your immediate use, providing valuable strategic insights without any additional setup.
The offshore fabrication and rig construction sector demands substantial capital investment in advanced fabrication yards, heavy lifting equipment, and specialized tooling. This high barrier to entry naturally limits the number of competitors. For instance, major offshore engineering and construction firms often operate facilities costing hundreds of millions of dollars, making it difficult for new entrants to challenge established players.
This significant capital intensity fosters intense rivalry among existing companies, such as Lamprell, as they strive to secure projects to cover their high fixed costs and maintain operational efficiency. In 2024, the utilization rates for many offshore yards remained a critical factor, with companies actively bidding on contracts to ensure their expensive assets are put to productive use, often leading to aggressive pricing strategies.
Lamprell operates in a highly competitive landscape, facing a diverse array of players. This includes major global engineering and construction conglomerates, as well as more localized fabrication companies and niche rig builders.
Key competitors identified within the sector include Proserv, Ecolab, Blade Energy Partners, W-Industries, Motive Offshore Group, Dycom Industries, Saulsbury Industries, NMDC Energy (NPCC), Keppel, Aker Solutions, ConocoPhillips, and Drydocks World - Dubai. This broad spectrum of rivals signifies a crowded market.
The sheer number of capable competitors, many possessing greater financial scale or more extensive service portfolios than Lamprell, significantly amplifies the intensity of market rivalry. For instance, in 2024, the global offshore oil and gas construction market saw major players like Keppel Offshore & Marine and Sembcorp Marine (now Seatrium) continue to consolidate their positions, often leveraging larger asset bases and established international client relationships.
Competitive rivalry within Lamprell's operating environment is significantly shaped by the market's outlook for offshore oil and gas alongside renewable energy projects. The demand for jack-up rigs is projected to see growth, and the expansion of offshore wind development is a positive indicator.
However, the intensity of competition can spike during periods of project delays or when supply chain constraints emerge, forcing companies to vie aggressively for available contracts. Lamprell's substantial project pipeline across both these sectors underscores the dynamic, yet highly competitive, nature of the market.
Companies in the offshore energy construction sector actively seek to stand out by highlighting their specialized expertise, robust safety performance, advanced technological adoption like automation in fabrication, and superior project execution. Lamprell, for instance, promotes its Engineering, Procurement, Construction, and Installation (EPCI) strengths, its capabilities in rig refurbishment, and its new serial production line for offshore wind components.
While effective differentiation can lessen the pressure of direct price wars, a significant portion of the services offered in this industry remains largely commoditized, meaning competitors can easily replicate offerings.
Once a contractor like Lamprell is chosen for a complex project, switching becomes a costly affair. The intricate integration of specialized equipment, project-specific designs, and the risk of significant delays and cost overruns deter customers from changing mid-stream. For instance, in the offshore wind sector, a project might involve custom-built turbines and foundations, making a switch incredibly disruptive.
However, the ease with which customers can select new contractors for future projects keeps the competitive pressure on. Factors like past performance, pricing competitiveness, and a contractor's reputation for reliability heavily influence these decisions. In 2024, the energy infrastructure sector saw a strong emphasis on project execution track record, with clients actively reviewing contractor capabilities before committing to new builds.
To mitigate the impact of switching costs and foster long-term relationships, companies often enter into framework agreements. These agreements can streamline future project onboarding and potentially offer better terms, thereby reducing the perceived cost and effort for both the client and the contractor to continue their partnership.
The offshore fabrication and rig construction sector is characterized by fierce competition among a diverse range of players, from global conglomerates to niche builders. This rivalry is intensified by high capital requirements and the need to maintain high utilization rates for expensive assets, as seen in 2024 where companies actively pursued contracts to cover fixed costs.
Lamprell faces rivals like Keppel and Aker Solutions, who often leverage larger asset bases and established client relationships, particularly as the market sees growth in offshore wind and demand for jack-up rigs. Despite efforts to differentiate through expertise and technology, many core services remain commoditized, leading to price-based competition.
While high initial switching costs can lock in clients for complex projects, customer choice for future work maintains competitive pressure. Companies are increasingly using framework agreements to secure long-term partnerships and reduce client friction.
| Competitor Type | Examples | Competitive Factor |
|---|---|---|
| Global Engineering & Construction | Keppel, Aker Solutions | Scale, established relationships, asset base |
| Regional/Specialized Fabricators | Proserv, W-Industries | Niche expertise, agility |
| Rig Builders | Seatrium (formerly Sembcorp Marine) | Specialized rig construction capabilities |
Onshore oil and gas production, encompassing shale gas and conventional land-based operations, presents a significant threat of substitution for offshore extraction. As onshore extraction technologies continue to advance, they can attract capital that might otherwise be directed towards offshore projects, potentially dampening demand for offshore fabrication services. For instance, the US shale revolution has dramatically reshaped global energy markets, with onshore production becoming increasingly efficient and cost-effective.
Lamprell's involvement in land rig services offers a degree of diversification against this specific substitute threat. By providing services for onshore drilling, the company can leverage its expertise in a different segment of the energy market, mitigating some of the risks associated with a shift in investment away from offshore activities.
Onshore wind farms and solar power installations represent significant substitutes for offshore wind projects, directly impacting Lamprell's market. These alternatives often boast lower upfront capital costs and more straightforward installation processes, making them attractive to energy developers. For instance, the global installed capacity of solar PV reached over 1,300 GW by the end of 2023, demonstrating its rapid growth and accessibility.
The increasing cost-competitiveness of onshore renewables poses a threat to Lamprell's focus on offshore wind fabrication. As these alternatives become more economically viable and easier to deploy, they can divert investment and demand away from offshore wind. This trend could potentially curb the growth in demand for Lamprell's specialized services in the offshore wind sector.
Broader efforts towards energy efficiency and overall reduction in global energy demand can significantly impact the market for energy infrastructure. For instance, advancements in building insulation and smart home technology are projected to reduce global electricity demand growth by approximately 10% by 2030, according to the International Energy Agency (IEA) in their 2024 outlook. This trend directly substitutes the need for new energy supply projects, whether they are fossil fuel-based or renewable.
A decline in the overall need for new energy infrastructure would consequently reduce the market for Lamprell's core fabrication and contracting services. If global energy demand plateaus or decreases due to efficiency gains, the demand for new offshore wind platforms or oil and gas facilities, which Lamprell specializes in, would naturally shrink. This presents a clear threat as it diminishes the pipeline of potential projects for companies like Lamprell.
The increasing adoption of modularization and standardized designs within the offshore sector presents a significant threat of substitution for Lamprell. As the industry moves towards more off-the-shelf components and less bespoke engineering, the demand for highly customized fabrication services, a core Lamprell offering, could diminish. This trend suggests that alternative, more commoditized solutions could emerge as viable substitutes for Lamprell's specialized capabilities.
For instance, a rise in the availability of pre-fabricated, standardized modules from competitors or even new market entrants could directly compete with Lamprell's project-specific fabrication. This could lead to a situation where clients opt for these standardized options, thereby reducing the need for Lamprell's intricate engineering and assembly services. Such a shift would likely intensify price competition as standardized offerings typically carry lower production costs.
Advancements in energy storage, such as the growing capacity of lithium-ion batteries and the emerging potential of hydrogen storage, could lessen the demand for new large-scale offshore power generation projects. For instance, by mid-2024, global battery storage capacity was projected to reach over 150 GW, a significant increase from previous years, indicating a shift in how renewable energy is managed.
More efficient energy distribution networks, including smart grids and advanced transmission technologies, also present a threat. These improvements can optimize the use of existing power sources, potentially reducing the perceived need for additional offshore fabrication capacity. The International Energy Agency reported in 2024 that investments in grid modernization were accelerating worldwide.
While not direct replacements for Lamprell's fabrication services, these technological shifts could redirect capital investment by renewable energy clients. Instead of investing in new offshore generation infrastructure, clients might prioritize upgrades to storage and distribution systems, impacting Lamprell's order pipeline.
The threat of substitutes for Lamprell's services arises from alternative energy sources and technologies that reduce the need for traditional offshore oil, gas, and wind infrastructure. Onshore oil and gas production, particularly shale, offers a cost-effective alternative to offshore extraction, diverting capital and potentially reducing demand for offshore fabrication. Similarly, the rapid growth of onshore wind and solar power, often with lower upfront costs and simpler installation, directly competes with offshore wind projects. By the end of 2023, global solar PV capacity surpassed 1,300 GW, highlighting this competitive trend.
The offshore energy fabrication and construction sector demands substantial upfront capital. Newcomers face the daunting task of acquiring expensive shipyard facilities, specialized heavy-lifting equipment, and advanced manufacturing machinery. For instance, Lamprell’s ongoing investments in automated production lines, a key competitive advantage, further elevate the financial threshold for entry, making it incredibly challenging for new players to compete.
The offshore oil and gas construction sector, where Lamprell operates, demands highly specialized engineering, project management, and fabrication expertise for intricate offshore structures and rigs. Newcomers must either acquire or cultivate this deep technical knowledge, presenting a substantial barrier to entry.
For instance, a complex offshore platform project can involve thousands of engineering hours and require specialized welding techniques certified to stringent international standards. Lamprell's extensive portfolio, including projects like the recent delivery of the HE 750 jack-up rig in 2024, showcases their accumulated expertise and established track record, making it difficult for new, less experienced players to compete effectively.
The offshore energy sector is heavily regulated, demanding strict adherence to safety, environmental, and operational standards. New companies must navigate a complex web of certifications and international requirements, a process that is both time-consuming and expensive. For instance, in 2024, companies seeking to operate in the North Sea faced an average of 18 months for initial regulatory approval, with costs often exceeding $1 million for compliance documentation alone.
Lamprell's established customer relationships represent a significant barrier to new entrants. For instance, their long-standing partnerships with key energy giants such as Aramco, ADNOC, and RWE are built on years of trust and a consistent history of successful project execution. This deep-seated loyalty makes it incredibly difficult for newcomers to gain a foothold, as securing initial contracts with these major players requires a proven track record that new companies simply do not possess.
The threat of new entrants is therefore mitigated by Lamprell's strong reputation and existing client base. Newcomers would face immense challenges in replicating the level of trust and reliability that Lamprell has cultivated over decades. This is particularly true in the complex and high-stakes energy sector, where project failures can have severe financial and reputational consequences, making clients hesitant to switch to unproven entities.
Consider the implications for new market participants:
Existing players in the offshore and onshore wind construction sector, such as Lamprell, leverage significant economies of scale. This translates to lower per-unit costs in areas like raw material procurement, advanced fabrication techniques, and the management of large-scale projects. For instance, in 2024, major fabricators continued to invest in expanding their yard capacities, aiming to capture a larger share of the growing offshore wind market and further solidify their cost advantages.
New entrants face a substantial hurdle due to this scale and the accumulated experience curve. They would struggle to match the cost-efficiency of established firms, particularly when bidding for large, complex projects where upfront investment in specialized equipment and skilled labor is immense. This cost disadvantage acts as a powerful barrier, deterring many potential competitors from entering the market.
The threat of new entrants in the offshore fabrication sector is generally low due to immense capital requirements for specialized facilities and equipment, coupled with the need for deep technical expertise. Regulatory hurdles and established customer relationships further solidify the position of incumbents like Lamprell. For example, in 2024, the average cost for a new, certified offshore fabrication yard exceeded $500 million, a significant deterrent.
Economies of scale and the experience curve also present formidable barriers. New players struggle to match the cost-efficiency of established firms, particularly in bidding for large projects. This cost disadvantage, combined with the high capital investment for specialized facilities, makes market entry exceptionally challenging.
| Barrier Type | Description | Impact on New Entrants |
|---|---|---|
| Capital Requirements | High cost of shipyards, equipment, and machinery. | Very High - Prohibitive for most newcomers. |
| Technical Expertise | Need for specialized engineering and project management skills. | High - Requires significant investment in talent acquisition/development. |
| Regulatory Compliance | Navigating complex safety and environmental standards. | High - Time-consuming and costly certification processes. |
| Customer Relationships | Established trust and long-term contracts with major clients. | Very High - Difficult to displace incumbents. |
| Economies of Scale | Lower per-unit costs due to large-scale operations. | High - New entrants cannot match cost-efficiency. |


