
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
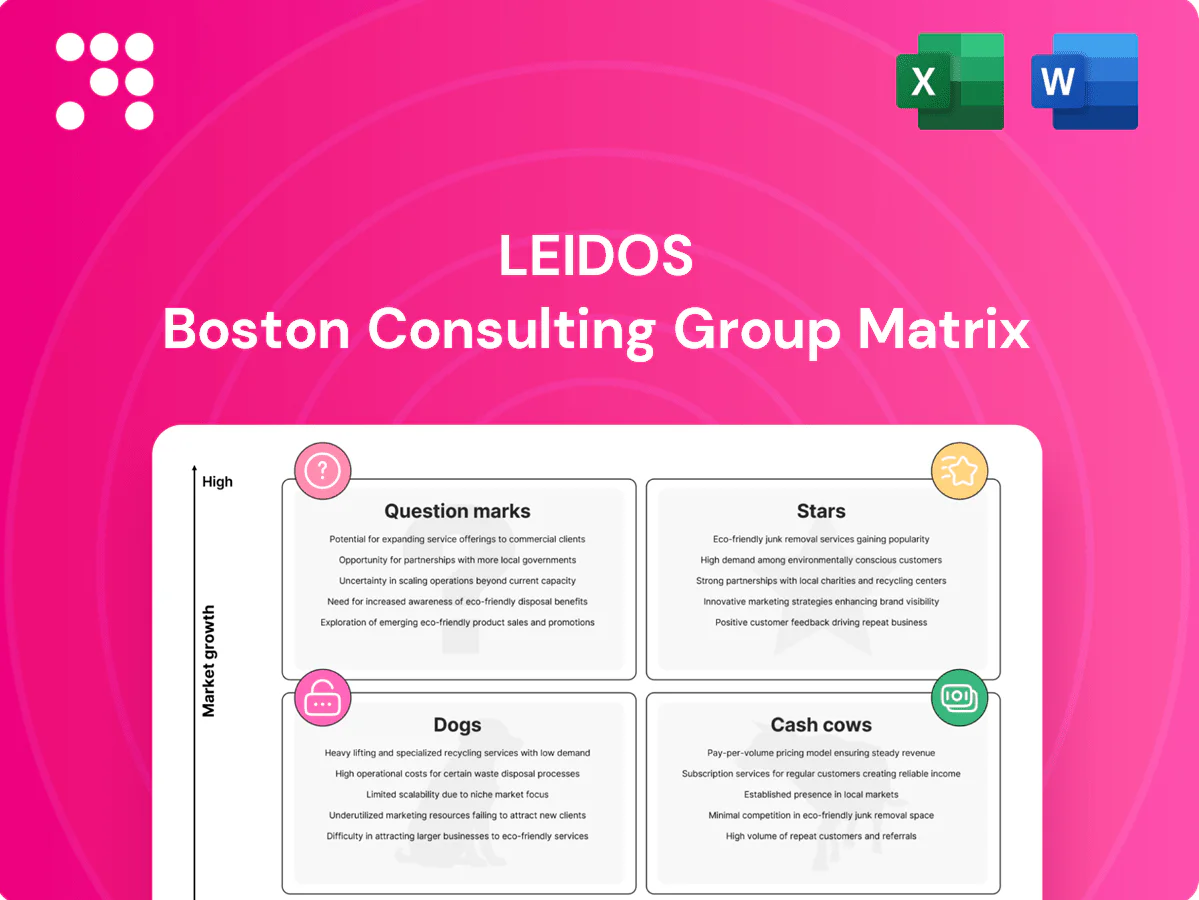
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Leidos’ products sit — Stars, Cash Cows, Dogs or Question Marks? This snapshot hints at positioning, but the full Leidos BCG Matrix delivers quadrant-by-quadrant clarity, data-backed recommendations, and a strategic roadmap you can act on. Buy the complete report for a polished Word analysis plus an editable Excel summary — skip the guesswork and get a ready-to-use tool for smarter investment and product decisions. Purchase now for instant access and clear, competitive direction.
Leidos Cybersecurity for Federal Missions is a Star: it sits on a high share across defense and intel as threats grow; Leidos reported $14.4B revenue in FY2024, with cyber a key growth driver. Programs lead but demand heavy investment in talent, tooling, and ATOs; keep the pedal down to mature into large annuity streams—classic cash-in, cash-out market moves fast.
Leidos sits in the ops loop with AI/ML analytics engineered for mission intelligence, leveraging FY2024 revenue of about $14.2B and positioning in a defense AI market growing ~13% CAGR (2024–2030). Leadership territory amid surging demand, but model ops and accreditation routinely cost millions per deployment, raising OPEX. Sustain wins and standardize platforms to transition to a Cash Cow as growth normalizes; invest aggressively while the market window remains open.
Digital Modernization for DoD Enterprises sits in Stars: large modernization waves and relentless demand for secure transformation drive high contract share; Leidos reported $15.8 billion in FY2024 revenue, underlining scale. Execution burns resources—cloud refactoring, zero-trust rollouts and DevSecOps pipelines consume program margins and talent. Strategy: hold share as the wave crests and lock in platform control so today’s wins become tomorrow’s foundation stones.
Mission Systems & ISR Integration are Stars: commanding positions in an expanding ISR market (global ISR CAGR ~6% to 2028) with Leidos reporting roughly $17.1B revenue in 2024; integration is capital- and talent-intensive so working-capital swings and program cash flow matter. Keep performance spotless to defend recompetes; sustained delivery can convert Stars into durable, high-margin Cows.
National security space and autonomy are ramping hard with the global space economy at about 469 billion in 2023 and the U.S. defense budget at roughly 858 billion for FY2024, placing Leidos well-positioned to capture growth in Stars.
Growth is rapid and competition fierce, with meaningful R&D outlays required; winning key references now sets standards, and if Leidos maintains share as markets mature the division’s cash profile can flip positive.
Leidos Stars (Cyber, AI/ML, Digital Modernization, ISR) hold high share in fast-growing defense/intel markets; FY2024 revenue approx 15.8B funds aggressive reinvestment. Heavy spend on talent, R&D and accreditations pressures OPEX but winning references and platform lock-in can convert Stars into Cash Cows.
| Segment | FY2024 rev | Growth | Key risk |
|---|---|---|---|
| Cyber/AI | approx 15.8B | ~13% CAGR | accreditation/OPEX |
 Detailed Word Document
BCG analysis of Leidos units with clear strategy: invest in Stars, harvest Cash Cows, reassess Question Marks, divest Dogs.

 Customizable Excel Spreadsheet
One-page Leidos BCG Matrix highlighting priorities and exit options—clear, C-level ready for fast decisions.
Long-cycle federal IDIQs and recompetes are cash cows for Leidos, underpinning a large share of backlog (>$18B at FY2024) with modest growth, solid margins and strong cash conversion. Focus on optimizing delivery, keeping CPARS scores high and driving efficient renewals to protect incumbency. Milk recurring cash flows while investing selectively to defend share and win recompetes.
Enterprise IT & Help Desk for civil agencies sits in a mature, sticky market with predictable volumes supporting Leidos’s stable IT services base; Leidos reported roughly $15.1B revenue in FY2024, with civil IT a consistent contributor. Upside is limited but generates dependable free cash flow; prioritize automation to widen margins, cut cost-to-serve and redeploy cash into higher-growth bets.
Health IT Program Operations are large, steady programs in EHR integration, claims, and analytics at scale—not hypergrowth but high renewal rates and a moat of operational know‑how; standardized playbooks can squeeze more efficiency and convert multi‑hundred‑million recurring contracts into reliable cash to fund innovation (Leidos reported roughly $1.6B operating cash flow in FY2024).
Systems Engineering & Integration Services is a core Leidos muscle with entrenched customer trust, representing a stabilizing business line amid the broader firm (Leidos reported roughly $14.5B revenue in 2024). The market is mature, competition known, and delivery repeatable, enabling margin expansion through reusable artifacts, tooling, and process repeatability. It reliably generates cash to backstop higher-risk growth initiatives.
Secure Cloud Migration & Managed Hosting remains a cash cow as migration waves cooled by 2024 and managed services now capture the majority of post-migration spend; sticky workloads drive recurring revenue and high lifetime value for Leidos. Continuous automation of monitoring and FinOps is essential to protect margins, while maintaining certifications and renewal flywheels sustains contract rollovers.
Long-cycle federal IDIQs and recompetes underpin >$18B backlog (FY2024), yielding steady margins and cash conversion; prioritize delivery excellence to defend incumbency.
Civil Enterprise IT (stable contributor to Leidos’s ~$15.1B revenue in FY2024) and Health IT recurring programs drive predictable free cash flow; automate to lift margins.
Managed hosting/cloud is sticky post‑migration cash cow; use FinOps and certifications to preserve margins.
| Business Line | FY2024 Metric | Role | Key Action |
|---|---|---|---|
| Federal IDIQs | Backlog >$18B | Primary cash | Protect incumbency |
| Civil IT | Stable vs $15.1B rev | Predictable cash | Automate |
| Health IT | High renewal rates | Recurring cash | Standardize ops |
| Cloud/Hosting | Post‑migration sticky | Steady margins | FinOps & certs |
The file you're previewing is the exact Leidos BCG Matrix you'll receive after purchase—no watermarks, no demo text, just the finalized, fully formatted report. It’s crafted for strategic clarity by industry-savvy analysts and ready to plug into presentations, planning, or client decks. After buying you'll get the same editable, print-ready document delivered instantly to your inbox. No surprises—just a polished, analysis-ready tool you can use right away.
Legacy on-prem data center management at Leidos sits in low-growth, shrinking footprints with pervasive price pressure; operations are cash-neutral at best after staffing and facility overhead. Turnaround investments rarely yield returns as customers migrate to cloud and managed services. Recommend exit or taper with minimal reinvestment to preserve margins and redeploy capital.
Non-core commercial advisory engagements sit in the Dogs quadrant: small, fragmented work outside Leidos core federal markets where the firm has competitive advantage, yielding low differentiation and fickle demand.
These engagements are hard to scale, tie up resources with minimal strategic return, and depress portfolio focus; recommended action is divestiture or narrowing to a few strategic anchor clients only.
Low-margin staff augmentation runs on commodity rates with typical gross margins around 10% in 2024 and talent churn near 22%, producing thin contribution that often only reaches break-even and caps upside. It consumes disproportionate management attention without building IP or a defensible moat. Prune aggressively or bundle into higher-value outcomes to protect margins and strategic focus.
Aging custom apps on sunset platforms are maintenance-heavy, consuming up to 80% of IT budgets (Gartner), show little growth (often under 2% CAGR) and accumulated tech debt drags profitability for Leidos business lines.
Clients resist modernization spend, pinching margins and converting these offerings into cash-trap territory; strategic choices are retire, migrate, or sell the book.
Hardware pass-through for Leidos sits in Dogs: race-to-the-bottom pricing yields thin margins (typical IT hardware resale gross margins 3–8%) and inventory carrying costs ~20% of value annually, tying up working capital that could be deployed against Leidos’ $14.4B FY2023 revenue base.
Minimal differentiation and inventory risk make it a distraction absent strategic bundling; recommend wind-down or partner-light models rather than holding stock.
Legacy on‑prem ops, low‑margin staff augment, hardware pass‑through and aging apps sit in Dogs: low growth (<2% CAGR), thin margins (staff ~10% in 2024), churn ~22%, hardware margins 3–8% with ~20% inventory cost, and maintenance up to 80% of IT spend. Recommend exit, prune, or sell to redeploy capital from Leidos’ $14.4B FY2023 base.
| Asset | Key metrics | Action |
|---|---|---|
| Staff aug | 10% GM;22% churn | Prune |
| Hardware | 3–8% GM;20% inv cost | Wind‑down |
Exploding interest in generative AI (market about $10.8B in 2023) meets early accreditation and trust hurdles that keep Leidos share low today; enterprise AI pilots often show ROI in 12–24 months, so returns lag heavy upfront spend on models, pipelines and guardrails. Focus on win pilots that prove mission impact, then scale—the right reference wins could sprint a Question Mark to Star.
Policy momentum for zero-trust managed services is strong—global zero-trust market ~28B in 2024 with ~17% CAGR to 2030—yet the field is crowded and standards are still maturing. Leidos has key capabilities and some contracts but platform share isn’t locked. Recommend investing to productize offerings and demonstrate faster ATOs to accelerate wins. If share jumps, this can become a durable revenue engine for Leidos.
Infrastructure agencies are largely in pilot mode, not yet standardizing; buyers stay cautious and budgets are phased, even as the digital twin market forecasts a 37.8% CAGR (from about $6.5B in 2021 toward ~$73.5B by 2028). High growth potential exists but adoption hinges on repeatable blueprints and co-funded lighthouse deployments to de-risk procurement. Time-box the bet: either scale within 18–36 months or reallocate capital.
Commercial cyber sits in a large addressable market—global cybersecurity spending ~USD 190B in 2024—but Leidos’ brand and FY2024 revenue of about USD 14.5B remain heavily federal-focused, with commercial share under 20%; GTM costs are high and competitors (MSSPs, big tech) are entrenched, so target defense-adjacent verticals, bundle mission-grade IP, and scale fast or pivot back to core.
Autonomous logistics and swarm support is R&D-rich with operational adoption still forming, requiring proofs of safety, reliability, and interoperability that demand cash-heavy upfront investment; Leidos reported FY2024 revenue of 14.4 billion, positioning it to absorb development costs while seeking flagship land programs to cement credibility. If defense and commercial procurement tip, this segment can move squarely into Star territory.
Generative AI (~USD 10.8B 2023) shows high upside but slow accredited wins; prioritize pilot-to-reference plays. Zero-trust (~USD 28B 2024, ~17% CAGR) needs productized ATOs to capture share. Digital twins (high CAGR) and autonomous logistics require lighthouse deployments or time-box divest; commercial cyber (global ~USD 190B 2024) needs defense-adjacent GTM to scale.
| Segment | Market | CAGR | Leidos | Action |
|---|---|---|---|---|
| Gen AI | USD 10.8B (2023) | — | Low share | Pilot→scale |
| Zero-trust | USD 28B (2024) | ~17% | Partial | Productize ATO |
| Digital twin | High growth | ~37.8% (forecast) | Pilots | Lighthouses |
| Commercial cyber | USD 190B (2024) | — | Commercial <20% | Defense verticals |
| Autonomous | R&D market | — | Capable | Flagship wins |


