
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
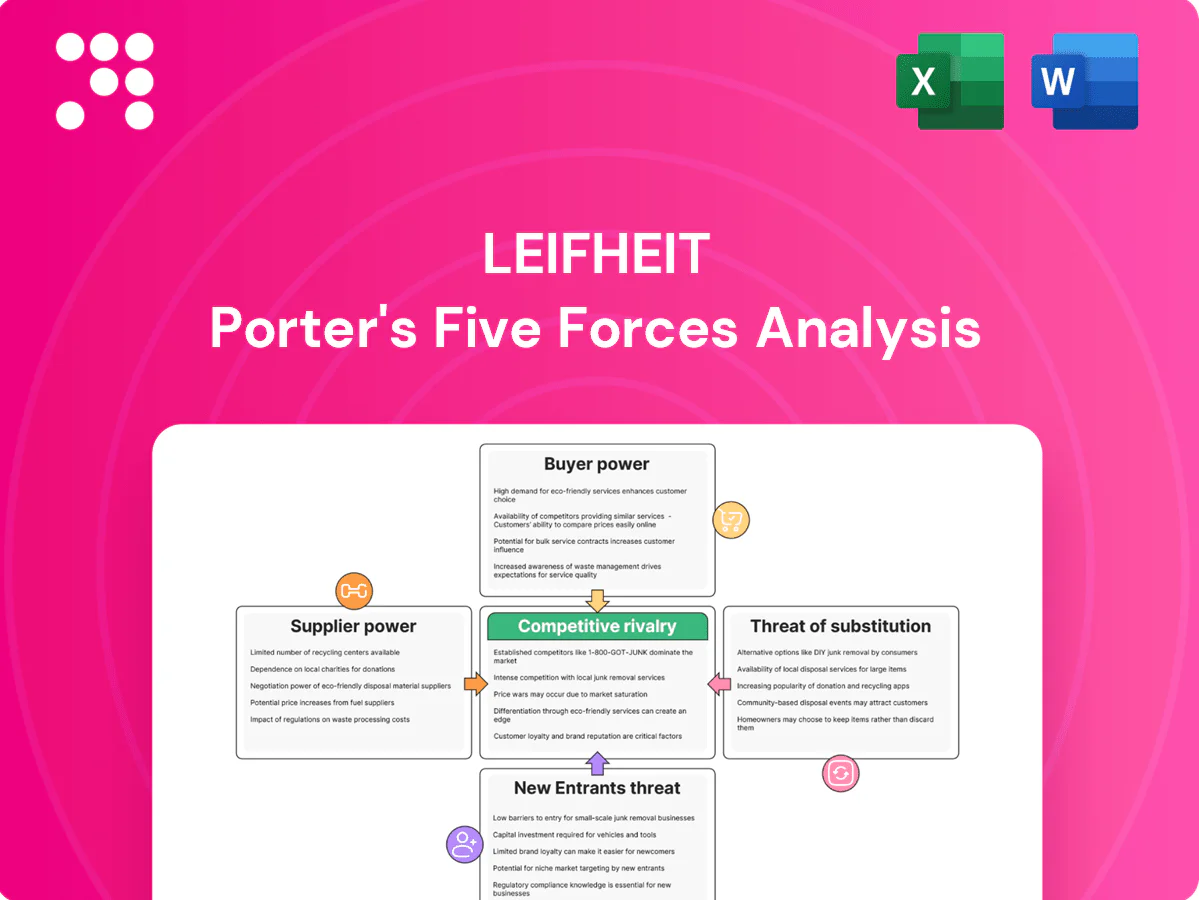
Leifheit’s Porter's Five Forces snapshot outlines supplier influence, buyer bargaining, competitive rivalry, substitute threats, and entry barriers to show where strategic pressure points lie. It summarizes key risks and opportunities shaping the company’s positioning. This brief only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore Leifheit’s competitive dynamics and market pressures in detail.
Leifheit sources plastics, metals, textiles and coating chemicals, diversifying supplier exposure and lowering single-input dependence. This breadth complicates quality control and logistics across categories, impacting margins as commodity swings—e.g., polymer and metal price volatility—can compress profits. Multi-sourcing and long-term contracts have been used to stabilise availability and cost; Leifheit reported FY 2023 revenue of €329.7m.
Some Leifheit SKUs need bespoke molds, mechanisms and tooling that sharply limit supplier switchability, with 2024 industry data noting tooling investments often exceed €100,000. Suppliers owning unique dies or patented parts can command premiums typically in the 10–20% range. Changing suppliers risks requalification costs and 3–6 month time-to-market delays. Strong engineering specs and dual-tooling materially reduce this lock-in.
EU compliance and sustainability norms, notably the CSRD phased in from January 2024 covering about 50,000 companies, narrow the pool of qualified suppliers by imposing strict reporting and traceability standards.
Certified suppliers gain bargaining power due to audit requirements and the cost of maintaining end-to-end traceability, strengthening their negotiation leverage.
At the same time, compliance raises supply reliability and reputational value for buyers and suppliers, and strategic partnerships can exchange volume visibility and multi-year contracts for improved pricing and terms.
Global distribution exposes Leifheit to shipping-rate and lead-time variability, with freight spikes shifting bargaining power to suppliers located closer to EU plants who can promise shorter, cheaper delivery windows. Nearshoring and larger inventory buffers implemented in 2024 reduced urgent purchase exposure, while improved digital forecasting and allocation cut stockouts during disruptions. Supplier leverage still rises during acute freight volatility but is partially contained by these measures.
Leifheit’s mid-scale volumes give it leverage with many component makers but rarely with global commodity firms; in 2024 major upstream players such as BASF (resins) and ArcelorMittal (steel) retained strong pricing power, constraining downstream margins. Smaller, regional suppliers often concede on unit price for stable orders, while Leifheit’s ability to aggregate demand across product lines boosts negotiating clout.
Leifheit faces moderate supplier power: diversified inputs lower single-source risk but commodity firms (BASF, ArcelorMittal) retained pricing leverage in 2024, squeezing margins. Tooling lock-in (tool costs >€100,000) and CSRD from Jan 2024 raise supplier switching costs and favor certified vendors. Nearshoring, inventory buffers and demand aggregation partly restore buyer leverage.
| Metric | 2024/2023 |
|---|---|
| Revenue | €329.7m (FY 2023) |
| Tooling cost | >€100,000 (industry) |
| Regulation | CSRD effective Jan 2024 |
 Detailed Word Document
Comprehensive Porter's Five Forces analysis tailored to Leifheit, uncovering competitive drivers, supplier and buyer power, threat of substitutes and new entrants, and highlighting disruptive risks and strategic levers to protect margins; delivered in fully editable Word format for integration into investor decks, business plans, or internal strategy reports.

 Customizable Excel Spreadsheet
Leifheit Porter's Five Forces offers a compact, quantified one-sheet of competitive pressures so teams can quickly spot vulnerabilities and prioritize strategic actions to reduce risk and capture opportunities.
Key accounts like DIY chains, hypermarkets and department stores wield strong negotiating power over Leifheit, extracting concessions on slotting, promotions and pricing. Slotting fees and promotional pressure, together with private-label threats, compress margins and can shift sales volume quickly; losing a major retailer can reduce volumes by 20–30% and cut visibility. Joint category planning and data-sharing agreements help secure shelf space and improve assortment decisions.
Price-transparent consumers raise buyer power for Leifheit: by 2024 roughly 68% of European shoppers used online comparisons and reviews before purchase, increasing B2C price sensitivity and low-friction switching to similar homecare products. Strong branding and design differentiation reduce pure price battles, while extended warranties and after-sales support (common in 60–70% of premium SKUs) add perceived value and customer stickiness.
Retailers increasingly push private-label cleaning and laundry tools, offering comparable functionality at lower prices and raising buyer leverage. Leifheit must defend through demonstrable innovation, superior ergonomics and documented durability to justify premiums. Exclusive SKUs and retailer partnerships that limit direct comparability can blunt private-label substitution.
Large B2B orders force Leifheit to offer volume discounts and extended payment terms, concentrating negotiating power among key retail partners; simultaneous growth in e-commerce (global online retail ~25% of sales in 2024) lets Leifheit recapture D2C margins but raises fulfillment and return costs.
Retailers demand high OTIF (commonly ≥95%) and rapid replenishment; failures can trigger penalties or delistings, pressuring margins and distribution access. Advanced planning and regional warehousing lower stockout risk and transit times. Data-linked forecasts improve retailer alignment and have been shown to cut safety stock by double-digit percentages in comparable FMCG/DIY supply chains.
Key accounts (DIY/hypermarkets) exert high leverage, risking 20–30% volume loss if delisted; 68% of European shoppers used online comparisons in 2024, raising price sensitivity. Private-label and promotional pressure compress margins; OTIF requirements (≥95%) and penalties intensify retailer power. D2C (~25% of sales in 2024) offers margin recovery but increases fulfillment costs.
| Metric | 2024 |
|---|---|
| Online comparison use | 68% |
| D2C share | ~25% |
| Volume risk if delisted | 20–30% |
| OTIF target | ≥95% |
This preview shows the exact Leifheit Porter’s Five Forces analysis you will receive upon purchase—no placeholders or samples. It contains a complete assessment of competitive rivalry, supplier and buyer power, threats of entry and substitutes, and strategic implications. The file is professionally formatted and ready for immediate download and use.
Cleaning tools and kitchen gadgets host numerous global and regional brands, making categories crowded and margins pressure intense; Leifheit reported about €360m sales (FY 2023/24), underscoring scale needs to compete. Product differentiation is often incremental, intensifying shelf competition and elevating marketing and in-store execution as decisive battlegrounds. Broad category breadth enables cross-sell and helps retain retail space through SKU depth.
Store brands undercut Leifheit on core SKUs, exploiting scale to shave prices and capture value—German private label grocery share rose to about 46% in 2024, signaling strong retailer pricing power. Quality gains have narrowed performance gaps, intensifying rivalry as branded margins compress. Branded players must justify premiums through superior design, proven longevity and faster innovation cadence backed by IP to slow commoditization.
Consumers now demand ergonomic, space-saving and eco-friendly features, driving Leifheit to match market trends as its reported 2024 revenue of €247m underlines pressure to sustain growth; quick 12–18 month copycat cycles compress innovation payoffs and shorten ROI windows. Patents, unique mechanisms and proprietary materials protect margins, while rapid NPD and modular platforms refresh assortments and cut time-to-shelf.
Brand trust drives repeat purchases in household goods, with trusted brands reporting materially higher repurchase intent; rivals spent heavily on promotions and influencer content as influencer marketing reached an estimated $22B global spend in 2024. An efficient media mix and clear value propositions lift conversion rates, while awards and independent tests (e.g., 3rd‑party lab wins) substantiate claims and reduce purchase friction.
Leifheit faces intense category rivalry as crowded global and regional brands pressure margins; group sales ~€360m (FY 2023/24) highlight scale needs. Private labels (Germany ~46% 2024) and fast 12–18 month copycat cycles compress premiums and ROI. Heavy promo and influencer spend (global ~$22B 2024) make media efficiency and proven product claims decisive.
| Metric | 2024 |
|---|---|
| Leifheit sales | ~€360m FY2023/24 |
| Germany private label share | ~46% |
| Influencer spend | ~$22B |
| Copycat cycle | 12–18 months |
Low-cost disposable wipes and single-use pads threaten Leifheit by offering cheaper, convenience-driven alternatives; the global wet wipes market was valued at about $9.2 billion in 2024, highlighting scale. Convenience boosts short-term demand but raises sustainability concerns that can damage brand equity. Pricing promotions can quickly shift volumes, while eco messaging and refillable systems (rising in adoption in 2024) counter disposables.
Vacuums, steam cleaners and robot devices increasingly substitute manual Leifheit tools, with the global robot vacuum market reaching about USD 6.7 billion in 2024 and smart-home penetration near 30% of households in 2024, driving tech adoption as prices fall. Higher upfront cost is offset by lower perceived effort and time savings, while hybrid tools and accessory lines often complement appliances, preserving some demand for manual products.
Laundromats and pickup-delivery services reduce at-home drying needs, with pickup penetration rising in major EU cities; urbanization (about 57% of global population urban in 2024) and smaller living spaces sustain paid-service demand. Economic downturns can push consumers back to DIY, seen in appliance sales rebounds during recessions. Leifheit defends relevance via compact, multipurpose laundry products and FY 2023 revenue of €180.7m.
Generic microfiber cloths and basic buckets often substitute Leifheit tools; social platforms amplify hacks—TikTok ~1.5 billion monthly users and Instagram ~2 billion accounts (2023–24) spread low-cost alternatives rapidly. Leifheit must demonstrate measurable performance advantages to justify premium; in-store demos and how-to content reduce perceived equivalence.
Food processors and multifunction cookers have eroded demand for single-purpose manual gadgets, with multi-cookers growing ~12% year-on-year through 2024 and capturing roughly 9–11% of small appliance unit sales in many EU markets.
Counter-space constraints drive consolidation, prompting consumers to favor multifunction devices, while durable, easy-to-clean designs sustain preference for some manual tools among 30–40% of buyers.
Bundling, modular storage and accessory ecosystems increase product stickiness and after-sales revenue, lifting attachment rates and repeat-purchase likelihood.
Disposables and refillables (wet wipes market ~$9.2B in 2024) and low-cost cloths erode premium margins; eco/refill trends mitigate this. Robovacs/steam cleaners (robot vacuum market ~$6.7B, smart-home ~30% households in 2024) shift demand from manual tools. Urban pickup/delivery and multi-cookers (≈12% YOY growth in 2024) compress need for single-purpose products.
| Substitute | 2024 stat |
|---|---|
| Wet wipes | $9.2B |
| Robot vacuums | $6.7B |
| Smart-home reach | ~30% |
| Multi-cookers YOY | ~12% |
Basic cleaning and kitchen tools are easy to design and source; OEM/ODM ecosystems enable fast entry with modest capital. In 2023 global houseware imports from China topped $100bn, lowering time-to-market and making differentiation and branding the main hurdles for Leifheit. Quality systems and safety compliance still require meaningful CAPEX and recurring audit costs.
Gaining shelf space is difficult without proof of velocity, as incumbents benefit from category management and entrenched retailer relationships; EDEKA and REWE together hold roughly 40% of German grocery market share (2023–24), concentrating buyer power. New entrants typically start online to gather sales data and consumer reviews, then use that performance to pitch listings; European e‑commerce accounted for about 15% of retail sales in 2024, easing this route. Clear niche positioning and robust sell‑through metrics materially improve access to limited shelf slots.
Household goods touch daily routines, so reliability is critical and Leifheit’s 65-year legacy (founded 1959) creates a strong brand moat. With 79% of consumers trusting online reviews (BrightLocal 2023), reviews and word-of-mouth can build or break new entrants rapidly. Leifheit’s established warranties and service raise switching costs, forcing entrants to overdeliver on design, durability and after-sales support to convert users.
Incumbents like Leifheit leverage volume purchasing and optimized tooling to keep unit costs low, raising the capital and scale hurdles for new entrants. Newcomers typically face higher unit costs and weaker supplier terms; contract manufacturing narrows but does not eliminate these gaps. Adoption of automated assembly and modular designs is deepening the cost moat, further deterring entry.
Leifheit’s patents on mechanisms and protected designs create tangible barriers, deterring direct copying and supporting premium positioning. Cross-border enforcement is costly and time-consuming, which slows but does not fully prevent low-quality clones. Rapid product refresh cycles in 2024 further raise imitation costs by shortening ROI windows. New entrants therefore target unprotected, price-led niches.
Low design complexity and China OEM scale (global houseware imports from China >$100bn in 2023) enable fast entry; e‑commerce (~15% of EU retail 2024) lowers shelf barriers but incumbents (EDEKA+REWE ≈40% DE grocery share 2023–24) hold buyer power. Brand, warranties and patents (Leifheit est.1959) raise switching costs and enforcement expense.
| Barrier | Metric |
|---|---|
| Buyer concentration | 40% (EDEKA+REWE) |
| E‑commerce | 15% EU (2024) |


