
Digital download
Access the files immediately after checkout.
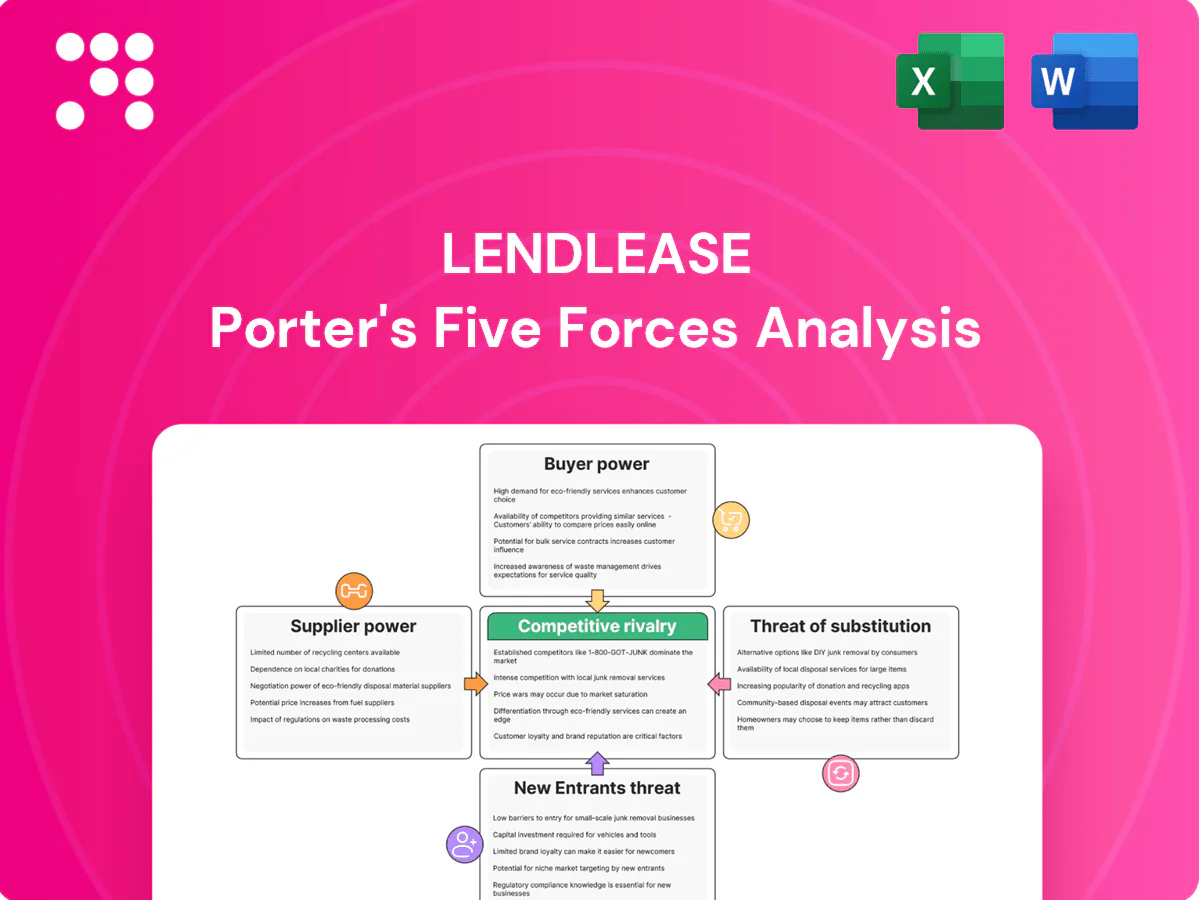
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
LendLease faces varied competitive pressures across construction, development and investment segments, with moderate supplier power, high buyer scrutiny and rising substitute risks from modular builds and proptech. Regulatory and capital intensity create meaningful barriers, yet rivalry is fierce. This snapshot only scratches the surface—unlock the full Porter's Five Forces report for force-by-force ratings, visuals and actionable strategy.
Steel, cement, glass and specialist façades come from a concentrated supplier base (China produced ~56% of crude steel in 2024) giving vendors price/delivery leverage; commodity-driven input volatility (construction input prices rose ~18% in 2024) can quickly cause cost overruns. Lendlease reduces risk via multi-sourcing and long-dated procurement, but mega-project scale still ties it to key vendors and substitutions are often blocked by design approvals.
Specialist trades (MEP, tunneling, façade, digital engineering) remain capacity-constrained in major cities; 2024 industry surveys found 68% of contractors reporting shortages and bid premiums rising 8–12%. Tight labor markets and strong union frameworks have elevated rates and shifted more risk upstream to owners. Preferred-subcontractor models boost predictability but entrench dependence on a narrow supplier base. Schedule-critical packages give subs outsized negotiating power on variations and claims.
Prime urban sites make Lendlease dependent on landowners and planning authorities, with scarce zoning approvals and entitlements commonly extending project timing by 2–5 years and giving these gatekeepers supplier-like leverage. Value-capture rules such as inclusionary housing requirements—often up to 20% of units—and infrastructure levies materially compress project returns. Lendlease’s partnering and placemaking track record mitigates but does not remove this dependency.
Equipment and technology providers—heavy plant lessors, BIM/CDE platforms and modular manufacturers—are concentrated in key segments, raising switching costs once project methodologies are locked; service-level reliability directly affects safety and schedule, increasing supplier leverage despite framework agreements moderating rates.
Debt, bonding and insurance markets supply execution capacity and de-risk Lendlease projects, but 2024 saw insurance market hardening with premiums up around 10%–12%, shifting more retention onto the developer; lenders' covenants (cashflow and gearing triggers) directly influence project pacing and distributions; diversified capital partners lower concentration risk but cannot fully neutralize cycle turns.
Concentrated suppliers (China ~56% crude steel) and commodity input inflation (+18% construction inputs in 2024) give vendors price/delivery leverage. Skilled trades shortages (68% of contractors reporting in 2024) and schedule-critical packages boost subcontractor power. Insurance hardening (+10–12% 2024) and lender covenants further constrain project flexibility.
| Metric | 2024 |
|---|---|
| Steel share (China) | 56% |
| Input inflation | +18% |
| Contractor shortages | 68% |
| Insurance prem. | +10–12% |
 Detailed Word Document
Uncovers key drivers of competition, customer influence, and market entry risks tailored to LendLease, detailing supplier and buyer power, threat of substitutes, competitive rivalry, and barriers protecting incumbents. Highlights disruptive forces, emerging threats, and strategic levers to safeguard profitability and market position.

 Customizable Excel Spreadsheet
A clear one-sheet summary of LendLease's five forces—quickly spot competitive pressures and strategic levers to relieve pain points in partnering, bidding and project margins for faster, confident decisions.
As anchor clients, government and public agencies run competitive tenders with strict risk-transfer terms, driving aggressive pricing and firm performance guarantees; political oversight creates frequent change-order friction but also bargaining leverage for clients. Large multi-year infrastructure pipelines deliver repeat work yet compress contractor returns, typically yielding single-digit project margins.
Pension funds and sovereigns controlling over $60 trillion of investable capital in 2024 push fee compression and co-invest rights, raising bargaining power versus managers like Lendlease. Rigorous due diligence—commonly 6–12 months—reshapes terms and project scope. Strong track record helps win mandates, but mandates remain contestable as capital can be reallocated globally.
Blue-chip corporate tenants and pre-committers anchor LendLease developments via pre-leases and design inputs, often linking commitments to sustainability specs and flexible layouts. They extract incentives, rent-free periods and capex contributions, materially affecting projected returns. With Australian CBD vacancy around 16–18% in 2024, tenant leverage on rent and fit-out terms is heightened, and failure to secure pre-commits can stall financing.
Homebuyers and strata purchasers in residential markets remain highly price-sensitive in 2024, able to delay purchases during downturns and slowing sales velocity that forces promotions. Nearby competitive offerings cap LendLease pricing power, while quality, sustainability and amenities shift demand but must align with affordability to convert buyers.
Global developers as co-partners: joint ventures spread project risk but grant partners measurable negotiation leverage over governance and economics, often driving preferential cost sharing and decision rights. Strong alternatives let partners press for preferential waterfalls and exit rights, constraining LendLease’s upside capture. ESG and community-alignment requirements add binding conditions to JV agreements. Reputation benefits accrue but do not eliminate the impact of diluted control.
Government tenders and public agencies impose strict risk-transfer terms, driving aggressive pricing and frequent change-order friction that compresses margins to single-digit levels. Pension funds and sovereigns holding over $60 trillion in 2024 demand fee compression and co-invest rights, increasing leverage. Tenants and buyers, with Australian CBD vacancy ~17% in 2024, force concessions on rent, fit-out and pre-lease terms.
| Counterparty | 2024 metric |
|---|---|
| Public sector | Single-digit project margins |
| Pension/sovereign capital | $60 trillion |
| CBD vacancy (Australia) | ~17% |
This preview displays the exact LendLease Porter's Five Forces Analysis you'll receive immediately after purchase—no samples, no placeholders. The full, professionally formatted document is ready for download and use upon payment. It delivers a thorough assessment of barriers to entry, supplier and buyer power, competitive rivalry and substitute threats, plus actionable strategic insights for decision-makers.
Global EPCs and local champions clash head-to-head on marquee projects, driving intense bid competition where tendering compresses margins and shifts more risk onto contractors; Lendlease leans on integrated design, financing and placemaking to differentiate, and win rates remain highly sensitive to pricing discipline and risk allocation in bids.
Cyclical pipeline swings drive fierce rivalry for ASX-listed Lendlease (ASX:LLC): downturns spark price wars while booms strain capacity and erode execution quality. Rivalry intensifies in gateway cities where pipelines cluster—Sydney, London, New York—raising bid competition and margin pressure. Counter-cyclical investment management cushions returns but does not neutralize cycle effects. Portfolio mix across sectors and geographies materially affects stability.
Competitors increasingly bundle development, construction and funds management to capture end-to-end margins, turning supply-chain depth, digital platforms and ESG credentials into table stakes; failure to integrate now drives client and fee leakage to vertically integrated rivals. Partnerships with capital providers are expanding competitive scope, shifting battles from project wins to ecosystem control.
City-specific incumbents hold deep relationships, land banks and regulatory fluency, so newcomers face higher costs and slower approvals that keep rivalry localized. Lendlease’s urban regeneration brand eases entry but must adapt to local norms and planning regimes. Joint ventures are often necessary to access sites and approvals.
Best-in-class safety and sustainability are now competitive filters for Lendlease; rivals invest in low-carbon materials and precinct-scale energy, shifting bids toward ESG-compliant partners and risking bid losses and reputational damage for laggards. Certification achievements such as NABERS and Green Star progressively narrow differentiation windows over time.
Global EPCs and local champions drive margin-compressing bid wars; Lendlease (ASX:LLC) relies on integrated development, construction and funds management to defend win rates. Cyclical pipelines in Sydney, London and New York amplify rivalry; ESG credentials (NABERS, Green Star) now filter bids and tighten differentiation.
| Metric | Detail |
|---|---|
| Listing | ASX:LLC |
| Core markets | Sydney, London, New York |
| Model | Dev+Construction+Funds |
Corporate and public clients increasingly favor retrofit to cut capex and emissions, with buildings responsible for roughly 40% of global CO2 emissions and retrofit activity rising amid a global construction market near USD 12 trillion in 2024. Adaptive reuse competes directly with ground-up projects as policy incentives for refurbishment expand. Lendlease can pivot services toward refurbishment but may face smaller, more fragmented contract sizes and lower per-project margins.
Factory-built modular and offsite solutions can compress project schedules by up to 50% and deliver reported cost savings of 10–20%, substituting traditional on-site methods and appealing to cost-focused clients. If competitors vertically integrate modular supply, Lendlease faces disintermediation and margin pressure. Building strategic alliances or equity stakes with modular suppliers in 2024 mitigates revenue loss and preserves project pipeline control.
Distributed work has cut CBD office demand—Australian CBD vacancy rose to ~15.2% in 2024 (JLL), driving tenants to downsize or defer new leases. Firms shift to smaller suburban hubs or home setups, pressuring developers to rebalance mixed‑use schemes toward residential or logistics to capture demand. Lendlease must use precinct activation—retail, amenities, events—to retain occupiers and sustain rental yields.
Digital delivery and PM platforms enable owners to in-source via BIM coordination and advanced PM tools, with 2024 surveys indicating around 38% of large owners shifting core PM tasks in-house, compressing integrator demand and margins by roughly 10–15%.
Transparent project data commoditizes routine services; Lendlease must sell outcome guarantees, digital twins and lifecycle performance warranties to neutralize substitution and preserve value.
Substitutes—retrofit, modular, sector rotation (data centres, logistics, renewables), and in-sourcing—are eroding Lendlease’s traditional project and fee pools; retrofit and buildings drive ~40% of CO2 and a ~USD12tn 2024 market, modular cuts schedules ~50% and costs 10–20%, CBD vacancy ~15.2%, in‑sourcing 38% (2024).
| Substitute | 2024 metric |
|---|---|
| Retrofit/market | 40% CO2; USD12tn |
| Modular | -50% time; -10–20% cost |
| CBD vacancy | 15.2% |
| In‑sourcing | 38% |
Large projects Lendlease targets often exceed $1bn and require strong balance-sheet strength and surety capacity, which screens out undercapitalized entrants. Surety bonds commonly run 5–10% of contract value, imposing immediate liquidity and capital tests. Rising commercial insurance deductibles—reported around 15% higher in 2023–24 by industry brokers—further raise the bar, while established track records remain decisive.
Urban regeneration typically requires multi-year approvals and stakeholder management, with public consultation windows commonly 28–60 days and project approvals often taking 3–7 years, creating high upfront time costs. New entrants lack the long-standing government, community and supply-chain relationships and process know-how that incumbents like Lendlease have developed. Rising community and ESG expectations—now embedded in many planning conditions—increase compliance scope and monitoring costs. Such delays and added costs erode feasibility and deter newcomers.
Scarcity of well-located sites and strong competition from incumbents materially impede new entrants; Lendlease's deep pipeline (reported above A$10bn in 2024) reinforces incumbency advantages. Land banking and public-private partnerships hinge on long-term relationships and favoured access to rezoning, limiting open-market opportunities. Without secured pipelines entrants face high carrying costs and financing strain, while off-market sourcing advantages are sticky and sustain incumbents' gatekeeping.
Major clients in 2024 increasingly vet safety performance, delivery record and measurable sustainability outcomes, making procurement conditional on verified KPIs. New entrants struggle to evidence comparable safety and ESG track records; high-visibility failures are swiftly penalized by contract losses and reputational damage. Incumbent reputations therefore act as a strong barrier, protecting market share.
High capital/surety needs (projects >A$1bn; bonds 5–10% of contract) and rising insurance deductibles (+15% in 2023–24) materially screen entrants, while Lendlease’s >A$10bn 2024 pipeline and long public-sector relationships lock access to land and PPPs. Urban regeneration approvals (3–7 years) plus ESG/safety KPI procurement requirements favor incumbents. Modular/BIM and platform finance (global modular market ~US$150bn in 2024) enable niche, asset-light entry but scaling to precincts remains constrained by delivery track record.
| Barrier | 2024 datapoint |
|---|---|
| Typical project size | >A$1bn |
| Surety bonds | 5–10% contract value |
| Insurance trend | +15% deductibles (2023–24) |
| Lendlease pipeline | >A$10bn (2024) |
| Modular market | ~US$150bn (2024) |


