
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
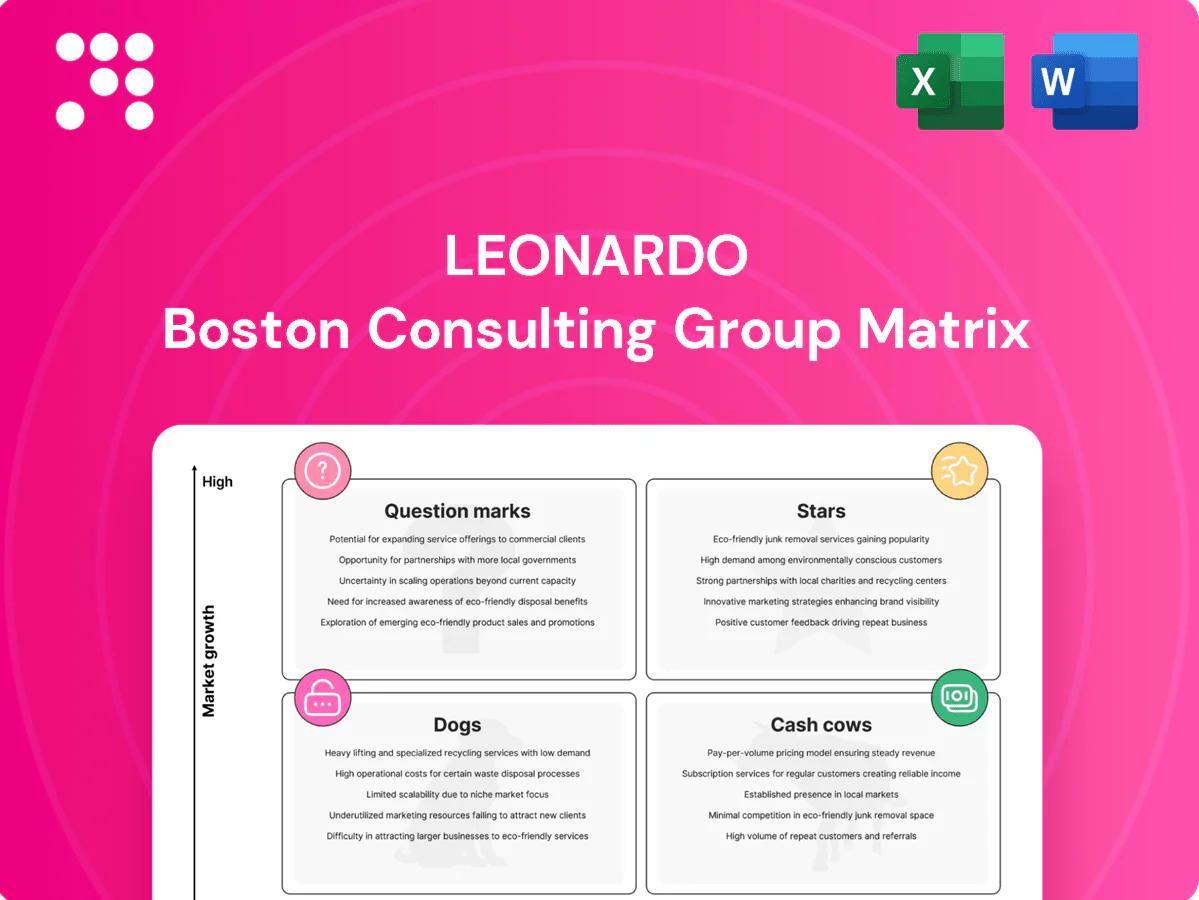
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Think of the Leonardo BCG Matrix as your quick compass through product chaos — it spots Stars, Cash Cows, Dogs, and Question Marks so you don’t waste time guessing. This preview shows the contours; the full report gives quadrant-by-quadrant placements, data-backed recommendations, and a practical roadmap to where to invest, divest, or double down. Buy the complete BCG Matrix for a Word report plus an editable Excel summary — ready to present and act on today.
Multi-mission rotorcraft are in hot demand and Leonardo benefits from a deep global installed base, securing leading positions in civil and para-public markets with significant military pull-through.
Active electronically scanned radars, EW suites and optronics deliver superior performance and interoperability; Leonardo holds a strong share on naval and air platforms as prime or key tier‑1 supplier. NATO defence spending topped $1.2 trillion in 2023 and Indo‑Pacific procurement accelerated in 2024, expanding the addressable market. Double down on R&D and targeted export campaigns to cement the technological edge and capture rising orders.
Integrated mission systems bundle sensors, effectors and software into command, control and combat suites, driving rising adoption across air and naval programs and creating high differentiation and high switching costs. With global military spending at $2.24 trillion in 2023 (SIPRI), demand for sticky C4ISR upgrades and interoperable ecosystems is expanding. Scaling the ecosystem secures long-tail service contracts and recurring upgrade revenue.
Space services & downstream data as a Stars quadrant: Leonardo leverages Earth observation (EO) and satcom services plus ground segment solutions to capture institutional and commercial demand; EO downstream market ~6.5bn in 2024 and global satcom services ~80bn in 2024, with fast growth in climate, security and mobility intelligence driving double‑digit segment growth.
Secure cyber & SOC services sit in Stars: national-level cyber defense, SOCs and managed security for critical infrastructure face an exploding threat landscape with cybercrime costs forecasted at 10.5 trillion USD annually by 2025, driving rising, recurring procurement and improving Leonardo’s win rates thanks to prime-defense credibility.
Scale managed services and automation to protect margins while growing MSS revenue streams and recurring contracts tied to national programs and critical-infrastructure SLAs.
Leonardo Stars: rotorcraft, sensors/C4ISR, space services and cyber show high growth and share — NATO defence spend $1.2T (2023) and global military $2.24T (2023) expand addressable markets. EO downstream ~$6.5bn and satcom services ~$80bn (2024); cybercrime cost est. $10.5T (2025) drives recurring SOC demand. Invest R&D, scale services and exports to capture long‑tail revenue.
| Metric | 2023/24/25 |
|---|---|
| NATO defence | $1.2T (2023) |
| Global military | $2.24T (2023) |
| EO market | $6.5bn (2024) |
| Satcom services | $80bn (2024) |
| Cyber cost | $10.5T (2025) |
 Detailed Word Document
Concise Leonardo BCG Matrix review: quadrant insights, investment moves, threats and trend context for each unit.

 Customizable Excel Spreadsheet
One-page overview placing each business unit in a quadrant, so leaders spot priorities and act fast.
Leonardo’s helicopter aftermarket & MRO is a cash cow: an installed base of over 5,000 rotorcraft delivers predictable parts, maintenance and training revenue, underpinning steady cash flow. The segment sits in a mature, low-growth market (single-digit CAGR) but very high utilization, driving recurring demand. OEM parts and rotorcraft upgrade programs yield strong margins; optimizing inventory, digital maintenance and partner MRO networks can efficiently milk cash.
Aeronautics sustainment underpins Leonardo through contractually anchored support for in‑service trainers, transports and fighter subsystems, yielding steady, modest growth as replacement cycles span decades. High cash conversion arises from spares, depot work and life‑extension kits, driving strong margins. Tighten SLAs and scale performance‑based logistics to lock recurring cash flow.
Installed tactical and naval communications deliver steady refresh and support orders, with legacy comms aftermarket often representing over 40% of product lifecycle revenue in 2024; market growth is muted (low single-digit CAGR) as tech is proven and standardized. Cash generative due to minimal R&D needs; prioritize compatibility updates and service margins rather than share battles to protect EBITDA and free cash flow.
Flight and mission simulators show cash-cow characteristics with service lives commonly between 15 and 30 years and recurring updates sustaining value; procurement is steady across NATO and allied air forces and training academies. High utilization and limited new entrants keep barriers elevated, supporting predictable aftermarket revenue. Prioritize software refresh cycles and expanding content libraries to maintain high ROI and lifetime revenue per unit.
Ground segment operations deliver dependable recurring service revenues, with 2024 contracts supporting steady cash flow from established ground stations and network ops. Market maturity means mostly incremental capacity adds rather than heavy new builds; high asset reuse and disciplined capex preserve margins. Lean ops and strict SLAs keep uplifts predictable and cash generative.
Leonardo cash cows: helicopter MRO (installed base >5,000 units), aeronautics sustainment, legacy comms and simulators deliver high-margin recurring revenue; 2024 aftermarket share ~35–45% of lifecycle revenue and cash conversion >20%. Focus on inventory, digital maintenance and PBL to sustain free cash flow.
| Segment | 2024 metric | Margin/Cash |
|---|---|---|
| Helicopter MRO | >5,000 units | High |
| Aeronautics sustainment | Multi-year contracts | High |
| Comms & simulators | ~40% lifecycle rev | >20% CC |
The file you’re previewing here is the exact Leonardo BCG Matrix you’ll receive after purchase — no watermarks, no demo pages, just the finished, fully formatted report. It’s crafted for strategic clarity and ready to edit, print, or present. Buy once, download immediately, and drop it straight into your planning or pitch materials with zero surprises.
Legacy analog systems face obsolete sensors and comms variants with shrinking support tails; industry surveys in 2024 show approximately 60% of customers migrating to digital, software‑defined solutions. Turnaround would require multi‑million euro refits per platform while strategic value remains thin. Recommend orderly sunset, parts harvesting and resale rather than reinvestment to minimize lifecycle costs and liabilities.
Small bespoke hardware lines are niche boxes built for single customers with no broader roadmap, typically under 1,000 units/year and often representing less than 5% of product revenue (2024 industry benchmarks). Low volumes create high engineering drag, consuming an estimated 20–30% of development capacity and driving unit costs far above scale. These lines are hard to scale and rarely rebid, with repeat RFP rates below 10%, so consolidate or discontinue to free engineering capacity.
Non-core consulting add-ons are ad hoc advisory engagements unlinked to platforms or recurring services, with repeat-business rates often under 20% (2024 market observations). They show weak differentiation, tie up senior talent for low yield—senior utilization can rise 25–35%—and should be wound down or strictly tied to product pull-through.
Dogs: Aging training devices — older simulators without upgrade paths show heavy maintenance and light utilization; 2024 procurement slowdowns make customer replacement capex unlikely, pushing operators to decommission, sell, or seek trade‑up bundles.
Aging training devices are maintenance‑heavy, low‑utilization assets (avg util <30%; maintenance >12% asset value in 2024). Replacement capex constrained (procurement delays +18% YoY in 2024), so resale, decommission, or bundle into trade‑ups recommended. Recovery unlikely; dispose/parts‑harvest to avoid >€2M annual carry per product line.
| Metric | 2024 |
|---|---|
| Utilization | <30% |
| Maintenance | >12% asset value |
| Procurement delay | +18% YoY |
| Carry risk | >€2M/line |
Uncrewed aerial systems sit in a surging market estimated at about $25 billion in 2024, but demand is highly competitive and fragmented. Leonardo brings proven capabilities and references within its ~€14.5 billion 2024 business base, yet market share is not locked in. With the right partnerships and mission payloads, Leonardo could scale rapidly. Invest selectively in interoperable, exportable platforms—or partner if speed lags.
Counter‑UAS sits as a Question Mark for Leonardo: the global C‑UAS market was estimated at $3.8 billion in 2024 with ~13.5% CAGR forecast to 2030, driven by defense and critical‑infrastructure demand. Multiple rivals and shifting threat profiles give early traction but no dominance. Accelerating integrated offers—radar, EW, effectors—is essential to win programs of record.
AI/ML ISR analytics sit in the Question Marks quadrant: 2024 estimates place the defense AI market near USD 10 billion with ~12% CAGR, driven by customer demand for sensor‑to‑decision speed. Leonardo’s unrivaled data access and mission context provide a platform advantage, but software share and commercialized products remain emergent. Big upside exists in fusing multi‑INT at the edge; prioritize productization and secure reference deployments with flagship clients to de‑risk scaling.
LEO constellations for EO and secure comms are expanding fast: Starlink exceeded 5,000 satellites by 2024 and OneWeb reached ~648, driving growing demand for low-latency secure links and high-revisit EO imagery.
Capital intensive (Starlink capex >10 billion to date), partner‑heavy and risk‑prone (supply chain, spectrum and debris risks); many entrants but market share remains unsettled—pick niches where sovereign access and security differentiation matter and then commit.
Defense customers are actively testing cloud and zero-trust C2 architectures with programs scaling in 2024; growth is strong but procurement models remain nascent. Leonardo brings mission-software DNA and domain expertise yet must navigate hyperscaler ecosystems—top three cloud providers held about 64% of market share in 2024. Co-developing with primes and governments to shape standards early is critical to move this Question Mark toward a Star.
Question Marks: UAS (~$25B 2024) and C‑UAS ($3.8B 2024, ~13.5% CAGR) show high growth but fragmented share; AI/ML ISR (~$10B 2024, ~12% CAGR) offers platform upside; LEO constellations scale (Starlink >5,000 sats, OneWeb ~648; capex Starlink >$10B) but are capital‑heavy; cloud/C2 adoption grows while hyperscalers hold ~64% (2024) — prioritize partnerships, productize, and target sovereign niches.
| Segment | 2024 size | CAGR | Key metric | Action |
|---|---|---|---|---|
| UAS | $25B | — | €14.5B Leonardo base | selective invest |
| C‑UAS | $3.8B | 13.5% | fragmented rivals | integrate offers |
| AI/ML ISR | $10B | 12% | data advantage | productize |
| LEO | — | — | Starlink >5,000 sats | sovereign niches |
| Cloud/C2 | — | — | Hyperscalers ~64% | co‑develop |


