
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Leong Hup International faces intense supplier consolidation, evolving buyer expectations, and rising substitute protein threats that shape its strategic outlook. This snapshot teases force-by-force impacts but omits granular ratings, visuals, and actionable recommendations. Unlock the full Porter's Five Forces Analysis to gain a consultant-grade breakdown and equip your investment or strategy decisions with data-driven insight.
Maize and soybean meal are largely imported for Leong Hup (over 60% of regional feed needs), exposing feed costs to 2024 global commodity cycles and FX swings; 2024 average CME corn ~ $5.20/bu (~$205/ton) and soybean meal ~ $420/ton amplified cost pass-through. A handful of global traders concentrate supply, boosting supplier leverage in tight markets. Hedging and diverse sourcing reduce but do not eliminate volatility; vertical integration into feed milling improves conversion efficiency but offers no control over raw grain prices.
Vaccine, veterinary pharma and breeder genetics are concentrated: in 2024 the top three veterinary pharma players (Zoetis, Elanco, Merck Animal Health) control roughly 50–60% of the global market, while leading broiler breeders dominate supply chains. Switching is limited by biosecurity, performance data and regulatory approvals, enabling price increases and strict contract terms; long-term supply agreements reduce disruption risk but heighten dependence.
Electricity, LPG, diesel and packaging are core inputs with few substitutes, giving suppliers situational leverage as energy price spikes (Brent crude averaged about 86 USD/bbl in 2024) only pass through imperfectly in competitive markets; cold-chain equipment and refrigerants bind firms to specialized vendors, while efficiency and on-site generation programs (requiring capex) can lower exposure but lengthen payback periods.
Import reliance makes Leong Hup vulnerable to shipping rates, container availability and port bottlenecks; during disruptions carriers and freight forwarders gain clear bargaining leverage, extending lead times and driving up freight premia. Longer lead times force higher safety stocks and working capital, while multi-port routing and forward booking mitigate but do not eliminate supplier power.
Vertical integration—in-house feed milling, breeding and processing—lowers reliance on intermediate suppliers and strengthens bulk-purchase leverage and access to technical services, partially offsetting supplier bargaining power. Scale enables centralized procurement and price management, but exposure to global commodity grains and regulated inputs sustains structural supplier influence. Overall supplier power is moderate with periodic cyclical spikes tied to feed-grain markets.
High import dependence on corn ($5.20/bu ≈ $205/t in 2024) and SBM ($420/t) raises supplier leverage; top-3 vet pharma ~50–60% market share increases switching costs. Energy (Brent $86/bbl 2024) and freight bottlenecks periodically spike costs and lead times; vertical integration and hedging reduce but do not remove exposure.
| Input | 2024 | Impact | Mitigation |
|---|---|---|---|
| Corn | $5.20/bu (~$205/t) | High cost volatility | Hedging, multi-sourcing |
| SBM | $420/t | Pass-through | In-house feed mills |
| Vet pharma | Top3 50–60% | Supplier power | Long-term contracts |
 Detailed Word Document
Tailored Porter's Five Forces analysis for Leong Hup International uncovering key competitive drivers, supplier and buyer power, entry barriers, and substitutes that threaten market share, with strategic commentary for investor reports and internal strategy use.

 Customizable Excel Spreadsheet
A concise one-sheet Porter’s Five Forces for Leong Hup International—clarifies supplier, buyer and competitive pressures for fast strategic decisions and boardroom-ready slides.
Large supermarkets, processors and QSRs buy poultry at scale and push for lower prices and tighter specs, with top buyers in Southeast Asia driving annual tenders and private label programs that now account for about 20% of grocery volumes in 2024; easy switching among compliant suppliers amplifies buyer leverage. Service levels, on-time delivery and consistent quality remain the main levers Leong Hup can use to protect margins.
Chicken and eggs are staple proteins so end demand for Leong Hup is highly price elastic; consumers increasingly trade down when retail prices rise and chase promotions when they fall, a dynamic evident through 2024 retail volatility.
Regional export buyers increasingly insist on JAKIM halal certification, HACCP and end-to-end traceability, raising qualification thresholds and adding compliance lead times of weeks to months. Once Leong Hup secures certification switching is possible but not instantaneous, tempering buyer power. Currency swings and cross-border logistics create additional negotiating variables. Long-term supply programs trade committed volumes for sharper pricing and predictable off-take.
Retail and foodservice majors wield strong bargaining power over Leong Hup, while fragmented traditional wet markets have much lower leverage. Expanding direct-to-consumer and e-commerce channels can lift realized prices but requires investment in fulfillment and logistics. Managing the channel mix and leveraging a broad portfolio enables cross-selling and bundled pricing to smooth average margins.
Large retailers, processors and QSRs exert high price pressure via tenders and private labels (≈20% grocery volumes in 2024), amplified by low switching costs among compliant suppliers. Global oversupply (poultry output ~137 million tonnes in 2024) strengthens buyer leverage; certification requirements (JAKIM, HACCP, traceability) raise entry time but not long-term switching. D2C/e-commerce can lift realized prices but increases fulfillment costs.
| Buyer type | Power | Key stat (2024) |
|---|---|---|
| Retail/QSR | High | Private label ~20% |
| Market supply | Competitive | Global output ~137m t |
| Certification | Barrier | JAKIM/HACCP, weeks–months |
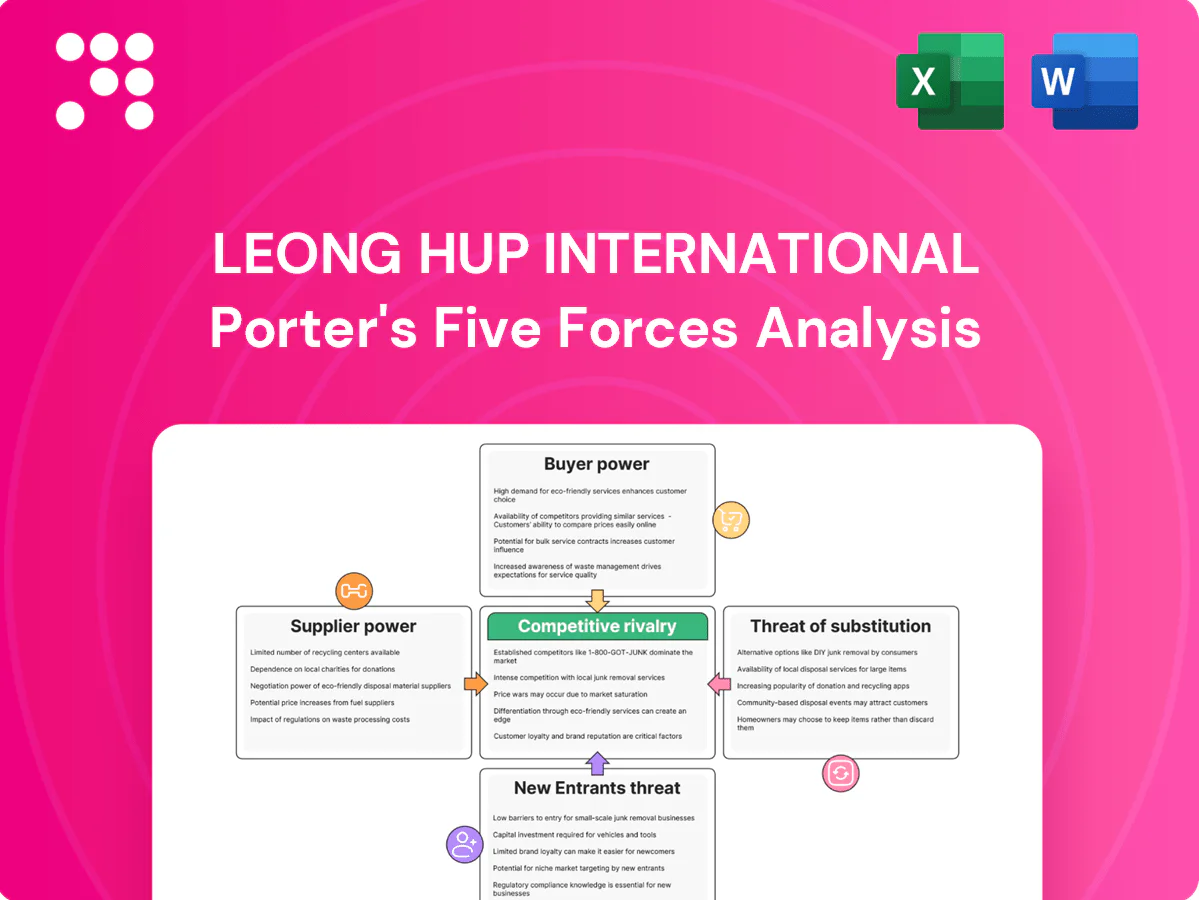
This preview shows the exact Leong Hup International Porter's Five Forces Analysis you'll receive immediately after purchase—no placeholders. The document is fully formatted, ready for download and use the moment you buy, and contains the complete, professionally written analysis.
Players like CP Foods (SET: CPF), Japfa (IDX: JPFA), QL Resources (KLSE: QL) and numerous local integrators compete across feed, broilers and eggs, driving tight margins.
Capacity additions often occur in waves, amplifying price pressure and inventory swings in core markets where frequent promotions are routine.
Rivalry is intense; scale and cost leadership — through integrated feed-to-farm operations and processing efficiencies — determine winners.
In 2024 broiler and egg prices tracked supply-demand closely, causing sharp margin compression during periodic gluts. Cost shocks such as feed or energy spikes cannot always be passed through promptly, squeezing operating income. Continuous productivity and biosecurity efficiency gains are required to sustain profitability. Value-added processing provides some margin buffer but faces intense competition from regional processors and private-label retailers.
Vertical integration lowers cost per kilo and secures quality across feed-to-farm-to-processing, raising the competitive bar for Leong Hup; most large rivals mirror this integration, constraining differentiation. Process innovation and genetics offer the micro-edges that can still move margins, while service reliability and superior biosecurity determine access to institutional accounts.
Disease outbreaks can quickly shift supply and force farm shutdowns, giving firms with stronger biosecurity short-term share gains while industry restarts restore rivalry; compliance costs are sizable and broadly similar across major players, and market-access rules often favor incumbents but intensify head-to-head competition.
Operating across Southeast Asia lets Leong Hup shift supply to match demand peaks and smooth margins, but competitors with similar regional footprints limit that edge; ASEAN population ~670 million (2024) sustains high poultry demand and tight cross-border arbitrage narrows price spreads. Local distributor networks and halal brand credibility in Indonesia (~275m) and Malaysia (~33m) directly affect share outcomes.
Rivalry is intense across feed, broiler and egg segments, with scale and vertical integration deciding cost leaders. 2024 broiler and egg prices tracked supply-demand closely, producing sharp margin compression during gluts. Regional footprint gives flexibility but competitors with similar ASEAN reach (population ~670 million in 2024; Indonesia ~275m; Malaysia ~33m) limit differentiation.
| Metric | 2024 |
|---|---|
| ASEAN population | ~670 million |
| Indonesia | ~275 million |
| Malaysia | ~33 million |
Pork, fish and beef compete with chicken on price, taste and availability, and consumers in SEA routinely shift across proteins based on relative prices and health perceptions. Fish is a strong substitute in many SEA markets where seafood is a primary protein source. 2023–24 avian influenza disruptions led to chicken price spikes of roughly 15–25% in some markets, accelerating temporary switching to fish and pork.
Plant-based meats and egg substitutes remain nascent but expanding: the global plant-based meat market was estimated at about $7.4 billion in 2023 with analysts projecting a ~12% CAGR, while plant-based egg solutions are small but growing. Price premiums and lingering taste/functional gaps—often 20–100% higher at retail—limit broad substitution today, though institutional buyers increasingly trial products for ESG goals, creating niche demand. Ongoing R&D and scale economies could materially raise the long‑run threat to Leong Hup if taste, cost and supply-chain parity are achieved.
Imported frozen chicken can undercut local fresh during downturns or when currency movements favor imports, prompting foodservice buyers to accept frozen for price stability. Non-tariff barriers and halal certification constrain but do not eliminate substitution, as compliant suppliers adapt. Expanded cold-chain reach increases feasibility of frozen substitutes into previously underserved regions.
Tofu, tempeh and legumes present low-cost protein substitutes that gained traction as households shifted to staples during economic stress; global plant-based protein retail sales rose about 11% in 2024, amplifying substitution risk for Leong Hup. Cultural preferences in Southeast Asia moderate pace of switching, keeping demand for animal feed and poultry resilient. Strategic promotional pricing can reclaim volume and margin share quickly.
Nutrition trends shift demand toward perceived leaner or ethical proteins, favoring chicken over red meat while niche free-range and organic segments siphon volume from conventional poultry; eggs remain volatile as cholesterol perceptions cycle and influence retail demand. Transparent sourcing, halal and certification badges reduce substitution risk and support price premiums.
Substitutes (fish, pork, plant-based, tofu) pressure prices—AI outbreaks in 2023–24 raised chicken prices 15–25%, driving temporary switching. Plant-based meat market was ~$7.4B in 2023 with ~12% CAGR; plant-based retail sales +11% in 2024 but remain price-premium. Halal, traceability and cultural preference limit full substitution.
| Substitute | 2023–24 signal |
|---|---|
| Plant-based | $7.4B (2023), +11% retail (2024) |
| Fish/Pork | Price-driven switches; AI ↑ chicken 15–25% |
Feed mills, breeder farms, hatcheries and processing plants require multi-million dollar capex, creating high fixed-cost entry barriers. Economies of scale in feed production and processing compress unit costs, disadvantaging small entrants. Working capital tied in 30–90 days of inventories plus ongoing biosecurity spending raises cash needs. Incumbent utilization cycles (typically 75–90%) and peak supply coverage further deter new entry.
Permits, environmental approvals and JAKIM halal certification require specialist expertise and multistage documentation, creating months-long lead times that deter newcomers. Disease-control protocols and full traceability are mandatory for major buyers and regulators, with non-compliance risking facility closure and export bans. Incumbents like Leong Hup leverage long-standing compliance records and buyer relationships, raising effective barriers to entry.
Nationwide chilled distribution and retailer listings are costly and time-consuming to build, creating a strong barrier to entry for newcomers; QSR and processor relationships require formal audits and trial runs that typically delay onboarding and scale-up. Entrants commonly launch in niche or regional pockets before attempting wider rollouts, making route-to-market a material moat for fresh poultry players like Leong Hup International.
Securing consistent grain supply and hedging exposure requires scale and financial sophistication, creating a high barrier for new entrants to Leong Hup; smaller players face worse procurement terms and higher landed costs. Volatility in feed ingredient markets can rapidly erode the thin margins of newcomers, while supplier credit lines and volume discounts favour established players.
Niche entry remains feasible: small farms can capture free-range, organic or specialty halal pockets with local branding; contract farming under Leong Hup and other integrators already absorbs many entrants. Technology and precision farming cut some input barriers, but compliance costs and scale economies keep mass-market entry difficult; threat is moderate and niche-focused, with premium segments fetching roughly 20–30% higher retail prices in 2024.
High multi-million capex and 30–90 days working capital needs, plus feed costs (~65% of broiler cost) and 75–90% incumbent utilization create steep scale barriers. Regulatory, halal and biosecurity lead times raise months-long entry delays. Distribution, QSR audits and supplier credit favour incumbents. Niche premium segments command ~20–30% higher retail prices in 2024.
| Barrier | Metric (2024) |
|---|---|
| Capex | Multi-million MYR |
| Working capital | 30–90 days inventory |
| Feed share | ~65% of broiler cost |
| Utilization | 75–90% |
| Premium segment | +20–30% price |


