
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Linde operates in a capital‑intensive, concentrated industrial gas market where supplier leverage, buyer negotiation, substitutes, new entrants, and rivalry determine margins and growth. Regulatory heft and scale bolster its position, while tech shifts and customer consolidation raise strategic risks. This brief snapshot only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore Linde’s competitive dynamics, market pressures, and strategic advantages in detail.
Helium supply is concentrated in a few geographies and producers, elevating supplier leverage on price and allocation; scarcity periods have forced pass-through pricing and contractual escalators. Linde mitigates via long-term sourcing agreements, customer-side recycling programs, and a broad industrial-gases portfolio, but episodic shortages still tighten supplier power. Supply shocks can ripple into margins and service levels, particularly for specialty-gas reliant end markets.
Cryogenic air separation and liquefaction consume roughly 200–300 kWh per tonne of O2, tying Linde's unit costs to local utility tariffs. In 2024 industrial electricity averaged about $0.07–0.09/kWh in the US and €0.12–0.18/kWh in the EU, and regulated utility oligopolies can pass through costs imperfectly and with lag. Short-term spikes increase supplier bargaining power. Hedging and efficiency projects (waste-heat recovery, electrification) moderate exposure over time.
Large compressors, turbines and cryogenic heat exchangers are sourced from a limited OEM pool (often under 10 firms), with lead times of 12–24 months and 6–18 month qualification cycles giving suppliers leverage. Linde’s global footprint in 100+ countries, scale and strong in-house engineering enable multisourcing and reduce single-vendor risk. Long-term partnerships trade price for reliability and access to joint innovation, supporting asset uptime and cost predictability.
Hydrogen, syngas and CO2 largely come from natural gas/refinery off‑gases; commodity inputs limit supplier power but pipeline bottlenecks and regional gas price spikes (Henry Hub ~ $2.8/MMBtu in 2024) can raise local leverage. Indexed supply contracts align feedstock and product pricing; on‑site SMRs and vertical integration cut third‑party exposure.
Supplier power is elevated by concentrated helium sources, limited OEMs (<10) for cryogenic equipment, and logistics bottlenecks (US driver shortfall ~80,000 in 2023 impacting 2024). Energy exposure (US $0.07–0.09/kWh; EU €0.12–0.18/kWh) and regional gas moves (Henry Hub ≈ $2.8/MMBtu) add volatility; Linde offsets via long‑term contracts, vertical integration and owned fleet.
| Metric | 2024 |
|---|---|
| Helium concentration | Few geographies/producers |
| OEM pool | <10 firms |
| Electricity | US $0.07–0.09/kWh; EU €0.12–0.18/kWh |
| Henry Hub | $2.8/MMBtu |
| Driver shortfall | ~80,000 (2023) |
 Detailed Word Document
Concise Porter's Five Forces analysis of Linde, examining competitive rivalry, supplier and buyer power, threat of substitutes, and entry barriers to reveal key pressures on margins, market share, and strategic positioning within the industrial gases and engineering sectors.

 Customizable Excel Spreadsheet
One-sheet Porter's Five Forces tailored for Linde—quickly highlights supplier, buyer, rivalry, new entrant, and substitute pressures so teams can prioritize strategic moves and reduce decision paralysis.
Steel, chemical and refining customers buy very high volumes and run competitive tenders, enabling significant price concessions and bespoke commercial terms. Their scale drives negotiating leverage, but take-or-pay provisions and indexation to feedstock or CPI limit renegotiation frequency. Multi-year on-site contracts, often 10+ years, lock in supply and materially reduce churn despite initial buyer leverage.
Pipelines, on-site plants and strict customer qualifications make switching disruptive and costly; on-site contracts commonly exceed 5 years, often tying customers into bespoke infrastructure. Reliability and safety track records thus outweigh small price deltas, shrinking ongoing buyer leverage. This structural stickiness reduces customer bargaining power once contracts are in place and lengthens renewal cycles in Linde’s favor.
Fragmented mid/small buyers in healthcare and food limit bargaining power because numerous smaller accounts are less able to negotiate bespoke pricing; Linde reported roughly $39.4 billion in 2023 sales, highlighting scale advantages. Packaged and specialty gases command higher margins and service components, reinforcing supplier leverage. Strict delivery, compliance and purity needs lower buyer mobility, though volume-aggregation platforms can modestly increase leverage by pooling demand.
Cyclicality raises buyer pushback on price and volumes during industrial downturns, forcing Linde to lean on index-linked clauses and surcharges to protect margins, though these mechanisms often lag spot cost movements. In expansion phases, customers prioritize uptime and delivery speed, reducing price sensitivity as urgency outweighs marginal cost. Quarterly shifts in demand mix between merchant, bulk and project volumes can materially swing bargaining leverage.
Application engineering, digital monitoring and guaranteed uptime (often 99.9% service SLAs) create switching friction—buyers prioritize process optimization and safety over commodity molecules, and bundled solutions dilute pure price comparisons, softening buyer power where performance guarantees are critical.
Linde customers have strong upfront bargaining power via large tenders and volume, but multi‑year on‑site contracts (commonly 5–10+ years), index‑linked pricing and high switching costs materially reduce ongoing leverage; reliability, SLAs (≈99.9%) and bundled services shift negotiations toward service terms. Linde reported $39.4 billion sales in 2023 and maintained margin resilience through indexation in 2024.
| Metric | Value |
|---|---|
| Typical contract length | 5–10+ yrs |
| 2023 sales | $39.4B |
| Service SLA | ≈99.9% |
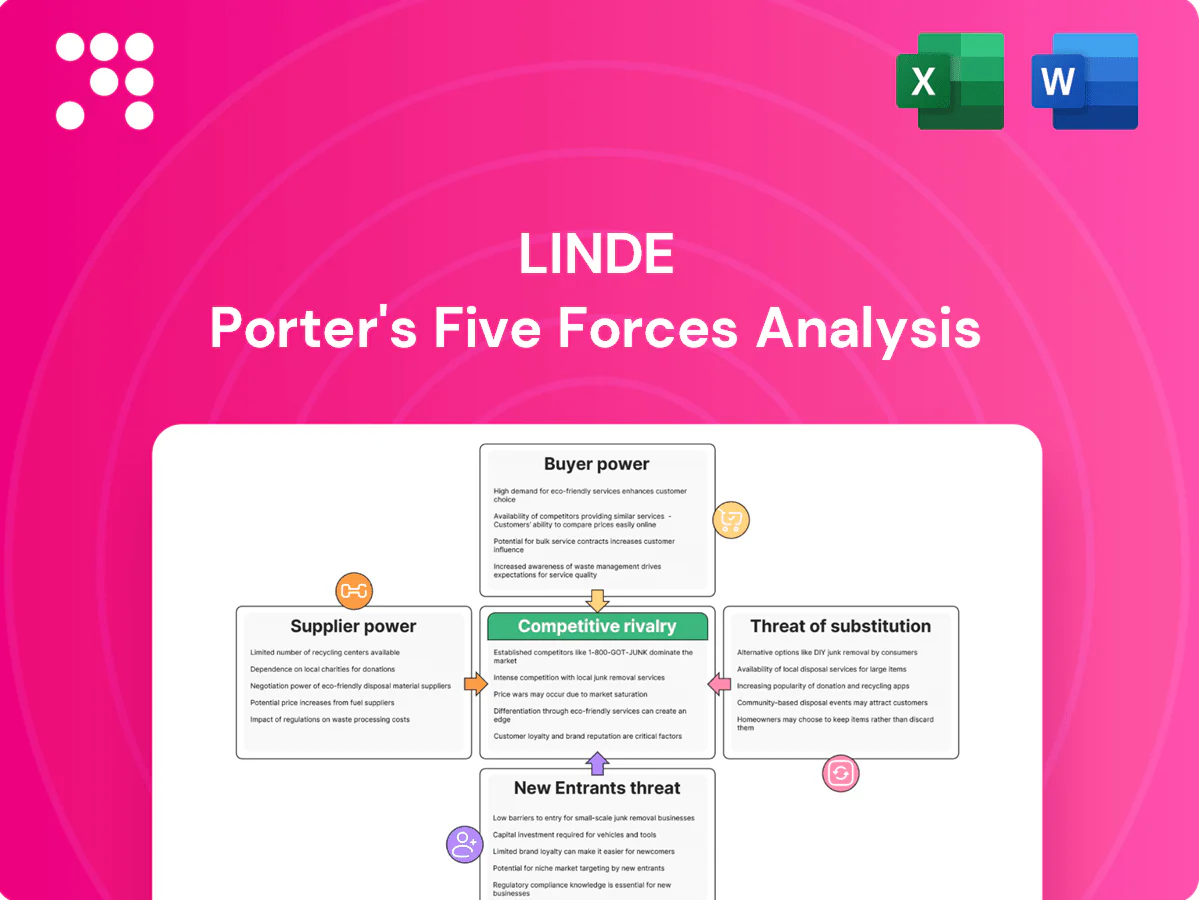
This preview shows the exact Linde Porter's Five Forces Analysis you'll receive immediately after purchase—no surprises or placeholders. The document is fully formatted and ready for download and use the moment you buy. No mockups or samples; this is the final deliverable.
Linde faces Air Liquide, Air Products, Nippon Sanso and Messer across regions; in 2024 rivalry remained disciplined in mature markets but sharpened around megaprojects, which often exceed $1 billion in capital value. Scale and network density drive measurable cost and service advantages through regional pipeline and on-site footprints. The oligopolistic structure limits broad price wars but intensifies aggressive bid competition for large contracts.
Long-term on-site and pipeline agreements (typically 10–20 years) lock in revenue and materially reduce churn-driven rivalry; the global industrial gas market was about USD 120 billion in 2024. Renewal battles center on service KPIs and incremental pricing (often 1–3%), while merchant and packaged segments face more frequent price competition. A large installed base delivers incumbency advantages, raising rivals’ entry costs.
High capex and uptime requirements push rivalry toward engineering excellence; large gas projects in 2024 still involve multi‑hundred‑million to billion‑dollar investments and target uptime often above 99.9%, shifting competition from price to reliability. Downtime penalties and safety KPIs prioritize quality; Linde’s engineering depth and presence in 100+ countries in 2024 bolsters defensibility, while the cost of failure deters weaker players from aggressive underbidding.
Emerging-market green hydrogen, CCUS and electronics fab projects draw intense, often 3–6+ bidder processes where technology partnerships and offtake structures determine winners; large electrolyzer deals and CCUS bids increasingly hinge on integrated supply and financing. Electronics fabs entail winner-take-most dynamics given capex per new leading-edge fab often exceeding 10 billion USD, while local content rules fold regional contractors into consortia.
In EPC, Linde faces head-to-head competition from specialized gas-process engineers and large diversified EPCs; in 2024 bids tightened as petrochemical and LNG cycles shifted capacity utilization and margins within the sector. Lump-sum, turnkey risk allocation often drives pricing tension and margin erosion on large projects. Linde leverages process IP and reference plants to differentiate offers and defend margins.
Linde competes with Air Liquide, Air Products, Nippon Sanso and Messer; 2024 global gas market ~USD 120bn and megaprojects often >USD 1bn, driving aggressive bid competition (3–6+ bidders). Long 10–20y on‑site contracts and 100+ country footprint reduce churn; EPC lump‑sum risk tightens margins. Green hydrogen/CCUS (~400 projects 2024) intensify tech/offtake battles.
| Metric | 2024 |
|---|---|
| Market size | USD 120bn |
| Megaproject capex | >USD 1bn |
| Bidders/project | 3–6+ |
| CCUS pipeline | ~400 |
| Country presence | 100+ |
Customers can install ASUs, PSA units or electrolyzers to bypass merchant supply; for very large, stable loads on-site can be economical. Electrolyzer CAPEX fell to roughly $1,000/kW by 2024, improving the business case for in-house H2. Linde counters with BOO/BOOM models and performance guarantees to match capex economics. Lifecycle costs, uptime and reliability often still favor outsourced supply.
Membranes, VPSA and catalytic routes can replace or shrink demand for bulk gases—VPSA typically yields 90–95% O2 purity and membranes enable on-site N2/O2 at lower CAPEX for small plants. Process intensification and recycling routinely cut gas consumption per unit by 20–40% in modern plants. Linde’s application engineering embeds optimized designs that raise switching costs, and its 2024 technology roadmaps reframe threats into service and retrofit revenue streams.
Nitrogen can replace argon or scarce helium in many inerting roles, while electrification is displacing hydrogen or oxy-fuel combustion in select processes; medical-device advances have cut oxygen use per patient in trials, and the 2024 global industrial gases market (~$147 billion) sees substitution as application-specific and often partial rather than full.
Recycling and recovery systems reduce fresh helium and specialty gas demand, but Linde supplies recovery solutions and thereby internalizes much of the substitution effect; Linde reported $41.4bn revenue in FY2024, showing diversified capture of these markets. Customers still need make-up volumes and ongoing service, producing margin-mixing rather than full displacement.
Bio-CO2 and point-source capture can displace traditional byproduct CO2; global CCUS capacity reached roughly 50 MtCO2/yr by 2024 with >200 projects in development, increasing alternative supply options.
Substitution is material but partial: on-site ASUs/PSA/electrolyzers (electrolyzer CAPEX ≈ $1,000/kW in 2024) and membranes/VPSA (O2 90–95%) reduce merchant volumes while recycling/CCUS (~50 MtCO2/yr capacity, >200 projects in dev. by 2024) cut fresh demand. Linde offsets via BOO/BOOM, recovery sales and engineering—FY2024 revenue $41.4bn—yielding margin-mix, not full displacement.
| Substitute | 2024 metric | Linde response |
|---|---|---|
| On-site H2/ASU | Electrolyzer CAPEX ≈ $1,000/kW | BOO/BOOM, guarantees |
| Membranes/VPSA | O2 purity 90–95% | Retrofits, application engineering |
| Recycling/CCUS | ~50 MtCO2/yr capacity, >200 projects | Recovery solutions, capture sales |
ASUs, liquefiers and pipeline networks carry heavy upfront capex, commonly in the hundreds of millions to >$1 billion range for large plants and trunk lines. Economies of scale and route density favor incumbents, reducing unit delivery costs and raising the minimum viable scale for entrants. Typical payback horizons run 7–15 years and contracted offtake pipelines lock capacity, while lenders demand proven track records, making financing difficult for newcomers.
Industrial gases involve hazardous operations and stringent compliance, and as of 2024 permitting timelines commonly span 1–3 years, slowing greenfield entry. End-markets demand certifications and audits such as ISO 9001 and ISO 14001 for qualification. Incumbents’ safety records create trust barriers that raise customer and regulator scrutiny.
Mission-critical customers demand proven reliability and redundancy, with industry expectations typically exceeding 99.9% uptime and multi-day liquid backup capacity for gases. New entrants rarely match incumbents on uptime guarantees or installed backup volumes, so switching risk remains high. Extensive embedded pipelines and on-site plants anchor Linde and peers, creating substantial switching costs and sustained gatekeeping.
As of 2024, helium sourcing, advanced cryogenics and process know-how are highly concentrated (US, Qatar, Algeria), making replication costly; incumbents use multi-year (≥10-year) supply contracts and proprietary plant designs to protect positions. OEM relationships, spare-part inventories and >6–12 month equipment lead times add friction, so entrants face steep learning curves and deployment delays.
Small players still enter cylinders, specialty niches, or focused geographies, often winning on service or price for non-critical volumes; scaling beyond niches is hard without bulk assets and logistics. In 2024 the global industrial gases market was about USD 88 billion, keeping consolidation pressure high as capex for bulk plants and distribution networks limits expansion.
High upfront capex (ASUs, liquefiers, pipelines >$100M–$1B) and long paybacks (7–15 years) create steep scale barriers. Stringent safety, 1–3 year permitting and uptime >99.9% raise trust and switching costs, while concentrated helium/supply sources and ≥10y contracts protect incumbents. Small entrants succeed in cylinders/specialty niches; 2024 global market ≈ USD 88 billion.
| Metric | 2024 Value | Note |
|---|---|---|
| Market size | USD 88B | Global |
| CapEx | $100M–$1B+ | Large plants/trunks |
| Payback | 7–15 yrs | Typical |


