
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
LSI Industries faces moderate supplier leverage, intense buyer price sensitivity in commercial lighting, and growing substitution pressure from LED integrators and smart lighting platforms. Competitive rivalry is high among niche manufacturers, while entry barriers remain moderate due to capital and regulatory needs. This brief snapshot only scratches the surface — unlock the full Porter's Five Forces Analysis to explore LSI’s competitive dynamics and strategic implications in detail.
Global availability of LEDs and power drivers, with China/Taiwan accounting for an estimated 65% of supply, moderates supplier leverage for LSI. LSI routinely dual-sources components from 2+ vendors per SKU to cut dependency. Qualification and certification cycles typically run 3–9 months, creating switching friction. Multi-year purchase agreements and volume commitments (1–5 year contracts) further balance supplier power.
Aluminum, steel and plastics experienced double-digit price swings in 2024, pressuring LSI Industries' margins as suppliers frequently passed through cost increases. Suppliers' input power rose with tighter metal markets and polymer feedstock volatility, raising COGS and margin risk. Hedging, value-engineered designs and scale purchasing (centralized buys) reduced exposure and improved negotiation leverage.
Custom optics, specialized controls and printed-graphics substrates narrow supplier options, with lead times often extending 8–20 weeks and lengthening supplier leverage during tight cycles. Extended lead times increase bargaining power; robust forecasting and safety stock materially reduce risk. Maintaining approved-vendor lists preserves sourcing flexibility and negotiation leverage.
Freight volatility (Drewry WCI ~1,800 USD/container average in 2024), US tariffs (steel 25%, aluminum 10%, Section 301 up to 25% on many Chinese electronics) and geopolitics shift bargaining power to suppliers; nearshoring and mixed sourcing reduce disruption risk, while LSI’s domestic plants cut exposure and logistics costs. Cost-sharing contract clauses further rebalance supplier terms.
UL, DLC, and energy-code compliance (DLC lists >30,000 products in 2024) tightly constrain supplier substitution for LSI, raising technical and documentation barriers that favor prequalified vendors.
High reliability expectations increase qualification hurdles, giving vetted suppliers greater pricing and delivery influence, while robust QA and multi-supplier qualification programs reduce single-supplier concentration risk.
Supplier power is moderate: China/Taiwan supply ~65% of LEDs/power drivers but LSI dual-sources and holds 1–5yr contracts to limit leverage. Commodity input volatility (metals/plastics double-digit swings in 2024) and freight (Drewry WCI ~1,800 USD/container) press margins; hedging and nearshoring mitigate. Certification (DLC >30,000 products) and long lead times raise switching costs.
| Factor | 2024 metric | Impact | Mitigant |
|---|---|---|---|
| Concentration | 65% China/Taiwan | Moderate | Dual-sourcing |
| Freight | WCI ~1,800 USD | Higher COGS | Nearshoring |
| Compliance | DLC >30,000 | Higher switching cost | Approved vendors |
 Detailed Word Document
Tailored Porter's Five Forces analysis for LSI Industries uncovering competitive drivers, buyer and supplier bargaining power, threats from substitutes and new entrants, and emerging disruptive forces; includes strategic commentary to assess pricing power, profitability risks, and defensive barriers for use in investor decks, business plans, or editable Word reports.

 Customizable Excel Spreadsheet
One-sheet Porter's Five Forces for LSI Industries—quickly spot supplier, buyer, and competitor pressures to streamline strategy and reduce execution risk.
QSR, petroleum and retail chains buy at scale and run competitive RFPs, using volume to push pricing and service levels and standardized specs that intensify price pressure; large accounts often demand centralized pricing, volume rebates and strict SLAs. LSI mitigates by offering turnkey, bundled lighting+controls solutions and value-added services that defend margins and shorten procurement cycles.
Buyers prioritize total cost of ownership, emphasizing energy savings (LED retrofits commonly cut lighting energy use 50–70%), lower maintenance and extended warranty coverage. Strong ROI cases—often delivering payback in 1–3 years—reduce pure price haggling. Performance guarantees and utility or state rebates (commonly covering a meaningful portion of retrofit costs) improve buyer acceptance. Data-backed proposals increase switching to LSI by demonstrating measurable lifecycle savings.
Custom graphics and integrated signage make apples-to-apples comparisons difficult, as bespoke specifications and engineering vary widely across projects. Tailored designs raise switching costs and extend timelines, reducing buyer leverage. Dedicated program management and phased rollouts add further stickiness, dampening customer bargaining power and favoring supplier pricing stability.
Buyers can choose from numerous lighting and signage vendors, and in 2024 expanded imports and private-label offerings have increased customer leverage; LSI must compete beyond price. Differentiation through proven quality, faster lead times, and superior service is critical. Strong reference projects and warranties remain key tools to defend pricing and margins.
Distributors, ESCOs and specifiers strongly shape LSI Industries purchasing paths, with 2024 market interactions shifting leverage toward channel partners as spec-driven projects rose. Focused channel programs and training reduce this buyer power by aligning incentives and technical preferences. Co-marketing, targeted rebates and pull-through tactics proved effective in 2024 at restoring manufacturer influence.
Large QSR, retail and fuel chains use volume RFPs and centralized pricing to pressure margins, but LSI’s bundled lighting+controls, service SLAs and warranties counteract this. Buyers focus on TCO—LED retrofits cut lighting energy 50–70% with typical payback 1–3 years—reducing pure price fights. Channel-led specs and rising imports in 2024 lifted buyer leverage, met by training, co-marketing and rebates.
| Metric | 2024 Value |
|---|---|
| LED energy savings | 50–70% |
| Typical payback | 1–3 years |
| Buyer leverage | Elevated (2024) |
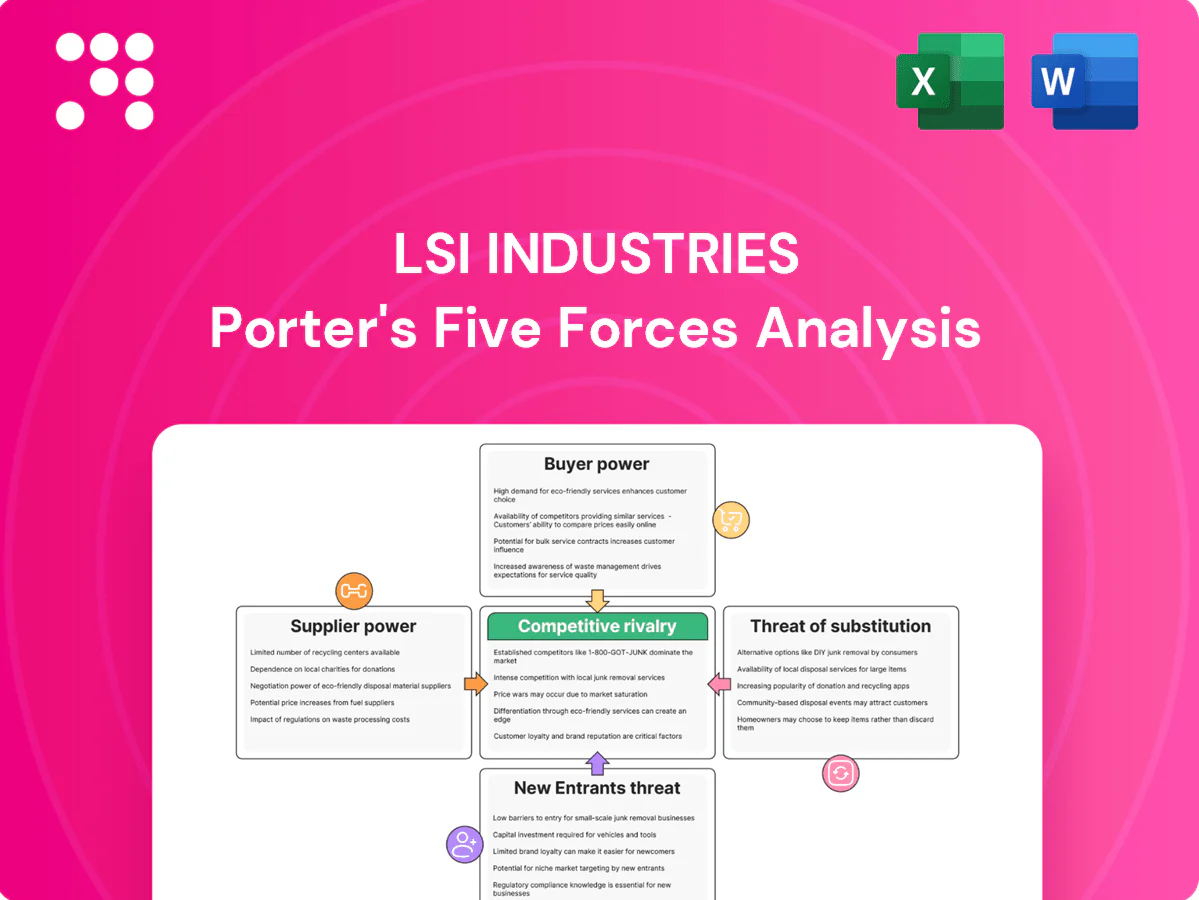
This preview shows the exact Porter's Five Forces analysis for LSI Industries you'll receive after purchase—no placeholders or edits. The document is fully formatted, actionable, and ready to download the moment you buy. Use this identical file for decision-making, reporting, or presentation without further setup.
In 2024 LSI faces a crowded lighting landscape competing with large rivals Signify, Acuity and Hubbell plus numerous niche specialists. Rivalry is intense in project bids and national accounts where contract scale and service depth matter. Brand strength, proven reliability and fast delivery often determine wins. Price competition remains persistent, squeezing margins across commercial and municipal segments.
Graphics and digital signage face rivals from display OEMs to systems integrators in a global market estimated at about 23 billion dollars in 2024 with a ~7.5% CAGR. Bundled end-to-end solutions intensify rivalry versus point products, while content management platforms and services—installation, analytics, maintenance—differentiate offerings. For LSI, end-to-end capability can be decisive in winning larger, higher-margin contracts.
Rapid advances in LEDs, optics and IoT controls force continual product refresh at LSI, compressing lifecycles and pressuring margins as component commoditization intensifies. Differentiation via smart controls, analytics and integrated services is now a primary competitive weapon. Falling component costs squeeze gross margins unless offset by higher-value software and data features. Lagging innovation risks market share loss to faster, control-focused rivals.
Project-based, spec-driven selling lets architects and engineers lock in suppliers via specs; value engineering can reopen bids but often triggers price cuts and margin pressure. Pre-approval and proven performance drive selection; long-term relationships and rapid service responsiveness win tight contests.
Short lead times and dependable after-sales support are competitive battlegrounds for LSI Industries; fiscal 2024 net sales of about $369 million underscore scale where warranty strength signals quality and reduces buyer risk, while poor field performance can quickly erode share; operational excellence and a sub-6-week commercial lead time target sustain edge.
In 2024 LSI faces intense rivalry from Signify, Acuity and Hubbell plus niche specialists; price pressure and contract scale compress margins despite $369M net sales. Advances in LEDs, optics and IoT shorten product lifecycles, pushing higher-value software/services to sustain gross margins. Fast delivery, warranties and service responsiveness remain decisive in bids.
| Metric | 2024 |
|---|---|
| Net sales | $369M |
| Display market | $23B global |
| Display CAGR | ~7.5% |
Low-cost fixtures and signage from importers and private labels intensified in 2024, pressuring branded margins as buyers accept lower specs for commodity applications; LSI emphasizes quality, regulatory compliance, and total lifecycle value to differentiate. Certification, documented warranty claims, and existing spec listings continue to favor established brands in procurement and institutional contracts.
Mobile, social, and in-app promotions increasingly substitute for traditional signage as global social media users reached 4.9 billion in 2024. Digital marketing channels can compress demand for physical displays and pressure margins. Integrated omnichannel strategies can reposition signage as a complementary touchpoint. Analytics-enabled, data-driven signage helps LSI defend relevance by proving measurable ROI.
Natural light strategies and skylights can cut electric lighting use by up to 60% (US DOE) and reduce fixture counts. High-performance building envelopes can lower overall lighting and HVAC loads by roughly 30% (IEA/2024 analyses). LSI can pivot to controls, adaptive solutions and integrated daylight harvesting to remain embedded. Retrofit opportunities persist as building stock upgrades continue to outpace new construction in 2024.
Legacy fluorescent and HPS in back-of-house areas act as low-cost substitutes as operators defer upgrades; LEDs can cut lighting energy use by up to 70% and often lower TCO by 30–50% (2024 industry estimates), but perceived short-term savings fuel deferral. Education on TCO, maintenance savings (fewer relamps, lower labor) and 2024 incentive programs unlock conversions.
Facility managers increasingly purchase simple lighting and controls direct via e-commerce, bypassing turnkey providers; US e-commerce penetration rose to about 18% of retail sales in 2024, signaling stronger online procurement trends that threaten LSI’s project margins. LSI can counter with standardized kits and streamlined ordering platforms while bundling installation, maintenance, and analytics to retain higher-margin service revenue.
Import/private-label fixtures and 2024 low-spec imports pressure margins; brand value (certs, warranties, spec listings) preserves institutional share. Digital channels (4.9B social users in 2024) and e-commerce (US ~18% in 2024) substitute signage demand. Daylighting (up to 60% electric cut) and LEDs (~70% energy cut; TCO −30–50%) shift purchase timing; LSI counters with controls, analytics, bundles.
| Threat | 2024 Data |
|---|---|
| Digital substitution | 4.9B social users |
| E‑commerce procurement | US ~18% retail |
| Energy tech impact | LEDs ~70% energy; TCO −30–50% |
Contract manufacturing lowers production capital needs for LSI, but the credibility bar remains high in 2024: certifications, multi-year warranties and legacy reference projects are costly to replicate. New entrants struggle to gain spec acceptance from large customers and design engineers, slowing market entry. LSI’s established service networks and field support further raise operational hurdles for newcomers.
Distributor and specifier relationships remain sticky, with approved-lists and shelf-space rules favoring incumbents and raising switching costs for buyers. New entrants face heavy upfront channel investment in marketing, stocking and specifier outreach to breach these barriers. As of 2024 LSI sustains long-term distributor agreements and specifier programs that reinforce penetration and defend market share.
UL, DLC and state energy codes require third-party testing and documentation, with lab testing often costing $20,000–$100,000 per luminaire and DLC fees/additional testing commonly $5,000–$50,000 in 2024, raising upfront capital needs. Ongoing standards updates—energy codes typically revised on a 3-year cycle—add time and compliance risk that slows new entrants. LSI’s established QA and certification pipelines reduce per-product time-to-market and lower failure rates, creating a barrier to entry.
Core LED technology is widely available, with the global LED lighting market ~61.2 billion USD in 2024, lowering IP entry barriers; however, systems integration and software expertise (controls, commissioning) remain key differentiators. Proprietary data, controls and platform integrations create customer stickiness and recurring revenue potential. Ongoing product and firmware improvements help maintain a moving moat.
E-commerce marketplaces let small lighting brands launch rapidly, with 2024 US e-commerce penetration near 17% driving discovery. Early traction often comes from lower prices rather than product performance. Customer reviews and warranty obligations filter out weak entrants. LSI’s established brand, national service network and OEM expertise reduce this noise.
Contract manufacturing lowers capex but certifications, warranties and distributor lists keep credibility hurdles high in 2024. Testing costs (lab $20k–$100k, DLC $5k–$50k) and 3-year code cycles slow entrants. LED market $61.2B (2024) eases tech entry, while integration/software and controls create stickiness. E-commerce (US 17% penetration) enables fast, price-led entry, filtered by reviews/warranties.
| Metric | 2024 |
|---|---|
| LED market | $61.2B |
| Lab test | $20k–$100k |
| DLC/testing | $5k–$50k |
| US e‑commerce | 17% |


