
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
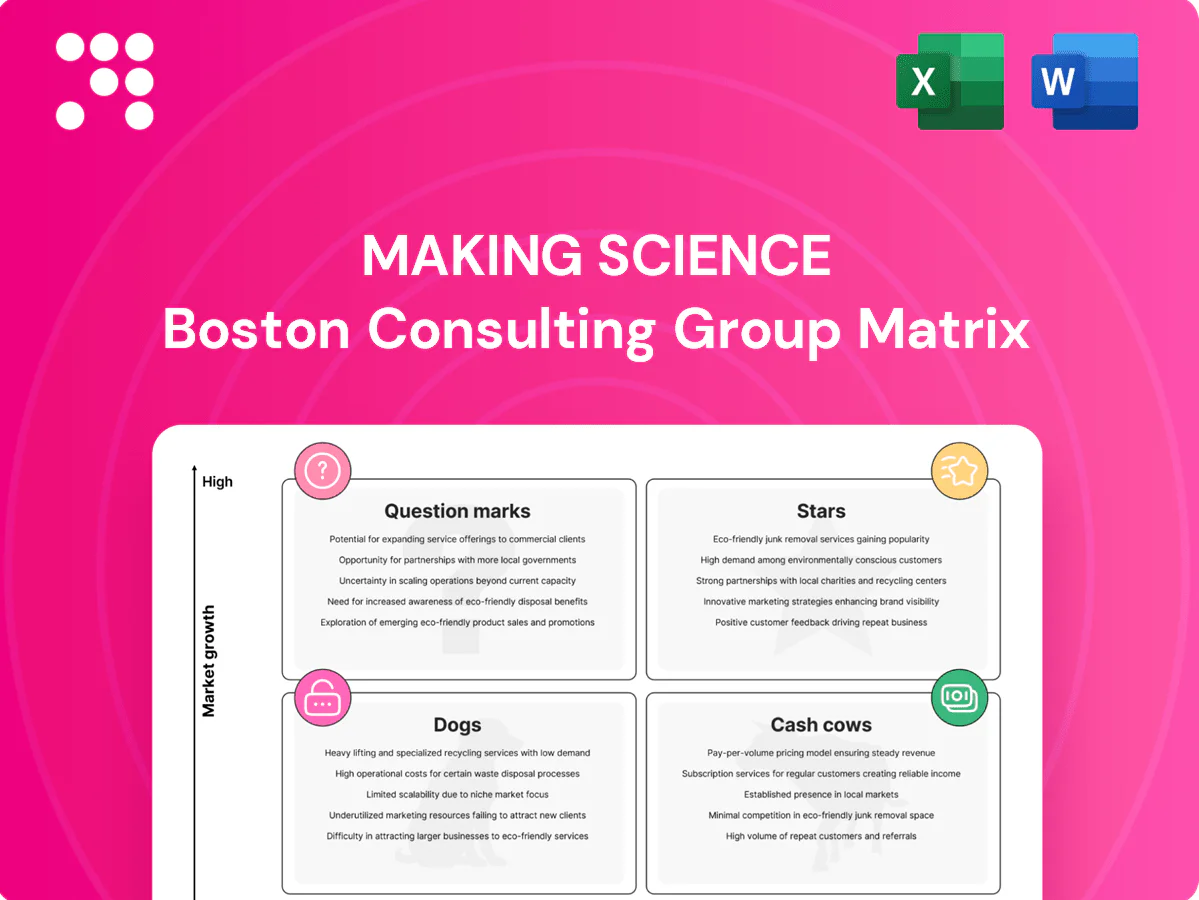
Curious where this company’s offerings land—Stars, Cash Cows, Dogs or Question Marks? This Making Science BCG Matrix preview teases the picture; buy the full report for quadrant-by-quadrant placement, data-backed recommendations and ready-to-use Word and Excel files. Get instant clarity and a practical roadmap for smarter investment decisions.
Data analytics & measurement suites are Stars for Making Science: we hold a high market share in analytics-led engagements as the marketing analytics/CDP market expands (CDP market ~2.4B in 2023 with ~20% CAGR toward 2030). Clients demand attribution clarity, CDPs and faster decisions — the core value. It consumes cash in specialists and tooling but generates influence and sticky revenue; continued investment should mature it into a reliable cash engine.
Performance digital advertising sits as a Star for Making Science: leader in paid search, social and programmatic with tailwinds from a global digital ad market near $665B in 2024; always-on budgets and measurable ROI drive growth. Heavy investment in talent, optimization tech and experimentation raises CAC but boosts average ROAS and global scale. Sustain share and it will transition into Cash Cow.
Businesses are racing to modern data stacks and AI-driven decisioning—Gartner noted enterprise AI investments grew about 20% year-over-year in 2024, making this a prime growth star. Making Science can architect and deploy modern cloud data platforms and then activate models into media and CRM to drive measurable ROI. Upfront capex for skills and strategic partnerships is high, but cloud spending exceeded roughly $600B in 2024, showing undeniable category momentum. Invest to lock in lighthouse wins and scale client proofs into recurring revenue.
Checkout, feeds, CRO and merchandising are top-priority in 2024 as global e-commerce surpassed 6 trillion USD, with clients reporting weekly conversion uplifts that enable fast market scaling. These levers are budget-backed and require continuous testing, tooling and analyst capacity — cash-intensive but strategic. Sustaining share through CRO compounds into margin over time.
International multi-market orchestration is a Stars play: global clients demand a single partner with local execution, creating a durable moat; by 2024 more than 100 countries had data localization rules, boosting demand for regional compliance and localization. Cross-border media and data governance are high-growth areas, coordination costs exist but drive account stickiness; keep funding playbooks and regional teams.
Data analytics/CDP: ~2.4B market (2023) with ~20% CAGR; high share, cash-burning build to sticky recurring revenue.
Performance ads: global digital ad market ~665B (2024); leader in search/social/programmatic, investment drives ROAS and scale.
AI/data, CRO, international orchestration: enterprise AI spend +20% YoY (2024); e‑commerce ~6T (2024); 100+ countries with data localization (2024).
| Segment | 2024 Metric | Growth | Investment |
|---|---|---|---|
| Analytics/CDP | 2.4B (2023) | ~20% CAGR | Specialists+tooling |
| Performance Ads | 665B market | Steady digital growth | Talent+tech |
| AI/Data & CRO | AI spend +20% YoY | High | Cloud+skills |
| Intl Orchestration | 100+ localization laws | Rising | Regional teams |
 Detailed Word Document
In-depth BCG review of Making Science products, with strategic moves per quadrant—invest, hold, or divest; risks and market trends.

 Customizable Excel Spreadsheet
One-page Making Science BCG Matrix highlighting portfolio gaps and quick action points for faster strategy decisions
SEO and content operations sit in the cash cows quadrant with mature demand, proven playbooks and steady retainers—2024 agency benchmarks show median retainer lengths of 12–18 months and predictable ARR streams. Margins rise to roughly 30–40% EBITDA when templates, tooling and offshore hybrids are applied. Growth is slower but churn is low (around 8–12% annual). Milk process efficiency while keeping quality tight.
Analytics implementation and dashboard upkeep—GA4 migration, tag management, and BI maintenance—are predictable, repeatable services; GA4 became the default property type for new Google Analytics properties in 2023. These offerings hold a high share within existing clients with stable renewals and strong unit economics despite low net-new growth. Standardize playbooks, templates, and SLAs to preserve margins and scalability.
Programmatic managed services maintain a well-defended share with established trading practices and partner discounts, benefiting from programmatic accounting for ~86% of US digital display spend in 2024. Market growth is moderate while spend volume remains reliable, driving steady revenue. Efficiency gains from automation flow to the bottom line; maintain service quality and automate routine tasks to protect margins.
Marketing automation & CRM ops drive recurring, sticky lifecycle campaigns, journeys, and hygiene that create predictable, repeatable revenue; tooling is stable and onboarding is standardized. In 2024 the marketing automation market was ~7.3B and CRM software ~60B, reflecting steady demand rather than explosive growth. Cash flows are dependable; invest in accelerators and automation to lift margins and reduce service cost.
Cloud managed services & support is a mature cash cow: post-migration care emphasizes cost optimization and SLA-based support with renewals typically above 85% in the MSP sector (ConnectWise 2023–24); attach rates on data clients are solid, often ~40% for adjacent services. Growth is low but predictable; scaling relies on standardized runbooks and governance, which Forrester 2024 found can cut MTTR by up to 30%.
SEO/content, analytics, programmatic, automation and cloud support form cash cows: mature demand, repeatable playbooks, steady retainers (median 12–18 months), 30–40% EBITDA, low churn (8–12%) and high renewals (>85%). GA4 default since 2023; programmatic ~86% of US display spend (2024). Invest in templates, automation and runbooks to preserve margins.
| Service | Metric | Margin | Renewal/Churn |
|---|---|---|---|
| SEO/Content | Retainer 12–18m | 30–40% EBITDA | Churn 8–12% |
| Analytics | GA4 default | 30–40% | High renewals |
| Programmatic | 86% display spend | 30–40% | Stable |
| Automation/CRM | Market 7.3B/60B | 30–40% | Sticky |
| Cloud Mgt | Attach ~40% | 30–40% | >85% renewal |
The file you're previewing here is the exact BCG Matrix document you'll receive after purchase—no watermarks, no demo text, just the finished file. It’s formatted for clarity and built for immediate use in strategy sessions, investor decks, or internal reviews. After buying, the full version is instantly downloadable and ready to edit, print, or present to stakeholders. No surprises—just a market-tested tool that saves you time and sharpens decision-making.
One-off brochure websites sit in a low-growth segment (≈3% CAGR in web development services, 2024), highly commoditized and relentlessly price-shopped. They offer minimal strategic value and impose high context-switching costs on teams. Cash often sits idle in small, non-scalable projects with thin margins. Divest or only include as add-ons within larger, strategic deals.
Legacy on‑prem marketing stack integrations are Dogs: demand is declining as clients go cloud-first—Gartner predicts 85% of enterprises will adopt a cloud-first principle by 2025. They are complex, costly, and hard to staff, often incurring 2–3x higher operating expense versus cloud alternatives. At best they break even after opportunity cost; recommended action: sunset or migrate clients to modern platforms.
Pure print or OOH-only services sit outside core digital acceleration and are hard to differentiate, with digital capturing about 68% of global ad spend in 2024 and compressing demand for traditional formats. They show low data leverage and thin margins, often below industry averages as advertisers shift to measurable channels. These offerings consume management attention without strategic upside; partner out or exit is recommended.
Custom adtech builds with narrow adoption carry high upfront costs and limited market fit, often generating lumpy, slow revenue and heavy ongoing maintenance; 2024 industry benchmarks show maintenance commonly consumes 15–20% of initial development spend annually and many bespoke projects exceed budgets by ~30%, tying engineers to non-scalable work.
Basic banner production sits in Dogs: race-to-the-bottom pricing and frequent heavy revisions create low margins and little defensibility; 2024 market rates show offshore vendors offering banners from 15 to 75 USD, undercutting agency rates and adding noise, not strategic value; automate or discontinue unless bundled with media buying.
Dogs: low-growth, commoditized services (≈3% CAGR for one-off sites; digital ad spend 68% in 2024) with thin margins, high maintenance (adtech 15–20%/yr), and declining demand (cloud-first 85% by 2025). Divest, sunset, or bundle only as add-ons; migrate legacy clients. Automate or partner for banners/print.
| Offering | 2024 metric | Action |
|---|---|---|
| One-off sites | ≈3% CAGR | Divest/add-on |
| Legacy on‑prem | 85% cloud-first by 2025 | Sunset/migrate |
| Print/OOH | 68% digital share | Partner/exit |
| Custom adtech | 15–20% maint./yr | Cut/license |
| Banners | $15–75 offshore rates | Automate/bundle |
Explosive interest in GenAI creative and content automation is evident—ChatGPT passed 100 million monthly users in 2023 and McKinsey estimates generative AI could unlock 2.6–4.4 trillion USD in annual value, yet playbooks and budgets remain uneven across teams. It can unlock speed and personalization at scale but requires IP guardrails and measurable lift via A/B tests and attribution. Bet selectively on lighthouse cases with clear ROI and phased rollouts.
Retailers are scaling ad businesses rapidly — US retail media ad spend reached about $71 billion in 2024, growing ~16-20% YoY; brands are chasing that spend. Making Science can bridge data, product feeds and closed-loop attribution to capture early share. Market share is still forming — land now or lose later; prioritize investments where categories are consolidating and winner-takes-most dynamics are emerging.
Regulation like GDPR (2018) and platform moves such as Apple ATT (2021) and Chrome cookie delays have reduced third-party identifiers and pushed demand for privacy-first clean rooms. The market is fragmented across vendors and verticals, enterprise sales cycles typically run 6–12 months and are technical. If MS delivers interoperable measurement and proven ROI early, this can become a scalable growth engine. Build partnerships and run outcome pilots to shorten adoption.
CTV/OTT advanced measurement sits in the Question Marks quadrant as spend shifted ~25% in 2024 to roughly $21B in US CTV ads, yet attribution lags behind impressions-to-conversion timelines; brands pay to crack incremental lift and cross-channel frequency optimization. Tooling and standards remain in flux across ID-less environments and probabilistic matching, so pilot programs with performance-minded advertisers accelerate validation and willingness to pay.
Retail sensors and edge events can power smarter merchandising by enabling in-aisle heatmaps, shrink detection and near-real-time inventory signals, but adoption remains nascent with only about 15% of retailers running edge analytics at scale in 2024. Complex integrations across legacy POS, inventory and cloud platforms slow decision velocity and raise TCO; packaged, turnkey edge+analytics offerings can differentiate Making Science’s data practice if they reduce deployment time and integration cost. Pilot with select innovators and stage investments to prove ROI before scaling.
Question Marks: GenAI adoption surges (ChatGPT 100M users 2023; McKinsey $2.6–4.4T potential) but ROI playbooks scarce; retail media is expanding (US ~$71B 2024) with winners emerging; CTV spend ~ $21B US (2024) yet attribution lags; edge analytics adoption ~15% of retailers (2024), integration cost delays scale.
| Area | 2024 | Key challenge |
|---|---|---|
| GenAI | 100M users (2023); $2.6–4.4T value | proof of lift |
| Retail media | $71B US | competition, attribution |
| CTV | $21B US | attribution/tools |
| Edge analytics | 15% retailers | integration/TCO |


