
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
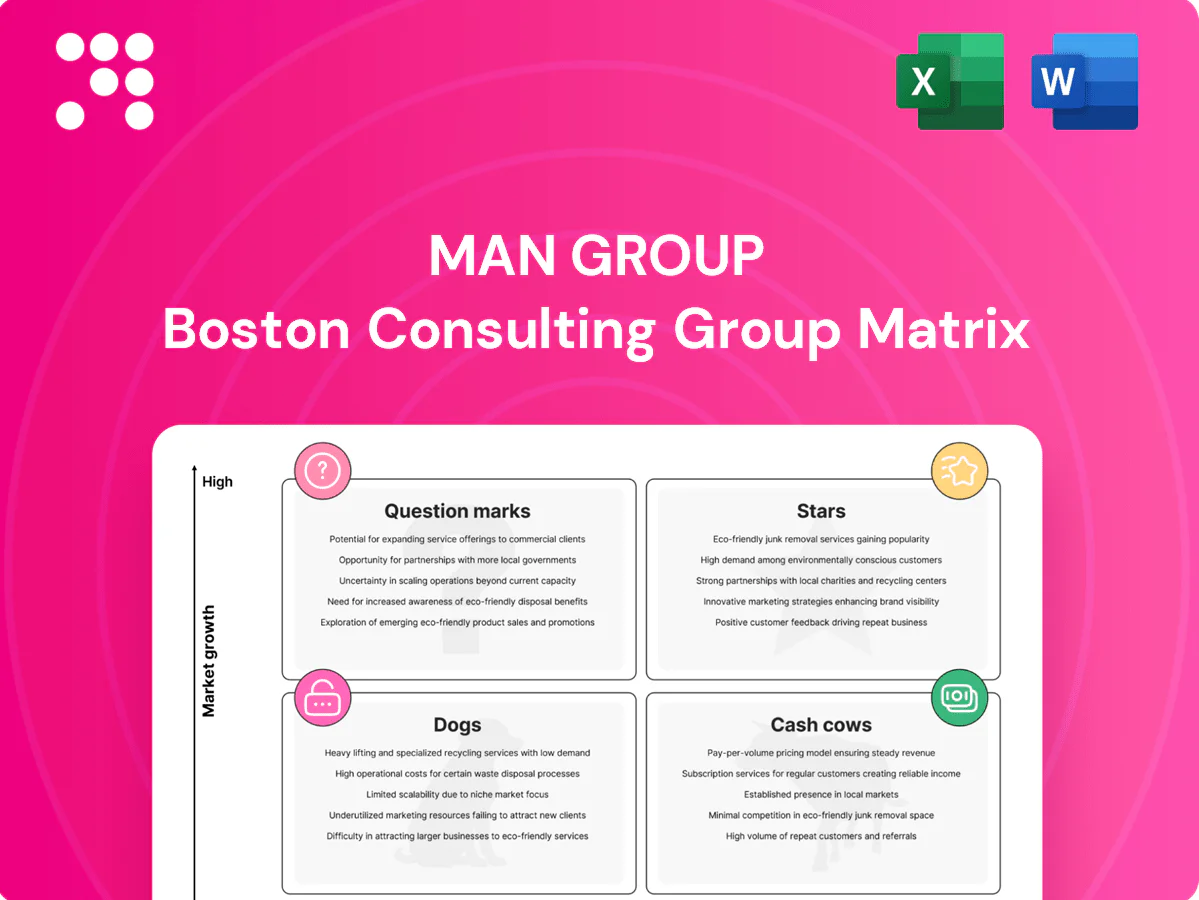
Man Group’s BCG Matrix peels back the fog on which strategies are driving growth, which funds are reliable cash cows, and where capital’s being wasted — a crisp snapshot for any investor or exec. This preview shows the shape of their portfolio; the full BCG Matrix gives you quadrant-by-quadrant placement, data-backed recommendations, and tactical moves tailored to Man’s market position. Buy the full report for an editable Word + Excel pack that lets you act fast with confidence.
Managed futures (systematic trend) sees high-growth demand in 2024 as allocators chase uncorrelated returns and crisis convexity; Man Group’s deep quant capabilities give it meaningful market share and brand pull. The strategy remains capex-intensive—models, data and infra consume ongoing investment—so keeping the lead compounds into a dominant, lower-growth franchise. For now, feed it: performance marketing and distribution materially drive flows in 2024.
Volatility has renewed demand for multi-asset absolute return platforms, driving inflows that lifted Man Group’s MAAR-related assets to about $105bn by mid-2024 and re-establishing relevance.
Scale plus tech-enabled research (quant models, ML) underpin leadership, but these strategies still require heavy investment in risk infrastructure, distribution and product development.
If market growth normalizes while share holds, MAAR can mature into a cash cow; until then Man must keep investing to stay on top.
Structural tailwinds—bank retrenchment and higher base rates (Fed funds ~5.25% in 2024)—plus stronger covenants fuel Man Group’s private credit and specialty finance book; global private debt AUM reached about $1.3tn in 2024 (Preqin). Growing book and opportunity set remain resource-hungry on sourcing, underwriting and risk systems. Maintain win rates and platform discipline to convert momentum into durable margins; star today, cow tomorrow if growth moderates.
Systematic macro beyond trend—carry, relative value and alternative risk premia—won fresh allocator budgets in 2024 as alternatives AUM hit $14.3tn (Preqin 2024); tech and research velocity give Man Group a measurable edge but continuous model upkeep raises operating cost intensity, and scaling is attractive only after share is secured as category growth cools.
Europe’s liquid-alts UCITS market reached roughly €220bn AUM in 2024, with cross-border distribution and passporting continuing to expand. Established track records give Man Group leadership, but winning shelf space demands sustained marketing and compliance investment. Maintaining performance and placement locks the lane; growth typically slows over time while unit economics improve.
Man Group’s Stars (managed futures, MAAR, systematic macro) show strong 2024 growth: MAAR AUM ≈ $105bn mid-2024, alternatives AUM $14.3tn and private debt $1.3tn (Preqin), with EU UCITS ≈ €220bn; scale, quant R&D and distribution drive share but require heavy ongoing capex, positioning Stars to mature into cash cows if growth normalizes.
| Metric | 2024 value | Implication |
|---|---|---|
| MAAR AUM | $105bn | Market leadership |
| Alternatives AUM | $14.3tn | Rising allocator flow |
| Private debt | $1.3tn | Resource-hungry |
| EU UCITS | €220bn | Distribution scale |
 Detailed Word Document
Concise BCG Matrix analysis of Man Group’s units, showing Stars, Cash Cows, Question Marks and Dogs with investment guidance.

 Customizable Excel Spreadsheet
One-page BCG matrix placing Man Group units in quadrants — clean, export-ready for quick share or C-level printouts.
Long-only quantitative equities (core/enhanced) are mature, sticky mandates with clear risk budgets delivering steady fees and predictable flows. In 2024 they represented a high share of certain Man sleeves (around 25–35% of discretionary equity AUM) while category growth stayed modest (low single-digit % YoY). Marketing lift is low; margin gains come from execution and scale — optimize infrastructure and avoid overspending.
Hedge fund solutions and advisory are durable, relationship-led mandates that generate more cash than they consume, benefiting from operational leverage as scale improves margins. In 2024 the focus remained on defending share via enhanced risk controls, transparent reporting and elevated client service. Strategy: milk core flows, maintain market position and selectively modernize products and tech to sustain cash generation.
Discretionary long-only equity franchises are well-known processes with loyal institutional clients and limited category growth, making them classic cash cows for Man Group. With group AUM above $100bn in 2024, these franchises deliver strong margins when capacity is sensibly managed and fees defended. Marketing spend is minimal beyond consultant coverage, so focus is on harvesting cash while keeping performance hygiene tight. Retain risk controls and strict capacity governance to sustain yield.
Risk overlays and portfolio insurance sit as Cash Cows for Man Group: mature institutional demand drives stable, recurring fee income with low growth; strong process and systems deliver high efficiency per dollar of AUM, enabling funding for broader platform R&D; maintain tight SLAs and a lean engine to protect margins. Man Group AUM ~146bn USD (2024) supports scalable funding of innovation.
Established multi-strategy UCITS ranges deliver steady net revenue, supported by Man Group AUM of $131bn in 2024 and consistent distributor traction; incremental sales arise mainly from adviser and platform relationships rather than large marketing campaigns.
Man Group cash cows—mature long-only equities, hedge fund solutions, risk overlays and UCITS—generate stable, recurring fees with low single-digit % YoY growth and high operational efficiency. In 2024 these franchises funded platform R&D while requiring minimal marketing; focus on capacity governance, performance hygiene and lean ops to preserve margins.
| Metric | 2024 |
|---|---|
| Group AUM | ~146bn USD |
| Discretionary equity share | ~25–35% of sleeve AUM |
| Category growth | Low single-digit % YoY |
The file you’re previewing is the exact Man Group BCG Matrix report you’ll receive after purchase. No watermarks, no placeholders—just the finalized, fully formatted strategic analysis. It’s ready to edit, print, or present to stakeholders. Delivered instantly to your inbox with clear visuals and actionable insights. No surprises, just plug-and-play clarity.
Under-scale regional equity niches are small, crowded categories with limited client appetite and typically product AUM under $100m, leaving firms with low market share and high per-client servicing costs. They tie up portfolio teams and compliance resources for marginal fees and returns; industry practice shows many such strategies fail to cover fixed costs. Turnarounds are costly and seldom move the needle, so consolidation or exit is the prudent course.
Legacy structured product wrappers are complex, high-touch offerings that many institutions largely abandoned by 2024, leaving Man Group with slow revenue trickles and persistent operational drag. Break-even at best, these products consume compliance, legal, and servicing capacity and often distract from scalable strategies. Recommend aggressive simplification or wind-down to reallocate resources to higher-growth, lower-cost businesses.
Retail share classes with fee caps sit in Dogs: persistent low margins and rising servicing costs in 2024 erode profitability, while weak distribution leverage means scale often cannibalises institutional economics. Cash-trap dynamics appear quickly as net flows need to cover fixed servicing overheads. Prune SKUs or actively migrate holders to consolidated institutional-fee wrappers to stop margin leakage.
Dogs: Obscure thematic long-only funds — fad-driven categories lost sustained growth and never reached scale; Morningstar noted thematic strategies saw net outflows into 2024, reflecting weak investor appetite. Marketing costs routinely exceed realistic upside; expense ratios often >0.60% with sub-1% AUM growth. Even with tweaks, addressable market remains thin; consider merging these strategies into core mandates or shuttering underperformers.
High-cost bespoke mandates at Man Group are customization-heavy, fee-light structures that typically account for under 2% of firm AUM in 2024 and carry single-client concentration risk often exceeding 20% of a mandate.
Operational burden remains fixed whether assets stay or leave, compressing margins (fixed op costs ~70% of mandate cost base) and delivering minimal growth (<1% p.a. by design).
Exit typically occurs at renewal or if fees are materially repriced, making these Dogs strategically low-share, low-growth, high-risk client exposures.
Dogs at Man Group: sub-$100m regional equity niches, legacy wrappers and thematic long-only funds showing net outflows into 2024; fee compression (expense ratios often >0.60%) and growth <1% p.a. leave low market share and high servicing costs. Bespoke mandates <2% firm AUM with single-client concentration >20% and fixed ops ~70% of mandate costs, prompting consolidation or exit.
| Metric | Value (2024) |
|---|---|
| Typical AUM | <$100m |
| Expense ratio | >0.60% |
| Growth | <1% p.a. |
| Bespoke AUM share | <2% |
| Concentration | >20% |
Private markets secondaries and NAV lending sit in a rapidly expanding ecosystem—global private capital AUM surpassed $11.6 trillion in 2023, while secondaries remain a low-single-digit percent slice, indicating an early-stage share.
Building scale is capital-intensive: networks, analytics and credit risk infrastructure require significant investment.
A few flagship secondary/NAV wins could flip this to a Star; if traction lags, redeploy capital.
Volatile, high-growth space with institutional interest warming: global crypto market cap ~ $1.6tn in 2024 and spot BTC ETFs drew >$40bn inflows in 2024.
Tech and quant DNA fit Man Group but regulatory and custody hurdles keep share low for now.
A few anchor mandates could change the curve; invest selectively and fast-fail if pipes don’t clear.
Policy tailwinds in 2024—notably broader TNFD uptake and EU SFDR enforcement—have accelerated allocator interest in transition and nature-based private credit, but underwriting frameworks remain nascent. Growth potential is large from a currently small base, requiring Man Group to build specialist expertise and third-party data validation to earn trust. Mandate-level diligence and rigorous verification of carbon and biodiversity metrics are essential. If unit economics fail to firm up, pivot away.
Tokenized SMA infrastructure is a Question Mark: infrastructure race with high upside but uncertain standards; private markets AUM ~$11.5tn in 2024 suggests large addressable alts liquidity if tokenized, yet Man Group holds low share today and faces fragmented protocols and regs.
APAC onshore partnerships sit as Question Marks: the regional onshore asset-management market exceeded $30 trillion in 2024 and is growing ~7–9% annually, but licensing and regulatory entry barriers slow go-to-market; early local mandates could unlock distribution flywheels, yet current build costs outpace fee income while momentum remains uncertain.
Question Marks: private markets secondaries/NAV lending (global private AUM $11.5tn 2024; secondaries low-single-digit %) show high upside but need heavy infra; tokenized SMAs face fragmented regs despite ~$11.5tn addressable alts; APAC onshore (AUM >$30tn 2024, 7–9% CAGR) requires local licenses; transition/nature private credit demand rising but underwriting nascent.
| Opportunity | 2024 metric | Key action |
|---|---|---|
| Secondaries/NAV | Private AUM $11.5tn; secondaries low-single-digit % | Build infra; pilot flagship mandates |
| Tokenized SMA | Addressable alts ~$11.5tn | Client pilots; regulatory guardrails |
| APAC onshore | AUM >$30tn; 7–9% CAGR | Stage-gate local partnerships |


